AEPS Best Company: How to Choose the Right AEPS Partner
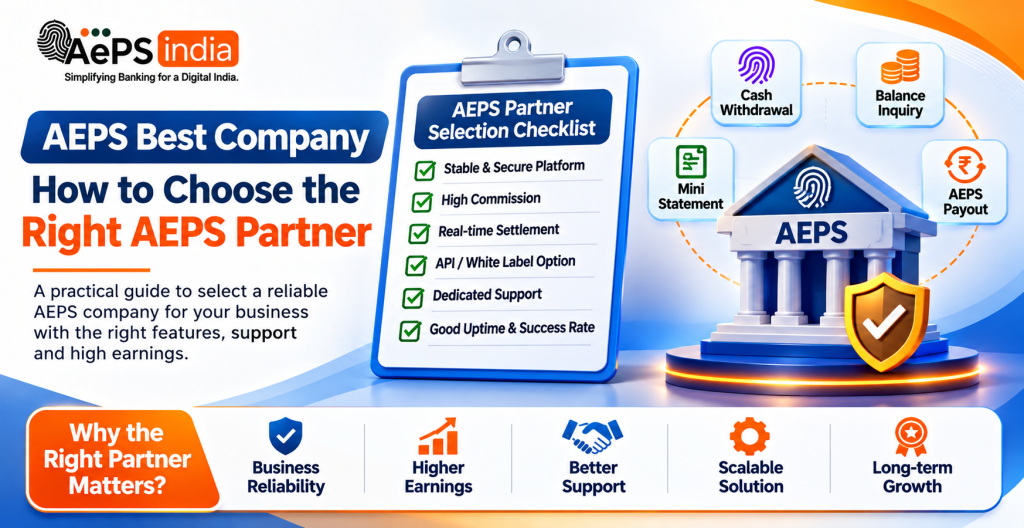
Finding the AEPS Best Company is an important decision for fintech startups, payment businesses, distributors, retailers, and entrepreneurs who want to enter or expand in India’s digital banking and financial services market. A reliable AEPS solution should offer more than basic Aadhaar-enabled transactions. Businesses need dependable Aeps API integration, biometric device compatibility, transaction monitoring, retailer and distributor management, commission control, wallet management, and proper technical support to operate their AEPS business efficiently. Whether you want to start AEPS business, build your own branded banking platform, or integrate Aadhaar Enabled Payment System services into an existing application, choosing the right technology and service partner can make a significant difference.
Top Aadhaar Enabled Payment System (AePS) service providers in India are chosen for their high transaction success rates, instant settlements, security compliance, and retailer-friendly commissions.
The best AEPS (Aadhaar Enabled Payment System) company depends on whether you are looking for a rural retail agency network or a developer-friendly API platform.
Aeps India provides AEPS software and integration solutions designed to help businesses develop and manage their own digital banking platforms. With solutions such as AEPS API integration, white label AEPS software, Aeps admin panel, Aeps retailer panel and Aeps distributor panel, businesses can build a structured platform around their operational requirements. The system can be configured to manage user onboarding, transaction records, wallet or ledger operations, commission structures, service controls, and business reports from a centralized administration dashboard.
When evaluating the AEPS Best Company in India, it is important to understand the essential banking services and technical capabilities available through the selected AEPS infrastructure. Depending on the participating banking and service arrangements, AEPS can support cash withdrawal, balance enquiry, mini statement, and cash deposit services through Aadhaar-based biometric authentication. Compatible biometric devices, proper authentication workflows, secure Aeps API communication, transaction-status verification, and accurate transaction records are equally important for maintaining a reliable customer experience. Businesses should also check how the solution handles pending transactions, failed requests, reversals, and reconciliation.
For businesses planning to build a larger fintech network, an advanced AEPS platform should also provide separate access and management facilities for administrators, master distributors, distributors, and retailers. Features such as wallet management, commission configuration, retailer activation, transaction reports, user permissions, and centralized monitoring help simplify daily operations. Additional integrations such as Micro ATM, Domestic Money Transfer (DMT), BBPS, Aadhaar Pay, and other digital financial services can further expand the Aeps platform business capabilities, subject to the required service integrations and eligibility.
With Aeps India, fintech startups, Aeps software companies, payment businesses, and entrepreneurs can explore customizable AEPS technology solutions for launching or expanding their digital financial services business. Whether you need an AEPS API for an existing application, a complete white label AEPS platform with your own branding, or a B2B AEPS software system with retailer and distributor management, selecting the Aeps india requires evaluating its integration capabilities, security practices, scalability, transaction management, and ongoing technical support.
In this guide, you will learn how to identify the AEPS Best Company, what features to compare before selecting an AEPS provider, how AEPS API integration works, which biometric devices are required, what services an AEPS platform can support, and how to choose the right AEPS software for your business. The goal is to help you make an informed decision and understand how Aeps India can support your AEPS technology and business requirements.
What is an AEPS Company?
An AEPS (Aadhaar Enabled Payment System) company is a financial technology or service provider that enables local retail shops, kirana stores, and individual agents to offer basic, interoperable banking services to customers using only their Aadhaar number and biometric authentication (such as a fingerprint or iris scan).
How Does AEPS Company Work
An Aadhaar Enabled Payment System (AePS) company works as an intermediary platform that connects local retail shops, agents, and Customer Service Points (CSPs) to the national banking network.
How an AePS Company Works
Customer Request at Retail Outlet:
- A customer visits a local merchant or agent outlet (like a kirana store or CSC) to perform a banking transaction.
- The customer provides their Aadhaar number, selects their bank name, and specifies the transaction type (e.g., cash withdrawal, balance inquiry, mini statement).
Biometric Authentication:
- The customer places their finger on a certified Aeps biometric fingerprint scanner (RD device) connected to the agent’s smartphone or computer.
- The fingerprint data is encrypted and sent securely to the Unique Identification Authority of India (UIDAI) for identity verification.
Core Banking Processing via NPCI:
- Once UIDAI verifies the identity, the request routes through the National Payments Corporation of India (NPCI) switch.
- NPCI connects directly to the customer’s linked bank account to check funds or debit/credit the required amount.
Real-Time Settlement & Cash Handover:
- The bank approves or declines the transaction in real time.
- If approved, the agent hands over the physical cash to the customer (in case of a withdrawal), and an SMS receipt is generated.
- The agent’s digital wallet or bank account is credited with the transaction amount plus a small retailer commission (typically ranging from ₹1.50 to ₹9.00 depending on the transaction size).
What Makes an AEPS Company the Best?
An (AePS) Aadhaar Enabled Payment System company is considered the best when it combines high security, strong uptime reliability, fast transaction speeds, and a transparent commission structure.
Key Qualities of a Top AePS Company
- Strict Security & Compliance: Adheres strictly to guidelines set by the Reserve Bank of India (RBI), the Unique Identification Authority of India (UIDAI), and the National Payments Corporation of India (NPCI). This includes strong data encryption, secure biometric (fingerprint/iris) authentication, and protection against unauthorized access.
- High Reliability & Uptime: Features a stable infrastructure with minimal downtime, ensuring that high volumes of daily cash withdrawals, balance inquiries, and mini-statements go through without sudden service dropouts.
- Fast Transaction Speed & Success Rates: Processes biometric-authenticated requests rapidly to avoid long lines or failed deductions at retail touchpoints.
- Transparent Commissions & Pricing: Aeps india offers clear, competitive commission structures for agents and merchants with no hidden fees or delayed payouts.
- User-Friendly Dashboard & Technology: Provides an intuitive Aeps app or Aeps portal with real-time transaction tracking, easy paperless onboarding, and multi-bank integration.
- Responsive Customer Support: Delivers accessible, fast grievance redressal and support channels (phone, email, or chat) to resolve failed transactions or biometric mismatches immediately.
- Expanded Service Ecosystem: Goes beyond basic cash-in/cash-out by bundling AePS with Micro-ATMs, Domestic Money Transfers (DMT), bill payments, and mini-statements to maximize daily earnings for shop owners.
AEPS Services: Cash Withdrawal, Balance Enquiry and Mini Statement
The Aadhaar Enabled Payment System (AePS) developed by the National Payments Corporation of India (NPCI) allows bank customers to perform interbank and intrabank financial transactions using their Aadhaar number and biometric authentication at a Aeps india website.
Core AePS Services
- Cash Withdrawal: Withdraw cash from an Aadhaar-linked bank account through an authorized Aeps india without needing a debit card or ATM PIN.
- Balance Enquiry: Check the real-time available balance of a mapped bank account via fingerprint or biometric scan.
- Mini Statement: View a short summary of recent account transactions (typically the last 5 to 10 entries).
- Other Supported Services: Cash deposits, Aadhaar-to-Aadhaar fund transfers, and Aadhaar Pay.
Key Features to Look for in the Best AEPS Company
The best Aadhaar Enabled Payment System (AePS) company provides a reliable, secure, and feature rich Aeps platform that turns local retail shops and service points into micro-banking hubs.
Core Banking & Financial Services
- Interoperable Transactions: Support for Aeps cash withdrawal, Aeps cash deposit, Aeps balance inquiries, Aeps mini statement and fund transfers across multiple participating banks.
- Cardless & PIN-Free Access: Operates strictly using a 12-digit Aadhaar number coupled with biometric authentication (fingerprint or iris scan) without physical debit cards or ATM PINs.
- Extended Services: Integration of complementary financial tools like Domestic Money Transfer (DMT), Micro ATMs, QR ATMs, and utility/insurance bill collections.
Technology & Security
- High Transaction Success Rates & Uptime: Reliable backend Aeps API infrastructure with minimal downtime for real-time processing.
- UIDAI-Compliant Security: Strict data encryption, biometric verification, and multi-bank integration ensuring safety against fraud.
- Developer & White-Label Support: Open, flexible Aeps service API, sandbox testing environments, and white label Aeps options for custom fintech integration.
Merchant & Business Experience
- Fast Paperless Onboarding: Quick digital KYC and merchant registration processes.
- Real-Time Dashboards & Reporting: Clear tracking of daily transactions, wallet balances, and commission structures.
- Transparent Payout Settlements: Flexible settlement cycles and competitive, clear commission structures for agents and retailers.
Best AEPS Company for Aeps API Integration
Partnering with a reliable AEPS (Aadhaar Enabled Payment System) company for best Aeps API integration is crucial because it directly impacts transaction reliability, legal compliance, and customer trust.
Key Reasons Why the Right AEPS Company Matters
- High Transaction Success Rates: Aeps india ensures smooth routing through NPCI and banking switches, reducing transaction drops and failed biometric authentication.
- Security & Compliance: AEPS involves sensitive Aadhaar data and biometric scans. Aeps india builds UIDAI-compliant encrypted pipelines to prevent fraud and data leaks.
- Real-Time Settlement & Payouts: Fast settlement cycles ensure that retailer wallets and business ledgers are credited instantly without cash-flow blockages.
- Developer-Friendly Tools & Sandbox: Access to clean documentation, live test sandboxes, and reliable Aeps API endpoints drastically cuts down integration time.
- Retailer & Commission Management: Built-in Aeps admin panels let you manage multi-tier distributors, automate commission structures, and track real-time reports.
- Reliable Technical Support: 24/7 dedicated assistance ensures quick resolution during server downtimes or biometric device sync errors.
Best AEPS Company for Retailers and Distributors
An AEPS (Aadhaar Enabled Payment System) company is important because it turns local grocery shops, medical stores, and general merchants into trusted neighbourhood banking points.
For retailers and distributors, partnering with or building an AEPS network unlocks major operational and financial benefits:
Why AEPS is Important for Retailers (Shop Owners)
- Extra Commission Income: Retailers earn a direct commission (typically ranging from ₹2 to ₹17+) on every cash withdrawal, balance enquiry, or mini statement processed through their terminal.
- Increased Customer Footfall: Acting as a mini-ATM draws more people into the shop who might not have visited otherwise.
- High-Value Cross-Selling: Customers who come in to withdraw cash or check a balance frequently spend that money right away on everyday items like groceries, snacks, recharges, or medicines.
- Low Startup Overhead: Retailers do not need to invest in heavy infrastructure they simply use their existing smartphone or computer, a small biometric Aeps fingerprint scanner, and an internet connection.
- No Cards or Passwords Needed: Transactions are processed securely using Aadhaar numbers and fingerprint/biometric authentication, removing the need for debit cards or PINs.
- Support for Government Schemes: Retailers can help local residents receive direct benefit transfers (DBT), pensions, and MGNREGA wage payouts.
Why AEPS is Important for Distributors (B2B Partners)
- Scalable Business Network: Distributors can build and manage a multi-tiered network by Aeps onboarding hundreds of local retailers under them.
- Passive/Override Commission: Distributors earn a share of the commission or override income on every transaction processed by the retailers in their downline chain.
- Foundation for Multi-Service Fintech: An b2b AEPS platform acts as an entry point that allows distributors to cross-offer other digital financial services like:
- Domestic Money Transfer (DMT)
- Bharat Bill Payment System (BBPS)
- Mobile and DTH Recharges
- Cash Payouts and Micro-Insurance
- Instant Settlement Support: Aeps india offer near-instant (T+0 or T+1) settlement cycles, helping distributors maintain smooth cash flow for their retail network.
AEPS Commission Structure and Retailer Earning Potential
The Aadhaar Enabled Payment System (AEPS) allows local kirana stores, pharmacies, and small service centers to act as micro-banking outlets. Retailers earn a transaction-based commission for cash withdrawals, balance inquiries, mini-statements, and related digital Aeps services.
AEPS Cash Withdrawal Commission Structure
Aeps Commission are typically tiered or slab-based, meaning higher withdrawal amounts yield higher payouts per transaction.
| Transaction Slab (Cash Withdrawal) | Typical Retailer Commission Range |
|---|---|
| ₹100 – ₹500 | ₹1.50 – ₹3.00 |
| ₹501 – ₹1,000 | ₹3.00 – ₹5.00 |
| ₹1,001 – ₹2,500 | ₹5.00 – ₹7.50 |
| ₹2,500 – ₹3,000 | ₹7.00 – ₹9.00 |
| ₹3,001 – ₹10,000 (Higher Slabs) | ₹9.00 – ₹17.00+ (depending on the scheme) |
- Balance Inquiry & Mini-Statements: Usually offer smaller flat payouts (roughly ₹1 to ₹5 for inquiries and ₹2 to ₹7 for mini-statements), or act as zero-margin footfall drivers.
- Aadhaar Pay: Capped up to ₹50,000 per day. While Aeps commission may be 0%, retailers are legally permitted to charge a merchant fee of up to 1% directly from the customer.
Retailer Earning Potential
A retailer’s monthly income depends heavily on daily footfall, local demand, transaction size mix, and the chosen AEPS India.
- Average / Moderate Outlets: Retailers processing 30 to 50 mixed transactions a day generally earn ₹10,000 to ₹30,000 per month in pure commission income.
- High-Volume / API-Integrated Outlets: Busy rural or semi-urban hub stores handling heavy daily cash-out volumes can scale earnings to ₹45,000 to ₹1,35,000+ per month.
- Indirect Cross-Selling Value: The hidden earning potential often surpasses direct commission. Customers who visit a local shop for an AEPS cash withdrawal frequently spend a portion of that cash right in the same store on groceries, snacks, or recharges.
- Multi-Service Boost: Combining AEPS with DMT (Domestic Money Transfer), BBPS (Bill Payments), mobile recharges, and Micro-ATMs significantly compounds daily earnings.
AEPS Wallet Management
An AEPS (Aadhaar Enabled Payment System) Wallet is a digital ledger used by merchants, retailers, and Business Correspondents (BCs) to manage the funds, cash flows, and commissions generated from Aadhaar-based banking transactions.
Key Aspects of AEPS Wallet Management
- Liquidity Control: Automates the balance between physical cash at the retail counter and digital wallet funds so agents do not run out of cash for customer withdrawals.
- Commission Tracking: Real-time calculation and crediting of merchant/agent commissions for every cash withdrawal, balance inquiry, mini statement, or fund transfer processed.
- Settlement & Payouts: Moving accumulated wallet balances to linked bank accounts via Immediate Payment Service (IMPS), National Electronic Funds Transfer (NEFT), or Real-Time Gross Settlement (RTGS).
- Audit Trails & Reconciliation: Generating Management Information System (MIS) reports to track daily transactions, failed debits, chargebacks, and cash-in-hand reconciliations.
- Security & Limits: Role-based access controls for Aeps admin, distributor, and retailer panels, alongside two-factor or biometric authentication protocols.
AEPS Transaction Success Rate, Server Stability and Settlement
Aadhaar Enabled Payment System (AePS) performance relies on three core pillars: transaction success rates, server stability (uptime and routing), and settlement cycles managed via the National Payments Corporation of India (NPCI).
1. Transaction Success Rate
- Average Industry Rate: Top-tier B2B and white label Aeps platforms target a success rate of 98% to 99%+ using multi-bank routing. However, historical and field studies indicate that average network-wide success can fluctuate, with failure rates historically hovering around 30%–34% during peak stress or localized connectivity/biometric mismatches.
- Common Failure Reasons:
- Biometric authentication failures (fingerprint/iris mismatch or dirty/worn scanner surfaces).
- Unlinked Aadhaar with the target bank account.
- Insufficient customer account balance.
- Issuer/Acquirer bank server timeouts or banking network drops.
- Transaction Cap: NPCI caps a single AePS financial cash withdrawal transaction at a maximum of ₹10,000.
2. Server Stability & Infrastructure
- Uptime Standards: Quality AePS switches and Aeps india aim for 98%–99% uptime.
- Multi-Bank Routing: To counter single-bank or regional server outages, reliable B2B Aeps platforms use 15+ multi-bank routing layers to dynamically switch traffic if a specific issuing or acquiring bank gateway is unresponsive.
- Official Data Tracking: You can monitor daily and monthly system metrics, volume, and member bank uptimes directly through the NPCI AePS Product Statistics page.
3. Settlement Process
Settlement Timelines (T+0 / T+1):
- Modern B2B/BC (Business Correspondent) frameworks typically offer instant or real-time settlements (T+0) into the agent’s main wallet or designated account to maintain daily cash flow.
- Standard interbank and institutional clearing cycles follow regulatory guidelines (such as T+1 or standard NPCI net settlement cycles).
- Failed Transaction Reversals: If an account is debited but cash is not dispensed due to a glitch, automated reversal or dispute management protocols apply. RBI guidelines mandate timely reversals and liability/penalty rules for delayed failed-transaction refunds. You can review the full operational framework on the NPCI Transactions & Settlement Lifecycle portal.
AEPS Retailer ID, Distributor Registration and KYC Process
An AEPS Retailer ID and Distributor registration allows you to offer Aadhaar-authenticated banking services such as cash withdrawals, balance inquiries, and mini statements through an authorized fintech or Business Correspondent (BC) network.
Eligibility Requirements
- Age: Minimum 18 years old.
- Documents: Valid Aadhaar Card, PAN Card, and a bank account linked with your mobile number.
- Business Setup: A physical shop, service center, or digital storefront with a smartphone or computer and a stable internet connection.
- Biometric Device: STQC-certified fingerprint, iris, or face scanner (e.g.Mantra) compatible with the Aeps app or best Aeps portal.
Step-by-Step Registration & KYC Process
1. Choose an Aeps india
- Select a Aeps india offers trusted Aeps portal credentials for Retailers and Distributors.
2. Submit Application & Basic Details
- Fill out the online or offline registration form on the Aadhaar Enabled Payment System portal with your name, mobile number, email, and business address.
- For a Distributor ID, you may also outline your target network or sub-merchant onboarding plan.
3. Complete e-KYC Verification
- Submit scanned or digital copies of your PAN Card and Aadhaar Card.
- Complete biometric e-KYC authentication using your fingerprint/iris scanner to verify your identity against UIDAI databases.
- Background and blacklist checks are run via your PAN/Aadhaar.
4. Document & Shop Verification
- Upload proof of address (such as an electricity bill, rent agreement, or shop registration) and a passport-sized photograph.
- Some providers or partner banks conduct a physical or remote verification of your retail shop.
5. Agreement & Training
- Sign the merchant/distributor agreement detailing roles, compliance, and commission structures.
- Complete mandatory training provided by the top Aeps platform on operating the Aadhaar Enabled Payment System software, handling biometric hardware, and managing settlements.
6. Activation
- Once verification clears, your login credentials (Retailer ID or Distributor ID) are activated, allowing you to start transactions or Aeps onboard sub-merchants.
AEPS Software, Mobile App, Portal and API Facilities
The Aadhaar Enabled Payment System (AePS) is a bank-led, NPCI-developed model that enables interoperable online financial transactions using an Aadhaar number and biometric authentication through Business Correspondents (BCs).
Software, Mobile App, Portal & API Components
AEPS Software & White Label Platforms:
- Turnkey white label Aeps admin panel allow to manage multi-tiered hierarchies (super distributors, distributors, retailers).
- Features include automated commission setups, real-time bank settlements, transaction logs, and ledger management.
Mobile Apps (Android / iOS):
- Designed for retailers and field agents to turn smartphones or tablets into mini-banks.
- Integrated with OTG-supported biometric Aeps fingerprint/Aeps iris scanners (UIDAI-compliant) for instant customer verification.
Web Portals:
- Centralized dashboards for operators to track live transaction status, generate daily/monthly settlement reports, and manage wallet loads/payouts.
AEPS APIs:
- Developer-friendly RESTful Aeps API that connect third-party fintech applications directly to the National Payments Corporation of India (NPCI) rails.
- Typically feature sandbox testing environments, KYC/UIDAI compliance hooks, and high-uptime routing (99.9%).
Aeps Biometric Device Compatibility and Transaction Security
An Aadhaar Enabled Payment System (AePS) transaction requires a UIDAI-certified Registered Device (RD) that matches specific hardware compatibility and security standards set by the Unique Identification Authority of India (UIDAI), the National Payments Corporation of India (NPCI), and the Reserve Bank of India (RBI).
Biometric Device Compatibility Requirements
- L1 vs. L0 Certification: UIDAI mandates the use of L1 (Level 1) biometric devices where cryptographic keys and data encryption are managed directly inside the device’s secure hardware. Older L0 devices (which processed keys in software on the host phone or PC) are being phased out.
- RD Service Activation: Every device must have an active Registered Device (RD) Service running, which encrypts biometric data (fingerprint or iris) inside the scanner before it ever reaches the host smartphone, tablet, or computer.
- Supported Brands & Models: Devices must be certified and explicitly integrated with the banking or fintech app being used. Commonly supported brands include:
- Mantra (e.g., Mantra MFS110 L1)
- Platform & Connectivity: Devices must connect seamlessly typically via USB or USB OTG (Micro-USB or Type-C) to Android smartphones, POS terminals, or Windows systems operated by Business Correspondents (BCs).
Transaction Security Architecture
- End-to-End Encryption: Raw biometric prints are never exposed to or stored on the merchant’s application, phone, or local computer.
- Hardware-Level Protection: L1 Aeps devices isolate cryptographic operations inside a tamper-resistant secure element inside the scanner.
- Interoperable Authentication: The encrypted packet goes straight to UIDAI’s central servers for validation, after which an authenticated clearance is passed to the NPCI and the user’s linked bank account across 100+ participating banks.
- Card-Free & PIN-Free Safety: Transactions rely exclusively on the Aadhaar number and live biometric capture, eliminating physical card skimming or static PIN thefts, though operators must maintain active RD service registrations and clean optical sensors to prevent transaction drops.
AEPS Company Charges, Wallet Requirements and Other Costs
AePS costs, wallet requirements, and Aeps setup fees vary depending on whether you are setting up a White Label Aeps API/Direct API platform or joining as a local Business Correspondent (BC) agent.
1. Company & API Setup Costs
- White-Label API: Ranges from ₹15,000 to ₹30,000 ( White Label Aeps API setup fees up to ₹35,000–₹50,000), allowing startups to use a parent banking/AePS license with customized branding.
- Direct Bank API: Ranges from ₹2,500,000 to ₹4,500,000+, designed for established fintechs integrating directly with partner banks (such as ICICI or Yes Bank).
- Per-Transaction Routing / Slabs: Cash withdrawals typically cost Aeps platforms around ₹10 to ₹20 in bank or NPCI routing fees, while agents/platforms earn Aeps commission slabs ranging from ₹2 to ₹17+ per transaction.
2. Wallet & Working Capital Requirements
- Working Capital Float: You must maintain a liquid cash or digital float in your AePS wallet because you hand out physical cash to customers at your touchpoint and get reimbursed through the backend settlement cycle.
- Wallet & Issuer Transaction Fees:
- Cash Withdrawal & Balance Enquiry: Often free or includes 1 free monthly transaction on other-bank touchpoints; subsequent transactions may incur fees around ₹15 + GST.
- Mini Statement: Typically offers 5 free transactions per month, with charges around ₹5 + GST thereafter.
- NPCI Settlement Fee: Flat ₹0.25 per transaction (where applicable).
3. Agent & Touchpoint Requirements / Other Costs
- Hardware & Devices: Requires an STQC/L1 Aeps certified biometric fingerprint scanner (₹2,000–₹4,000) paired with an Android smartphone, tablet, or PC and internet access.
- KYC & Documentation: Standard requirements include an Aadhaar-linked mobile number, PAN card, bank account, and local business proof (such as a Shop Act certificate or utility bill), while UIDAI authentication remains government-subsidized and free.
AEPS Reconciliation
Aadhaar Enabled Payment System (AePS) reconciliation is the process of matching transaction logs, micro-ATM/terminal records, and NPCI switch data against bank statements and settlement files to ensure every debit, credit, or failed attempt is accurately accounted for.
Core Objectives of AePS Reconciliation
- Status Matching: Verifying whether transactions marked as successful, failed, or pending at the touchpoint (micro-ATM, kiosk, or mobile device) match the actual settlement logs at the backend bank.
- Dispute and Chargeback Resolution: Identifying mismatches, duplicate debits, or stuck funds, and processing chargebacks or refunds for failed transactions where a customer’s account was debited.
- Settlement Verification: Ensuring Business Correspondents (BCs) and AePS Touchpoint Operators (ATOs) receive correct liquidity and commission payouts.
Key Steps in the Reconciliation Workflow
- Data Aggregation: Downloading transaction log files from the AePS switch, aggregator portal, micro ATM terminals, and core banking / settlement bank statements.
- Automated / Manual Matching: Cross-referencing unique transaction reference numbers, Aadhaar/IIN details, timestamps, and amounts.
- Categorizing Discrepancies:
- Matched: Successful debits and credits align across all touchpoints.
- Pending / Stuck: Amount deducted from the customer but response timed out; auto-reversal or manual settlement required.
- Failed / False Positives: Transaction failed at the switch, requiring verification that no funds left the customer’s account.
- Adjustment and Payout Release: Settling merchant/BC commissions, clearing disputed float, and closing out daily or cycle-based ledger differences.
Best AEPS Company for White Label Aeps Software
Partnering with the Aeps india is an right AEPS company for a white-label AEPS software is crucial because it allows you to launch your own branded digital banking and micro-banking business without building complex banking infrastructure from scratch.
Why Choosing the Best White-Label AEPS Company Matters
- Brand Identity & Control: A white label Aeps solution lets you operate under your own company name, logo, domain name, and custom color scheme, giving you full ownership of your customer and retailer relationships.
- Avoids Complex Regulatory & Tech Hurdles: Building direct integrations with the National Payments Corporation of India (NPCI), Unique Identification Authority of India (UIDAI), and banking partners requires massive capital, time, and compliance approvals. Aeps india handles the heavy backend infrastructure.
- Hierarchical Network Management: A reliable white label Aeps platform includes a centralized Aeps admin panel to manage multi-tiered networks such as Master White Labels, Super Distributors, Distributors, and Retailers/CSPs along with commission configurations and automated payout/settlement cycles.
- Biometric & Device Integration: Seamless support for STQC-certified Aeps biometric scanning devices (like Mantra, Morpho, Startek, and Cogent) is essential for smooth Aadhaar authentication during cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay software.
- Security & Compliance: Financial transactions require high-grade security, such as 256-bit encryption, fraud prevention controls, and RBI/NPCI-compliant data protection.
- Uptime & Transaction Success Rates: High transaction uptime (99.9% or multi-bank routing) ensures that rural and semi-urban customers facing limited banking access experience fast, reliable service rather than failed debit scans.
Best AEPS Company for Aeps Software
Choosing the Aeps india one of the right AEPS company and Aeps service software is crucial for any fintech startup, B2B provider, distributor, or local retail network. Because AEPS handles core banking operations like cash withdrawals, balance inquiries, and mini statements using biometric authentication, the quality of the underlying technology directly dictates your business’s success and legality.
Why a Best AEPS Company and Software Matter
- High Transaction Success & Uptime: Top tier AEPS platform maintain stable direct-bank or Aeps mini statement API, minimizing server-down issues and failed fingerprint/iris matching. This builds trust with your daily walk-in customers or retail network.
- Security and Compliance: AEPS transactions involve sensitive biometric data and direct bank accounts. Aeps india ensures strict UIDAI compliance, multi-factor authentication (2FA), and robust end-to-end encryption to prevent fraud.
- Centralized Network & Hierarchy Management: Good B2B AEPS software lets you run a full multi-tier network (Admin, Super Distributor, Distributor, and Retailer IDs) from a single Aeps dashboard. You can easily monitor commission structures, wallet balances, and agent performance.
- Fast Settlement Cycles: Instant or automated payout and settlement systems ensure that retail agents or business owners don’t get their working capital stuck in transit.
- Scalability and White-Label Options: If you want to build your own brand, a Aeps india offers white label Aeps app or open-Aeps API solutions that scale as your agent network expands across regions.
Why Important Best AEPS Android App
A reliable AePS Android app is important because it turns local retail shops into micro-banking touchpoints, driving financial inclusion and creating new business value.
Key Reasons Why a Best AePS Android App is Important
- Cardless & PIN-Free Banking: Customers only need their Aadhaar number and biometric verification (fingerprint or iris scan) to complete transactions, removing the need for debit cards, PINs, or smartphones.
- Rural & Underserved Access: It bridges the gap in areas with limited bank branches or ATMs, allowing citizens in remote villages to withdraw cash or check balances locally.
- New Revenue Streams for Retailers: Local shop owners and agents earn commissions on every transaction (cash withdrawals, balance inquiries, mini statements), increasing footfall and customer loyalty.
- Government Benefit Disbursements: It facilitates direct access to social security pensions, NREGA wages, and other government-backed financial distributions using Aadhaar authentication.
- Value-Added Services: Beyond basic banking, top apps integrate utility bill payments (BBPS), mobile recharges, Micro ATM device (MATM), and domestic money transfers, expanding a retailer’s utility.
- Security & Transparency: Biometric authentication and UIDAI-backed verification minimize the risk of bank fraud and unauthorized transactions.
Security Features to Look For Best AEPS Company
Aeps india one of the best Aadhaar Enabled Payment System (AePS) company or Aeps software provider, security is the most critical pillar. Aeps india must protect sensitive biometric and financial data against unauthorized access, data leaks, and fraud.
Core Security Features to Look For
- NPCI Certification & Regulatory Compliance: Aeps india is an authorized and certified partner of the multi bank and complies with Reserve Bank of India (RBI) guidelines.
- End-to-End (E2E) Data Encryption: All transaction data and communication between the merchant/agent device, the Aeps india server, and banking nodes must be strongly encrypted (such as SSL/TLS protocols) during both transmission and storage.
- No Storage of Biometric Data: A secure AePS system must never store customer fingerprints, iris scans, or raw biometric data locally. It should act strictly as a pass-through channel where verification happens directly on UIDAI (Unique Identification Authority of India) servers.
- Liveness Detection & Anti-Cloning Measures: Advanced Aeps biometric scanners and top Aeps software integration should feature anti-spoofing and liveness detection to prevent fraud attempts involving cloned or fake rubber fingerprints.
- Role-Based Access Control (RBAC): Backend Aeps portals and Aeps administrator panels should enforce strict role-based permissions, multi-factor authentication (MFA) for agents/staff, and secure session management.
- Comprehensive Audit Trails & Transaction Logging: The branded Aeps platform should maintain immutable, real-time logs of every transaction, AePS Balance Enquiry API call, failed attempt, and administrative action for security auditing and tracking.
- Secure API Communication: If you are integrating AePS Cash Withdrawal API into your own Aeps commission platform, look for tokenized credentials, IP whitelisting, rate limiting, and strict input validation to block injection or relay attacks.
AEPS Company vs AEPS API Provider
An AEPS Company is a full-stack business that offers a complete end-to-end portal, mobile Aeps app, and business structure for agents or merchants, Aeps india is an AEPS API Provider is a technical infrastructure company that supply Aeps software code (API) allowing third-party developers to plug AePS banking features into their own custom Aeps apps.
Key Differences at a Glance
| Feature | AEPS Company (Platform) | AEPS API Provider |
|---|---|---|
| Primary Focus | Delivers a ready-to-use business ecosystem, panels, and wallets. | Delivers backend connectivity and raw code to talk to the banking network. |
| Target Audience | Retailers, distributors, small shop owners, and agents. | Software developers, fintech startups, and enterprises building custom platforms. |
| What You Get | • Ready-made web/mobile portal • Retailer & distributor hierarchy • Commission management • Built-in wallet & settlement reports | • Technical documentation & sandbox environment • Direct Aeps API endpoints for cash withdrawal/balance inquiry • Multi-bank/NPCI routing |
| Customization | Low to moderate (often white-labeled with your brand name, but the workflow is pre-built). | High (you design the UI, UX, and entire user journey yourself). |
| Technical Load | Low (the company manages servers, compliance, and bank uptime). | High (your team must handle app development, security compliance, and error handling). |
Detailed Breakdown
1. What is an AEPS Company?
Aeps india is an AEPS company provides a turnkey business solution. If you want to run a network of micro-ATM or Aadhaar-banking agents without writing software, you partner with an AEPS india.
- What they provide: They give you access to a ready admin panel, retailer logins, commission distribution rules, wallet balance management, and reporting tools.
- Example use case: A regional distributor or micro-finance network that wants to onboard local kirana stores to process cash withdrawals and balance inquiries immediately.
2. What is an AEPS API Provider?
Aeps india is an best AEPS API provider acts as a bridge or gateway to the National Payments Corporation of India (NPCI) and underlying banking rails. They do not necessarily give you a ready-made agent portal; instead, they give you an fast Aeps API (Application Programming Interface).
- What they provide: Technical documentation, SDKs, sandbox testing environments, fingerprint device integration support (like Mantra or Morpho), and uptime-managed transaction routing.
- Example use case: A fintech startup building its own proprietary mobile super-app that wants to embed Aadhaar cash-out or mini-statement features natively inside their own code.
How to Choose the Right AEPS Company for Your Business?
Aeps india one of the right Aadhaar Enabled Payment System (AePS) company for your business involves evaluating several core operational, financial, and regulatory factors to ensure smooth transactions and customer trust.
Key Factors to Consider
Security and Compliance
- Aeps india strictly complies with guidelines from the National Payments Corporation of India (NPCI), the Unique Identification Authority of India (UIDAI), and the Reserve Bank of India (RBI).
- Look for end-to-end data encryption, secure biometric authentication, and strong fraud prevention mechanisms.
Transaction Success Rate and Uptime
- High uptime (ideally 99% or higher) and low failure rates prevent customer drop-offs at your counter.
- Fast processing speeds ensure quick fingerprint scans and immediate response times.
Commission Structure and Transparent Pricing
- Compare per-transaction earnings, agent/retailer commissions, and any hidden platform fees.
- Look for clear, predictable fee structures without surprise maintenance or reliable Aeps software charges.
Settlement Speed and Payouts
- Fast or real-time settlement into your bank account or wallet is critical for managing daily store cash flow.
- Check for transparent reporting and transaction tracking logs.
Supported Banking Services
- Verify which Aeps services are included beyond basic cash withdrawals, such as balance inquiries, mini statements, Aadhaar-to-Aadhaar fund transfers, or cash deposits.
- Many providers also bundle value-added services like Domestic Money Transfer (DMT), Micro-ATMs, bill payments, and mobile recharges.
Hardware and Software Usability
- Check whether the Aeps india supports UIDAI-certified Aeps biometric fingerprint or Aeps iris scanner device (Registered Devices / RD devices).
- The retailer Aeps portal or Aeps mobile app should feature intuitive navigation, clear transaction statuses, and easy history reporting.
Integration and Technical Support
- For live Aeps API or white-label users, look for clean documentation, sandbox testing environments, and Aeps developer support.
- For retail shop owners, responsive customer support via phone, chat, or email is essential to quickly resolve failed or stuck transactions.
Why Choose AEPS India for AEPS Best Company
Aeps india one the AEPS Best Company is essential for retailers, shop owners, and fintech entrepreneurs looking to offer reliable, biometric-based banking services like cash withdrawals, balance inquiries, and mini-statements.
Key Reasons to Choose a Top AePS Provider
- High Transaction Success Rates: Aeps india ensure uptime and reliability (aiming for 98%+ success rates) to minimize failed transactions at your shop.
- Instant Settlements: Aeps india offer fast or real-time daily payouts and settlement cycles so your working capital isn’t locked up.
- Regulatory Compliance: Aeps india maintains strict adherence to NPCI and RBI guidelines for data protection, encryption, and secure 2FA authentication.
- Attractive Commission Structure: Aeps india offer transparent, competitive commission margins that turn the agency model into a profitable revenue stream.
- Robust Support & Infrastructure: Dependable technical support, multi-bank connectivity, and smooth integration with biometric RD devices (fingerprint/iris scanners) keep your counter running without disruptions.
Questions to Ask an AEPS Company
When evaluating Aeps india is an Aadhaar Enabled Payment System service provider, asking targeted questions ensures you select a partner that is compliant with NPCI (National Payments Corporation of India) and RBI guidelines, Aeps india offers reliable uptime, and provides transparent payouts.
1. Compliance and Licensing
- NPCI and RBI Authorization: Are you a direct NPCI-certified partner, a Business Correspondent (BC) of a registered bank, or a third-party aggregator?
- Sponsor Bank Details: Which sponsor bank powers your AEPS transactions, and is there a backup bank if the primary server goes down?
- Agent Onboarding and KYC: What is the exact KYC verification process for onboarding merchants, and how long does activation take?
- Audit and Data Security: How do you comply with UIDAI and RBI data storage guidelines regarding customer biometric and Aadhaar data?
2. Pricing, Commissions, and Settlements
- Commission Structure: What is the exact slab-wise commission payout for cash withdrawals, balance inquiries, mini statements, and Aadhaar Pay?
- Setup and Hidden Fees: Are there any one-time onboarding fees, annual maintenance charges (AMC), or minimum transaction quotas?
- Settlement Cycle: Do you offer instant T+0 settlement to my bank account, and what are the charges for NEFT, IMPS, or RTGS payouts?
- TDS and GST Deductions: How are TDS (under Section 194N or 194O) and GST calculated and deducted from my commissions?
3. Technical Reliability and Integration
- Transaction Success Rate: What is your current average transaction success rate, and how do you handle technical declines?
- Biometric Device Compatibility: Which RD (Registered Device) L1 biometric scanners (such as Mantra, Morpho, or Startek) are supported on your portal or app?
- API Documentation (If applicable): If I am integrating AEPS into my own platform, how comprehensive is your API documentation, and do you provide a sandbox environment for testing?
- Multi-Service Bundling: Can I access other services like Domestic Money Transfer (DMT), Micro ATM, BBPS, or PAN card services using the same wallet balance?
4. Dispute Resolution and Support
- Failed Transaction Turnaround Time (TAT): If a customer’s account is debited during a failed transaction, what is the exact TAT for an automatic refund or chargeback resolution?
- Customer Support Availability: Is dedicated technical support available during weekends and bank holidays when transaction volumes peak?
- Fraud and Chargeback Liability: What is your policy if a fraudulent transaction or disputed chargeback occurs at a merchant point, and how do you assist in resolving it?
Important AEPS Compliance Note
Aadhaar Enabled Payment System (AePS) compliance is strictly governed by the Reserve Bank of India (RBI), the National Payments Corporation of India (NPCI), and the Unique Identification Authority of India (UIDAI) to prevent identity theft and payment fraud. Acquiring banks, Business Correspondents (BCs), and AePS Touchpoint Operators (ATOs) must adhere to the mandatory regulatory framework.
Operator Onboarding & Due Diligence
- Mandatory Operator KYC. Acquiring banks must complete full customer-grade KYC and background due diligence before onboarding any AePS Touchpoint Operator.
- Single Bank Mapping. Each operator is restricted to mapping with a single acquiring bank to prevent unauthorized multi-bank routing.
- Inactivity Re-KYC Rule. Any operator ID that remains inactive for three consecutive months must undergo mandatory re-verification before processing new transactions.
Authentication & Transaction Security
- Step-Up Authentication. Under NPCI Circular OC 096, cash withdrawals and Aadhaar Pay transactions exceeding ₹5,000 require two-factor authentication combining biometrics and an Aadhaar-registered mobile OTP. Transactions up to ₹5,000 require biometric verification only.
- Certified Biometric Hardware. Touchpoints must use STQC-certified L1 biometric devices equipped with liveness detection to block spoofed fingerprints. Face authentication is discontinued for AePS cash-outs.
- Transaction Caps. Standard AePS cash withdrawals are subject to a maximum cap of ₹10,000 per transaction, alongside bank-specific daily velocity limits.
Technical, API & Data Protection Controls
- Dedicated API Restrictions. Aeps india must restrict modern AePS API strictly to authorized AePS workflows and integrate Aeps system with Enterprise Fraud Risk Management Systems (EFRMS).
- Real-Time Status Verification. Systems must integrate with UIDAI Aadhaar Status Notification APIs to block transactions linked to deactivated or deceased Aadhaar profiles.
- Aadhaar Masking & Consent. Entities must obtain explicit customer consent prior to authentication and redact or mask Aadhaar numbers in all physical receipts and electronic records.
Conclusion
Choosing the AEPS Best Company in India is an important step for businesses that want to establish a reliable digital banking and Aadhaar-enabled payment service network. The Aeps india should provide more than basic cash withdrawal facilities. Businesses should look for a complete solution that includes secure AEPS Cash Deposit API integrating, biometric device compatibility, cash withdrawal, balance enquiry, mini statement, transaction monitoring, Aeps wallet management, commission configuration, and retailer and distributor management. Proper transaction-status verification, settlement support, reconciliation, and responsive technical assistance are equally important when evaluating an Aeps india.
The best AEPS (Aadhaar Enabled Payment System) company in India depends on your specific use case, such as rural retail networks, fintech APIs, or direct banking infrastructure.
Aeps India offers trusted AEPS software and integration solutions designed to help fintech startups, entrepreneurs, payment businesses, and distributors build and manage their own digital Aeps banking platform. From white label AEPS banking software and reputed Aeps API integration to centralized Aeps admin panel and B2B retailer-distributor management, businesses can explore technology options based on their operational requirements. Additional services such as Micro ATM Software, Domestic Money Transfer (DMT), BBPS Software, and Aadhaar Pay API can also help expand a digital financial services Aeps business platform, subject to the availability of the required integrations and service approvals.
If you are searching for the AEPS Best Company to start a new AEPS business, integrate Aadhaar-enabled banking services, or expand your existing fintech network, Aeps India can be a solution worth exploring. Before making your decision, compare API capabilities, security standards, supported biometric devices, transaction handling, pricing, scalability, and technical support. Choose an AEPS platform that matches your business goals and provides the essential tools to manage daily operations efficiently.
Contact Aeps India to discuss your AEPS software, white-label platform, or Aeps API integration requirements and explore the right technology solution for building and growing your digital banking business.
Frequently Asked Questions About AEPS Best Company
The best AEPS company in India is one that provides reliable Aeps API integration, secure biometric authentication support, transparent transaction management, retailer and distributor panels, commission management, and responsive technical support. Aeps India offers high volume AEPS software, Aeps API integration, and white label Aeps platform solution for businesses looking to establish or expand their digital banking services.
A reliable AEPS company should support essential services such as Aadhaar-based cash withdrawal, balance enquiry, mini statement, and cash deposit where enabled. It should also provide transaction tracking, Online Aeps API connectivity, biometric device compatibility, settlement information, and proper support for failed or pending transactions.
Yes, Aeps India offers AEPS API integration solution for businesses that want to connect Aadhaar-enabled banking services with their existing websites, mobile applications, or fintech platforms. Integration requirements and supported services depend on the selected solution and applicable banking arrangements.
White Label AEPS Software allows businesses to launch their own brand AEPS platform using their company name, logo, and branding. It can include an admin panel, retailer panel, distributor panel, transaction management, wallet or ledger functionality, and commission configuration, depending on the Aeps software package.
AEPS transactions require compatible Aadhaar-enabled biometric authentication devices supported by the Aeps india integration. Common device brands include Mantra, Morpho, Startek, and Cogent. Device compatibility, STQC certification, RD service requirements, and supported device models should be verified before purchasing.
Aeps india should offer secure API integration, biometric device support, cash withdrawal, balance enquiry, mini statement, transaction reports, wallet management, commission settings, retailer and distributor management, admin controls, and technical assistance. Proper reconciliation and transaction-status handling are also essential.
To start an AEPS business, first determine your business model and select a suitable AEPS API or white-label software solution. Complete the required business and KYC formalities, confirm Aeps india approvals, arrange compatible biometric devices, and configure your admin and retailer panels. Contact Aeps India to discuss the available onboarding and integration requirements.
AEPS API integration connects your software or application with an authorized AEPS service infrastructure. After authentication and the required customer consent, a transaction request is processed through the applicable banking and authentication systems. The platform receives a transaction response and updates its records according to the transaction status.
An AEPS india can provide a centralized platform through which retailers and distributors access supported banking services. Features such as individual accounts, transaction history, commission management, wallet or ledger records, and reporting help businesses manage their distribution network and monitor daily operations.
Aeps India provides AEPS technology solutions for businesses looking for API integration, white-label AEPS software, admin panels, and B2B retailer-distributor management. Businesses can explore suitable solutions based on their branding, integration, transaction management, and operational requirements. Contact Aeps India to discuss your requirements and identify the right AEPS solution for your business.
Best AEPS Provider in India 2026 – Highest Commission, Fast Settlement & Trusted Service
Best AEPS Commission App in India 2026
AePS Advantages and Disadvantages: Complete Guide
About Author

