AEPS Banking Software in India – Secure, Scalable & Complete AEPS Platform
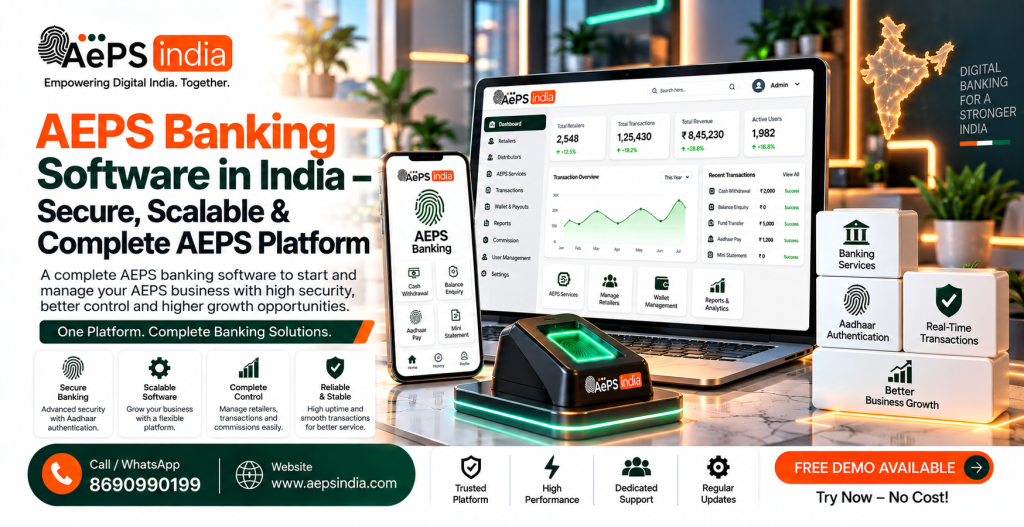
AEPS Banking Software is a digital platform that helps fintech businesses, payment companies, distributors, retailers, and digital service providers manage Aadhaar Enabled Payment System services through a centralized system. It can bring AEPS transactions, retailer management, distributor management, wallets, commissions, reports, and service controls together in one platform.
AePS is a bank-led model that allows customers to access supported banking services through an authorised touchpoint using Aadhaar-based authentication. Depending on the applicable service and banking arrangement, AePS can support services such as cash withdrawal, cash deposit, balance enquiry, mini statement, and other supported transactions.
AEPS (Aadhaar Enabled Payment System) banking software is a digital platform that lets local shops, retailers, and fintech agents turn into mini-bank branches. It uses the customer’s Aadhaar number and fingerprint scan to complete cardless and PIN-less transactions through the NPCI network.
For a business, AEPS Banking Software is more than a simple transaction application. A complete platform can provide an Admin Panel, Retailer Panel, Distributor Panel, wallet management, commission management, transaction history, service activation, reports, settlement information, user management, and role-based access. These features help businesses manage their AEPS network from a single dashboard.
An AEPS banking platform can also support a multi-level distribution structure such as Admin → Master Distributor → Distributor → Retailer. This allows businesses to create their own network, Aeps india, assign services, manage wallet balances, configure applicable commission structures, and monitor transactions according to their operating model.
AEPS API Integration is another important part of the software. The Aeps API connects the Aeps platform with the required AEPS service infrastructure and enables supported transaction requests and responses to move between systems. The exact services, authentication process, device requirements, and transaction workflow depend on the selected Aeps india.
A well-designed AEPS Banking Software Solution should also make transaction management easier. The best Aeps admin can monitor transaction status, review reports, manage users, check wallet activity, control services, and maintain operational records. For larger businesses, scalability and reliable transaction handling become increasingly important as the retailer network and transaction volume grow.
Businesses can also consider White Label AEPS Banking Software when they want to provide AEPS services under their own brand. Depending on the implementation, the best Aeps platform can include branded web portals, mobile Aeps application, retailer and distributor dashboards, customized Aeps commission structures, wallet workflows, and Aeps API integration.
At Aeps India, businesses can explore top AEPS banking software based on their operational requirements, retailer network, required services, integration model, and business structure. The Aeps india can be planned for fintech companies, digital service providers, payment businesses, retailers, distributors, and organizations looking to add supported top AEPS services to their existing best Aeps platform.
It is also important to choose AEPS software based on the actual business requirements rather than only the number of features listed on a website. best Aeps API connectivity, biometric-device compatibility, transaction processing, Aeps wallet and ledger management, Aeps commission controls, reporting, security, scalability, support, and service availability should all be evaluated before implementation.
In this complete guide, we will explain what AEPS Banking Software is, how AEPS banking software works, its key features, AEPS API integration, retailer and distributor management, AEPS Admin Panel, wallet management, commission management, transaction processing, reports, biometric device requirements, white label AEPS software, security considerations, Aeps setup requirements, pricing factors, and how to choose the right AEPS Banking Software for your business.
What Is AEPS Banking Software?
AEPS banking software is a digital platform that allows merchants, retailers, and financial service providers to process cardless and PIN-less banking transactions using a customer’s Aadhaar number and biometric authentication (fingerprint or iris scan). Developed under the framework of the National Payments Corporation of India (NPCI), it turns local shops and micro ATM into accessible banking touchpoints.
AEPS Banking Software Work
Aadhaar Enabled Payment System banking software enables cardless, interoperable micro-banking transactions through an agent or Business Correspondent (BC) using biometric authentication.
How AEPS Software Works
- Data Input: The retailer or agent enters the customer’s 12-digit Aadhaar number and selects the participating bank name.
- Biometric Scan: The customer places their finger on a connected biometric scanner to capture a fingerprint.
- Secure Routing: The top AEPS software sends the encrypted biometric and transaction request through the secure NPCI gateway to UIDAI and the destination bank.
- Real-Time Approval: The bank verifies the details against Aadhaar records and approves or declines the transaction instantly.
AEPS Banking Services Available Through the Software
Aadhaar Enabled Payment System banking software enables cardless, biometric-authenticated banking operations through authorized agents and business correspondents.
Available AEPS Banking Services
- Cash Withdrawal: Allows customers to withdraw money from their bank accounts using biometric verification.
- Balance Inquiry: Provides real-time checking of account balances.
- Mini Statement: Generates a summary of recent account transactions.
- Cash Deposit: Permits depositing cash directly into linked bank accounts (supported by select banks and platforms).
- Fund Transfer: Facilitates Aadhaar-to-Aadhaar or interbank money transfers.
- Aadhaar Pay / BHIM Aadhaar Pay: Enables merchant payments via biometric authentication.
AEPS Banking Software Requirements
An AEPS Banking Software requires a certified STQC Aeps biometric device, an internet-connected smartphone or Windows PC, and an authorized Aeps india.
Hardware Requirements
- Biometric Scanner: An STQC-certified Aeps fingerprint or Aeps iris scanner (such as Mantra) connecting via USB or Bluetooth.
- Computing Device: An Android smartphone/tablet or a Windows PC/laptop running Windows 7 or higher.
- Connectivity: A stable 4G or broadband internet connection for real-time authentication.
Software & Technical Features
- API Integration: Robust backend connectivity to link with banking gateways and NPCI infrastructure.
- Security & Encryption: End-to-end data encryption and AI-powered fraud prevention to safeguard biometric data.
- Dashboard Management: An intuitive user interface to track retailer wallets, transaction logs, commission structures, and reports.
- Compliance Protocols: Adherence to the latest RBI and NPCI guidelines, including risk-based tracking and multi-factor authentication.
Documentation & Setup
- KYC Documents: Valid Proof of Identity (PAN/Aadhaar), Proof of Address, and business registration proof.
- Bank Account: An active Aadhaar-seeded bank account for settlement of daily transactions and commissions.
Who Can Use AEPS Banking Software
Aadhaar Enabled Payment System (AEPS) banking software can be used by bank customers, authorized agents or business correspondents, and fintech businesses or retailers.
1. Bank Customers (End Users)
- Who they are: Any individual holding a bank account in India.
- Requirement: The bank account must be linked to their 12-digit Aadhaar number.
- What they do: Use AEPS at touchpoints for cardless and PIN-less services like cash withdrawals, balance checks, and mini statements using fingerprint or iris scans.
2. Agents and Business Correspondents (BCs)
- Who they are: Local shopkeepers, micro-merchants, and dedicated rural banking agents.
- Requirement: Registration with an authorized Aeps india, paired with a certified biometric scanner.
- What they do: Turn local retail shops into “micro ATM device” to help community members deposit or withdraw cash while earning commission on transactions.
3. Retailers, Distributors, and Fintech Companies
- Who they are: B2B service providers, entrepreneurs, and startup platform owners.
- Requirement: Integration of best white label AEPS software or Fast Aeps API.
- What they do: Manage merchant networks, handle real-time settlements, track user commissions, and offer banking services to underbanked regions without needing a banking license.
Why Use AEPS Banking Software
Aadhaar Enabled Payment System (AEPS) banking software enables secure, cardless, and PIN-less financial transactions using an individual’s Aadhaar number and biometric authentication.
Key Reasons to Use AEPS Banking Software
- Cardless and PIN-Less Convenience: Customers do not need to carry physical debit cards, remember complex ATM PINs, or carry bank passbooks to access their funds.
- Biometric Security: Transactions require a Aeps fingerprint or Aeps iris scan verified through the Unique Identification Authority of India (UIDAI), which drastically reduces the risk of fraud and unauthorized access.
- Promotes Financial Inclusion: It bridges the gap in rural and underbanked regions by turning local retail shops and micro ATM system into mini-bank branches.
- Interoperability: The top Aeps platform supports cross-bank transactions, meaning customers can access accounts from any NPCI-approved bank using a single local agent touchpoint.
- Essential Banking Services: It handles real-time requests for cash withdrawals, cash deposits, balance inquiries, mini-statements, and fund transfers.
- Business Revenue Generation: Retailers and business correspondents earn direct commissions on every successful financial transaction they process for customers.
AEPS Banking Software for Fintech Businesses
An AEPS Software platform enables fintech businesses and local merchants to offer interoperable, Aadhaar-based digital banking services such as cash withdrawals, balance inquiries, and mini-statements using secure Aeps biometric fingerprint authentication.
Core Features of AEPS Banking Software
- Biometric Authentication: Uses fingerprint or Aeps iris scans linked with a customer’s Aadhaar and bank account.
- Essential Banking Services: Facilitates cash withdrawals, balance checks, mini statements, and Aadhaar Pay.
- White-Label Solutions: Allows startups to launch custom-branded web portals and Android Aeps apps without heavy banking infrastructure licensing.
- Real-Time Settlements: Automates commission calculations and instant transaction settlements.
AEPS Retailer and AEPS Distributor Software
An Aeps india enables local shop owners and fintech intermediaries to process cardless, biometric-based banking transactions such as cash withdrawals, balance inquiries, and mini-statements using the Aadhaar Enabled Payment System.
Core Features
- Retailer Platform: Turns local shops into neighborhood mini-banks using a smartphone or computer paired with a biometric fingerprint scanner.
- Distributor & Admin Panel: Provides multi-tier user hierarchy control to onboard retailers, assign member IDs, and track downline volume.
- Automated Commission Engine: Dynamically calculates and splits commission margins for every transaction completed by downline agents.
- Real-Time Settlement: Settles funds and commissions instantly into merchant or distributor wallets.
AEPS Retailer and AEPS Distributor Software
Complete Banking Management Panel • Live System
AEPS Retailer Software
Retailer ID: RET-4521AEPS Distributor Software
Distributor ID: DIST-108- RKRajesh Kumar₹2.4L
- PSPriya Sharma₹1.8L
- AV
AEPS Banking Software Dashboard – What Can You Manage?
An AEPS dashboard allows administrators, distributors, and retailers to control and monitor cardless, biometric-based digital banking operations from a single centralized Aeps b2b platform.
Key Features You Can Manage
- Transaction Monitoring: Track real-time successful, pending, or failed Aadhaar-based transactions like cash withdrawals, balance inquiries, and mini-statements.
- Agent & Retailer Onboarding: Review KYC documents, approve new Customer Service Point (CSP) agents, and manage user accounts across regional hierarchies.
- Wallet & Payout Settlements: Load funds, oversee ledger balances, and handle automated daily or real-time payout settlements for merchants.
- Commission Management: Configure, track, and disburse commission structures daily, weekly, or monthly across distributors and retailers.
- Reports & Analytics: Generate detailed audit logs, performance metrics, and location-based or time-based transaction analytics.
AEPS Banking Software User Hierarchy
An AEPS (Aadhaar Enabled Payment System) banking software user hierarchy typically follows a multi-tier Aeps B2B structure that flows downward from the primary software owner to the end customer.
AEPS Software User Tiers
- Super Admin / Admin (Company / Fintech): The top-level authority who owns the Aeps service software or white label Aeps b2b platform. They manage b2b Aeps API switches, assign master distributors, set global commission structures, monitor overall wallet balances, and track Aeps service platform-wide compliance and logs.
- Master Distributor (State / Zone Head): The regional manager appointed by the admin. They create and oversee regular distributors, manage regional floating funds or wallets, and earn an override commission on all transactions processed underneath their zone.
- Distributor (District / Area Partner): The middle-tier manager who handles local retail networks. They Aeps onboard, KYC-verify, and support local retailers/agents, while receiving margins/commissions from the transactions generated by their assigned retail chain.
- Retailer / Merchant / Business Correspondent (BC): The ground-level touchpoint (e.g., local kirana store or pharmacy). They connect Aeps biometric devices to process direct customer transactions like cash withdrawals, balance checks, and mini-statements, earning instant per-transaction commissions.
- Customer / End-User (Aadhaar Holder): The individual consumer who visits the retailer, provides their Aadhaar number, bank name, and buy Aeps fingerprint/buy Aeps biometric scan to complete cardless banking operations.
AEPS Banking Software
Aadhaar Enabled Payment System – Secure Banking Services
Features AEPS Banking Software
AePS (Aadhaar Enabled Payment System) banking software is a digital Aeps platform that lets local agents and retailers turn their shops into micro-ATMs for cardless and PIN-less financial transactions using Aadhaar-based biometric authentication.
Software & Management Features
- Biometric Integration: Connects seamlessly with Aeps fingerprint scanners and Aeps iris devices certified for UIDAI authentication.
- Real-Time Processing: Links directly with the National Payments Corporation of India (NPCI) network for instant transaction routing and clearance.
- Agent & Hierarchy Management: Tools for onboarding distributors and retailers, assigning member IDs, and managing performance.
- Automated Commission Slabs: Calculates and credits retailer or partner commissions instantly upon transaction settlement.
- Dashboard and Analytics: Centralized control Aeps panel providing live transaction logs, success rates, and ledger reports.
- API Integration: Allows Fast Aeps platform to embed banking capabilities into existing multi-recharge or mobile Aeps apps.
Benefits of AEPS Banking Software
Aadhaar Enabled Payment System (AEPS) banking software transforms local shops and agents into best micro ATM, allowing users to complete basic banking transactions using only their Aadhaar number and fingerprint.
Key Benefits of AEPS Banking Software
- Financial Inclusion: Extends formal banking and financial services to unbanked and underserved rural populations who live far from traditional bank branches.
- Cardless and PIN-less Banking: Eliminates the need for physical debit/credit cards, credit tokens, or remembering security PINs, relying entirely on biometric authentication (fingerprint or iris scans).
- Interoperability: Allows customers from any participating bank to conduct transactions at any AEPS-enabled micro-ATM or Aeps agent portal, regardless of the Aeps india.
- High Security: Reduces risks of fraud, password theft, and lost cards by using unique biometric markers that verify the exact identity of the account holder in real-time.
- Cost-Effective Infrastructure: Lowers operational costs for Aeps india by cutting down the need to build physical bank branches or maintain expensive standalone ATM networks.
- Government Subsidy Distribution: Streamlines direct benefit transfers (DBT) and welfare fund distributions straight into recipient accounts without delays or middleman leakage.
- Business Opportunities for Retailers: Gives local shop owners and business correspondents an additional stream of revenue through commission-based earnings on every successful transaction.
AEPS Banking API Integration
Integrating AEPS banking API (Aadhaar Enabled Payment System Application Programming Interface) allows your Aeps application or Aeps portal to offer secure, cardless, and PIN-less biometric banking services like cash withdrawals and balance checks.
Steps for AEPS Banking API Integration
- Planning and Vendor Selection: Choose a Aeps india matching your budget and technical scope (standard integration costs ₹12,000–₹35,000; white label Aeps portals cost ₹15,000–₹120,000). Define required services like balance inquiry, mini-statements, or cash withdrawals.
- Compliance and KYC Verification: Submit your business PAN card, Aadhaar, address proof, and settlement bank account details to complete Business Correspondent (BC) verification and clear due diligence checks. Sign the service-level agreement (SLA).
- Hardware Procurement: Procure a STQC-certified L1 Aeps biometric fingerprint or L1 Aeps iris scanner (such as Mantra or Morpho). Install the manufacturer-specific Registered Device (RD) service driver and SDK on your mobile device or terminal.
- Software and API Integration: Build or update your user interface to collect the 12-digit Aadhaar number, bank IIN (Institution Identification Number), and transaction type. Implement backend Aeps API logic to securely encrypt the captured biometric data.
- Testing in Sandbox: Connect endpoints in a restricted staging or sandbox environment provided by your vendor. Test mock transaction requests, verify responses (success, pending, or failed), and check security compliance.
- Go Live and Deployment: Move your Aeps Service API endpoints from sandbox to production. Complete your initial biometric self-authentication on the live network to activate your agent/merchant ID and start processing live transactions.
AEPS Banking Software Cost
An AEPS (Aadhaar Enabled Payment System) banking software cost structure typically ranges from ₹12,000 to ₹50,000 for basic-to-standard setups, while comprehensive white label Aeps portal or custom enterprise Aeps earning platform can cost anywhere from ₹1.5 lakh to over ₹4.5 lakh.
Breakdown of AEPS Software Costs
- Setup and Integration Fees: One-time Aeps Software development or Aeps API integration charges range from ₹12,000 to ₹35,000 depending on the Aeps india and custom features.
- White-Label Software Cost: Complete ready-to-deploy Aeps panel solution (portal, mobile app, and admin dashboard) range from ₹35,000 to ₹50,000.
- Per-Transaction Charges / Commissions: Rather than fixed monthly software licensing fees, Aeps india often charge or share a commission model. Transaction fees generally range from 0.5% to 1% per transaction (capped around ₹15) or operate on a revenue-sharing/slab basis.
- Interchange & Agent Commissions: NPCI sets standard interchange fees between banks (e.g., ₹5 for cash withdrawal, ₹1 for balance inquiry), out of which agents typically earn Aeps commission of ₹5 to ₹20 per successful withdrawal.
Key Components Included in the Cost
- API Integration: Connects Aeps earning platform to NPCI-approved banking rails for biometric authentication, cash withdrawals, balance inquiries, and mini-statements.
- Wallet & Commission Management: Automated real-time settlement and high Aeps commission distribution across admin, distributor, and retailer accounts.
- KYC & Security Compliance: Built-in two-factor biometric validation security and reporting dashboards.
Transaction & Operational Fees
- Transaction/Commission Fees: Often structured as a commission of 0.5% to 1% or a flat ₹5 to ₹15 per transaction depending on the volume and slab rates.
- Maintenance & Support: Ongoing technical support and hosting fees may apply quarterly or annually depending on AEPS India vendor contract.
AEPS Banking Software Commission & Earnings
AEPS (Aadhaar Enabled Payment System) banking software commission structures typically range from ₹5 to ₹15+ per successful cash withdrawal, varying by transaction slab size, Aeps india interchange fees.
- Balance Inquiry & Mini Statement: Usually free for customers; agents earn a nominal fee or zero-to-minimal incentive (around ₹1 where applicable).
- Cash Withdrawal Slabs (Retailer/Agent Earnings):
- ₹100 – ₹999: ₹1 to ₹2 per transaction
- ₹1,000 – ₹1,499: ₹3 per transaction
- ₹1,500 – ₹1,999: ₹4.50 per transaction
- ₹2,000 – ₹2,499: ₹5.50 per transaction
- Higher Slabs (₹3,000 – ₹10,000): Can range anywhere from ₹7 up to ₹13–₹15 on high Aeps commission portal (often structured with bonus additions like ₹13 + ₹2 promotional incentives).
Non-Withdrawal Services
- Balance Enquiry / Mini Statement: Usually free for customers; agents earn a nominal fee or zero direct commission, though Aeps india offer small promotional rewards (₹0.25 to ₹1 per check).
- Aadhaar-to-Aadhaar Fund Transfer / Aadhaar Pay: Aeps Commission depends on merchant fee structures or flat interchange values set by NPCI.
Core Revenue & Interchange Model
- Software/API Setup Costs: Licensing or white-label AEPS payment software setup generally ranges from ₹12,000 to ₹35,000, with recurring high speed Aeps API commission splits or capping around 0.5% to 1% per transaction.
- NPCI Interchange Guidelines: The underlying inter-bank fee set by the NPCI generally assigns an interchange of around ₹5 for cash withdrawals, ₹10 for cash deposits, and ₹1 for balance inquiries which banks settle among themselves. Aeps india share a portion of these margins or subsidize them to attract retail agents.
AEPS Banking Software and Biometric Device Integration
AEPS (Aadhaar Enabled Payment System) banking software and biometric device integration enables local retail shops and Aeps fintech platform to function as cardless, PIN-free “micro-ATMs” via the National Payments Corporation of India (NPCI) network.
Core Technical Architecture & Workflow
- Initiation: An agent enters the customer’s 12-digit Aadhaar number, bank name, and transaction type (such as cash withdrawal or balance inquiry) into the AEPS application solution.
- Biometric Capture: The customer scans their finger or iris on a certified Aeps scanner.
- Registered Device (RD) Services: Hardware-level encryption of the biometric block occurs via manufacturer-specific SDKs using mandatory, STQC-L1 Aeps devices.
- API Routing: Encrypted JSON/XML payloads travel over secure HTTPS protocols through the reliable AEPS API integration service to the NPCI switch and UIDAI database for validation.
- Settlement: Upon successful bank authorization, funds transfer instantly to the agent’s digital wallet or business account.
Key Integration Requirements
- NPCI-Certified API Provider: Partner with a Aeps india to obtain sandbox documentation and Aeps API keys.
- Hardware Compliance: Use UIDAI/STQC-certified L1 Aeps biometric fingerprint or L1 Aeps iris scanner device (such as Mantra devices) connected via USB or Bluetooth.
- Business Verification: Complete mandatory merchant onboarding, business PAN/Aadhaar verification, and video/biometric KYC protocols.
AEPS Banking Software Wallet Management System
An AEPS Banking Software with a Wallet Management System is a centralized digital Aeps b2b platform that enables micro ATM operators, business correspondents, and local retailers to handle cardless, biometric-based banking transactions and track digital ledgers.
Core Features of AEPS Wallet Management
- Real-Time Ledger Tracking: Automatically logs credits and debits for every cash withdrawal, balance inquiry, or mini-statement processed via Aadhaar authentication.
- Liquidity and Balance Monitoring: Provides a clear dashboard view of main operating balances, available agent float, and settlement ledgers.
- Automated Settlement Engine: Handles instant or scheduled (T+0 / T+1) bank settlements and moves funds securely down the retail chain.
- Commission Management: Automatically calculates and distributes margins and commission slabs for retailers, distributors, and master admins.
- Hierarchy and Role Control: Manages multi-level user networks including super admins, white label Aeps, distributors, and local merchants.
AEPS Banking Software Commission Management System
An AEPS Software commission management system is a backend and dashboard tool that automatically calculates, tracks, and distributes earnings for Aadhaar-enabled banking transactions across a network of agents, Aeps distributors and Aeps admins.
Core Features of Commission Management
- Automated Commission Engine: Instantly calculates and splits margins for every transaction (cash withdrawal, balance check, mini-statement) based on pre-set slab rates.
- Multi-Tier Hierarchy Splitting: Distributes margins dynamically across layers, including Super Distributors, Master Distributors, Distributors, and Retail Agents.
- Real-Time Tracking Dashboards: Displays live transaction counts, successful payouts, and total earnings accrued for individual agents and admins.
- Instant Wallet Settlement: Credits earned commissions directly into user digital wallets or bank accounts immediately after transaction completion.
- Custom Slab Configuration: Allows Aeps administrators to customize commission percentages or flat fees depending on transaction volume or specific bank routing.
AEPS Banking Software Business Model
An Aadhaar Enabled Payment System (AePS) banking software business model turns local retail shops and service points into digital mini-banks by using biometric authentication for cardless transactions.
Core Components of the Business Model
- Technology Infrastructure: The Aeps india delivers Aeps transaction API, user dashboards, Aeps wallet system and biometric device integration (like fingerprint or iris scanners).
- Hierarchical Distribution: Operations scale through a multi-tier channel, typically structured as Admin/Fintech → Super Distributor → Distributor → Retailer/Agent.
- Transaction Services: Retailers act as Business Correspondents (BCs) processing cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay for customers across interoperable banks.
Revenue and Monetization Flow
- Commission Slabs: Agents, distributors, and branded Aeps platform owners earn a commission or markup split on every successful financial transaction.
- White-Label Licensing: Aeps indias charge setup fees, recurring maintenance, or subscription fees to businesses wanting their own branded Aeps portals.
- API Monetization: Aeps india charge per-hit or volume-based pricing for external apps integrating their AEPS Banking API.
AEPS Banking Software Transaction Flow – Step by Step
An Aadhaar Enabled Payment System (AePS) software transaction flows through a secure, centralized switch managed by the National Payments Corporation of India (NPCI) to connect the customer’s bank account with a best micro ATM device.
Step-by-Step Transaction Flow
Step 1: Customer Details Input
- The customer visits an authorized AePS touchpoint or micro-ATM and provides their 12-digit Aadhaar number and the name of their bank.
Step 2: Transaction Selection
- The agent or retailer selects the required service on the AePS Software Portal (such as cash withdrawal, balance inquiry, or mini-statement) and enters the transaction amount if applicable.
Step 3: Biometric Capture
- The customer places their finger on a certified Aeps biometric scanner attached to the micro-ATM or POS device to scan their fingerprint.
Step 4: Encryption at Terminal
- The Aeps device or mobile Aeps app encrypts the biometric data and transaction details locally before sending the request securely over the internet.
Step 5: Routing via NPCI Switch
- The encrypted request goes to the centralized NPCI switch, which acts as the core router for all Aadhaar-based banking transactions.
Step 6: UIDAI Authentication
- The NPCI switch forwards the biometric data to the Unique Identification Authority of India (UIDAI) to verify the customer’s identity against their stored Aadhaar profile.
Step 7: Bank Authorization
- Once UIDAI confirms a successful match, the request routes to the customer’s specific issuer bank to check account balance and authorize the financial debit or inquiry.
Step 8: Response and Settlement
- The issuer bank sends a success or failure response back through the NPCI switch to the retailer’s terminal, generating a Reference Number (RRN) and printing a receipt upon success.
AEPS Banking Software Admin Panel
An AEPS B2B Admin Panel is a centralized branded Aeps software dashboard that lets fintech companies and entrepreneurs manage Aadhaar Enabled Payment System operations, retailer networks, and fund settlements under their own brand.
Core Features
- White-Labeling: Rebrand Aeps portal with your own company logo, custom domain, and color schemes.
- Hierarchy Management: Create and oversee multi-tier user networks including master distributors, distributors, and local retailers
- Wallet & Commission Engine: Manage dual-wallet systems (Main and AEPS wallets) and configure custom Aeps commission slabs for agents.
- Transaction Monitoring: Track cash withdrawals, balance inquiries, and mini-statements in real time.
- Fraud Control & Support: Investigate failed transactions, process instant refunds, and handle automated dispute resolution.
AEPS Settlement and Reconciliation
AEPS Operating and Settlement Guidelines govern how the National Payments Corporation of India (NPCI) handles transaction clearing, daily balancing, and dispute management for the best Aadhaar Enabled Payment System.
AEPS Settlement Process
- NTSL File: Settlement happens using the Net Total Settlement Limit (NTSL) file provided by the top AEPS switch, which summarizes the net financial position for every member bank.
- Timeline: Settlements generally occur on a T+0 or T+1 cycle, transferring funds among issuer banks, acquirer banks, and business correspondents.
- BCS Admin Portal: Member banks use designated administrator IDs on the NPCI BCS system to manage user permissions, access reports, and process secure PGP-encrypted files.
AEPS Reconciliation Steps
- Transaction Logging: Capturing all raw transaction logs (successful, declined, and pending requests) containing transaction IDs, timestamps, amounts, and Aadhaar/IIN data.
- Cross-Checking: Matching internal merchant/bank logs against the central switch settlement files to find discrepancies or unmatched entries.
- Dispute and Chargeback Handling: Raising adjustments, processing chargebacks, and resolving failed or misrouted transaction counts.
- Liability: Member banks bear full financial responsibility for any losses if they fail to complete daily reconciliation on a T+1 basis.
AEPS Admin, Distributor and Retailer Panel
An AEPS B2B Admin Panel is a centralized backend system used by Aeps india to manage hierarchical multi-tier digital banking networks, including master distributors, distributors, and retailers.
Panel Roles and Hierarchy
- Admin Panel: The master command center providing full oversight of system margins, Fast Aeps API integrations, global commission structures, transaction audits, and network-wide compliance.
- Distributor Panel: An intermediate management tier used to onboard, monitor, and assign custom Aeps commission slabs to regional agents or retailers.
- Retailer Panel: The front-line agent interface connected to Aeps biometric fingerprint device or Aeps iris scanner device to execute direct customer transactions like cash withdrawals and balance inquiries.
Security Features in AEPS Banking Software
Aadhaar Enabled Payment System (AePS) banking software uses biometric verification and end-to-end encryption to ensure secure, cardless transactions.
Core Security Features
- Biometric Authentication: Users confirm identity using a unique fingerprint or iris scan via a UIDAI-certified Aeps scanner, removing the need for a debit card or PIN.
- Registered Device (RD) Integration: Software communicates only through certified RD services that encrypt biometric data at the device level before transmission.
- End-to-End Encryption (E2EE): Data in transit (such as Aadhaar numbers and biometric captures) is locked using strong protocols like SSL/TLS to prevent interception.
- UIDAI Central Verification: Identity matches are routed securely through the NPCI switching gateway directly to UIDAI servers for validation.
- Double Authentication: Critical actions like specific fund transfers require multi-step verification checks within the network.
AEPS Banking Software Compliance & Ecosystem
Top Aadhaar Enabled Payment System software enables cardless, PIN-less banking transactions through biometric authentication via business correspondents.
Compliance Mandates
- UIDAI Standards: Software must not store raw biometric data locally and must use approved L1 certified registered devices.
- NPCI & RBI Framework: High volume Aeps Platform must enforce the “One-Agent-One-Bank” linking rule and support real-time secure switching.
- Data Security: Strict data retention limits apply, prohibiting long-term storage of sensitive transaction logs and Aadhaar details.
Ecosystem Architecture
- Core APIs: Integrates real time AEPS API connections for instant balance inquiries, cash withdrawals, and mini-statements.
- Hardware Layer: Requires STQC-certified L1 Aeps fingerprint or purchase Aeps iris scanner device linked via registered device (RD) services.
- Agent Infrastructure: Transforms local retail shops into micro-ATMs or mini-banks supported by instant settlement pipelines.
White Label AEPS Banking Software
A white-label AEPS (Aadhaar Enabled Payment System) banking software is a pre-built, ready-to-deploy digital banking solution that allows you to launch custom-branded biometric banking services under your own company name, logo, and domain.
Key Features Included
- Core Banking Services: Cash withdrawals, balance inquiries, mini-statements, and Aadhaar-to-Aadhaar fund transfers via biometric fingerprint/iris authentication.
- Value-Added Services (VAS): Integrated BBPS (Bharat Bill Payment System) for utility bills, mobile/DTH recharges, and Domestic Money Transfer (DMT).
- Administrative Control: Complete Aeps admin dashboard to manage retail and distributor hierarchies, track real-time transactions, and configure automated commissions.
- Multi-Platform Support: Ready web portals and Android mobile Aeps application.
Common AEPS Banking Software Transaction Errors and Troubleshooting
Common Aadhaar Enabled Payment System (AePS) software transaction errors typically involve biometric authentication failures, unlinked Aadhaar numbers, or network timeouts.
Frequent AePS Errors and Troubleshooting
Biometric Authentication Failed
- Causes: Poor fingerprint quality, dry/dirty fingers, or a dusty scanner.
- Troubleshooting: Clean the user’s finger and the scanner glass, ensure proper finger placement, or update the biometric device RD service/drivers.
Aadhaar Not Linked to Bank (Error Code 52)
- Causes: The 12-digit Aadhaar number is not mapped or synchronized with the selected bank account.
- Troubleshooting: Ask the customer to link their Aadhaar via their home bank branch or netbanking. If recently linked, wait 24–48 hours for system synchronization before retrying.
Insufficient Account Balance
- Causes: The account does not have enough funds to cover the requested withdrawal amount or bank charges.
- Troubleshooting: Perform a balance inquiry first to confirm available funds before attempting a cash withdrawal.
Issuer or Switch Inoperative / Bank Server Down
- Causes: Technical failure or scheduled maintenance on the issuer bank’s core banking system or NPCI switch.
- Troubleshooting: Wait a few minutes and retry the transaction. If the customer’s account gets debited during a timeout, inform them that a reverse credit typically happens automatically within 3 to 5 working days per RBI guidelines.
Network Connectivity / Timeout Issues
- Causes: Unstable internet connection at the merchant terminal or Aeps API gateway delays.
- Troubleshooting: Switch to a Aeps india on your micro-ATM/pos device.
AEPS Banking Software vs AEPS B2B Software
Aadhaar Enabled Payment System (AePS) banking software generally refers to core, bank-level or high-end institutional infrastructure that connects directly to financial switches, whereas AePS B2B software is a white label Aeps platform or advanced Aeps API-driven ready-made portal meant for fintech startups, distributors, and retailers to offer micro-banking services.
AEPS Banking Software vs. AEPS B2B Software Comparison
| Feature / Parameter | AEPS Banking Software (Core / Enterprise) | AEPS B2B Software (White-Label / Portal) |
|---|---|---|
| Primary Target User | Commercial banks, large financial institutions, or Tier-1 fintechs with direct NPCI/bank ties. | Fintech entrepreneurs, master distributors, retailers, and local service shops. |
| Setup & Architecture | Deep integration with central banking switches, custom node configuration, and direct sponsor-bank pipelines. | Ready-to-use white-label panel with pre-integrated Aeps APIs, multi-tenant dashboards, and modular UI. |
| Compliance & Certification | Requires independent, rigorous compliance, security audits, and direct NPCI/UIDAI onboarding. | Operates on the parent provider’s pre-approved NPCI infrastructure; no separate independent certification needed. |
| User Hierarchy Management | Manages core transaction routing, switch balancing, and inter-bank dispute settlements (chargebacks). | Manages multi-level downline networks—Admin, Master Distributors, Distributors, and Retailers/Agents. |
| Deployment Cost | Extremely high (lakhs to crores, involving dedicated server infrastructure and legal/banking pacts). | Nominal to moderate setup cost (ranges from ₹10,000 to over ₹1,00,000 depending on white-label branding). |
| Core Functionality | Transaction switching, UIDAI biometric data decryption handling, and raw ledger posting. | Cash withdrawal, balance inquiry, mini-statement, Aadhaar Pay API, and automated commission slab tracking. |
Aeps india one of the Best AEPS Banking Software Provider in India
Aeps india one of the best AEPS banking software provider requires evaluating core factors like security compliance, transaction success rates, and multi-bank routing support.
Key Factors to Choose the Best AEPS Software Provider
Security and Compliance
- Ensure the Aeps india complies with NPCI and UIDAI regulations, featuring end-to-end HTTPS encryption, secure biometric authentication, and adherence to the OWASP Aeps API Security Guide.
Transaction Success Rate and Uptime
- Look for Aeps transaction platform offering 98% to 99%+ Aeps API uptime and multi-bank routing (15+ bank connections) to minimize failed transactions and maintain retailer trust.
Settlement Speed and Transparency
- Aeps india with fast, automated, or same-day payout cycles and clear pricing structures to avoid unexpected hidden deductions that eat into profits.
Integration and Developer Support
- Prioritize Highest volume Aeps platform with clean documentation, responsive Aeps developer assistance, and robust sandbox testing environments for smooth Aeps API deployment.
White Label and Management Features
- Verify if the trusted Aeps software supports customizable white label Aeps modules, such as Aeps admin dashboards, retailer/distributor portals, and real-time commission tracking.
Device Compatibility and Support
- Confirm that the software supports standard certified Aeps biometric scanners (fingerprint and iris) and micro ATM hardware.
Customer Technical Support
- 24/7 assistance via call or chat is critical to resolve sudden integration bottlenecks, operational errors, or failed transactions quickly.
Why Choose Aeps India for AEPS Banking Software?
Aeps india is a reliable AEPS banking software solution requires evaluating key technical, financial, and regulatory factors.
Key Factors to Consider
- Security & Regulatory Compliance: Ensure the Aeps india is fully compliant with NPCI (National Payments Corporation of India) and UIDAI guidelines, featuring end-to-end data encryption and certified biometric device compatibility (such as Mantra or Morpho).
- Transaction Success Rate & Uptime: Look for a Aeps platform delivering high uptime (99% or higher) and fast processing speeds to minimize failed transactions and maintain customer trust.
- Settlement Speed & Payout Cycles: Fast or real-time settlements (T+0 or T+1) are critical for maintaining healthy cash flow and retailer confidence.
- Commission & Pricing Structure: Compare per-transaction earnings, payout frequencies, and watch out for hidden charges that can reduce profit margins.
- Integration & Documentation Quality: Opt for Aeps india developers offering clear Aeps API documentation, sandbox testing environments, and responsive technical support to simplify deployment.
- Dashboard & Reporting Tools: A robust Aeps admin panel with real-time analytics, transaction history, and multi-bank interoperability makes managing agents and tracking commissions easier.
How to Get Started With AEPS Banking Software?
AEPS Banking Software provides a technology Aeps platform for businesses that want to offer Aadhaar-enabled banking services through authorised service points. It can bring AEPS transactions, retailer management, distributor management, wallet operations, commissions, reports and service controls together in one centralized system.
AEPS supports banking services such as cash withdrawal, cash deposit, balance enquiry and mini statement, depending on the applicable fast AEPS setup and participating banking arrangements. The bank-led nature of AePS makes the underlying banking and authentication infrastructure an important part of any Aeps software implementation.
AEPS (Aadhaar Enabled Payment System) banking software is a digital Aeps service platform that lets local retailers and fintech agents provide cardless and PIN-less banking services using a customer’s Aadhaar number and Aeps fingerprint scan system.
For a business, choosing AEPS Banking Software should not be based only on the number of features listed on a website. The platform should support the actual requirements of the business, including AEPS API integrate, retailer and distributor onboarding, transaction management, wallet and ledger management, commission management, settlement tracking, reports, role-based access, security controls and technical support.
A scalable AEPS Banking Software Solution can also help businesses manage a multi-level network of retailers and distributors. Through dedicated dashboards and access permissions, administrators can monitor transactions, manage users, configure services and review business activity from a central high speed Aeps platform.
Integration is another important consideration. The reliable Aeps software needs to communicate correctly with the required AEPS service infrastructure and handle transaction requests, responses and status updates properly. The exact AePS Balance Enquiry API workflow, supported services, authentication requirements and transaction limits can vary according to the selected provider and banking arrangement.
For businesses planning to operate under their own brand, White Label AEPS Banking Software can provide a branded Aeps b2b platform with customized interfaces and business controls. Additional services such as Best BBPS, money transfer software, recharge, Aadhaar Pay Software or other digital financial services may also be integrated when the required infrastructure and partnerships are available.
If you are planning to launch or expand an AEPS-based digital banking business, Aeps India can help you explore an AEPS Banking Software solution according to your business requirements.
Contact Aeps India to discuss your AEPS Banking Software requirements, explore available features and understand the suitable setup for your retailer, distributor or fintech business.
Build your AEPS service platform with a solution designed around your business model, transaction requirements and future growth.
Frequently Asked Questions About AEPS Banking Software
AEPS Banking Software is a technology platform that enables businesses to offer Aadhaar-based banking services through an integrated portal. It can manage AEPS transactions, users, wallets, commissions, settlements, reports, and retailer or distributor networks.
The software connects the Aeps india Server with the required banking and AEPS infrastructure. The customer provides the required Aadhaar/Virtual ID and authentication, the transaction is processed, and the high volume Aeps software displays the transaction result and records it for reporting and reconciliation.
Depending on the platform and supported AEPS services, it can provide cash withdrawal, cash deposit, balance enquiry, mini statement, fund transfer and Aadhaar Pay. NPCI documentation lists the core AePS transaction types including balance enquiry, cash withdrawal, cash deposit, fund transfer and mini statement.
AEPS Banking Software can be used by fintech businesses, financial-service distributors, retailers, Business Correspondent networks and organisations that want to provide supported top AEPS services through an authorised business model.
You generally need an eligible business setup, appropriate Aeps onboarding/KYC, an authorised AEPS service arrangement, a suitable software platform, supported biometric hardware where required, and the required technical and operational setup.
For AePS financial transactions, Aadhaar/Virtual ID authentication and biometric authentication are fundamental parts of the process. The specific authentication method and device requirements depend on the applicable AePS and UIDAI specifications.
White Label AEPS Banking Software allows a business to offer an Aadhaar Enabled Payment System platform under its own brand. Depending on the Aeps india, it may include b2b Aeps portal, wallet management, commission configuration, user management, AEPS activation and retailer/distributor management.
An AEPS admin panel is the central dashboard used to manage the trusted AEPS platform. It can provide control over users, retailers, distributors, transactions, wallets, commissions, settlements, reports and other operational settings.
Yes. AEPS software provide a central system for onboarding distributors and retailers, assigning roles or IDs, managing access, monitoring transactions and maintaining the distribution hierarchy.
An AEPS wallet system maintains the financial balance associated with the applicable business or distribution hierarchy. Depending on the platform, administrators can manage wallet credits, debits, balances, transaction history and related reports.
Commission management can be configured through predefined slabs or business rules. The professional Aeps software can calculate applicable commissions for transactions, maintain commission records and provide reports for retailers, distributors and administrators.
Settlement is the process of reconciling eligible transactions and transferring or accounting for the applicable funds according to the service and partner arrangement. Secure Aeps Software can help track settlement status, transaction records, wallet entries and reconciliation reports.
Yes. Where Aeps API integrating is supported, AEPS functionality can be connected with an existing fintech application, website, mobile application or best Aeps B2B platform. The exact integration method depends on the secure Aeps API and technical requirements.
AEPS Software is generally a ready-to-use smooth Aeps platform containing interfaces and management features for operating AEPS services. AEPS API provides the technical connectivity required to integrate AEPS functionality into an existing best Aeps application or custom Aeps platform.
The cost depends on factors such as standard Aeps software type, white-label requirements, trusted Aeps API integration, supported services, user/network size, hardware, onboarding, support and commercial transaction arrangements. Aeps india should be contacted for pricing based on the required setup.
Compare the available AEPS services, Aeps platform features, Aeps API capabilities, security controls, wallet and commission management, settlement and reporting features, scalability, technical support, onboarding process and commercial terms before selecting a provider.
Yes. It can be suitable for fintech startups that want to add supported AEPS banking services without developing the complete Aeps platform infrastructure from the beginning. The appropriate model depends on the startup’s network, technical requirements and business arrangement.
Yes. White label AEPS platforms can allow businesses to operate the software using their own brand, Aeps india available white-label features and applicable business, technical and regulatory requirements.
You can begin by discussing your business requirements with Aeps India, selecting the required most AEPS software or integration model, completing the applicable onboarding and Aeps KYC process, configuring your Aeps platform service and user network, and proceeding with testing and activation according to the applicable service arrangement.

High Commission AEPS App for Retailers in India
AEPS System in India: How It Works for Banking Transactions
AEPS Live Explained: Everything You Need to Know
About Author

