White Label AEPS Platform in India: Complete Guide to Cost, Features, Benefits & Setup
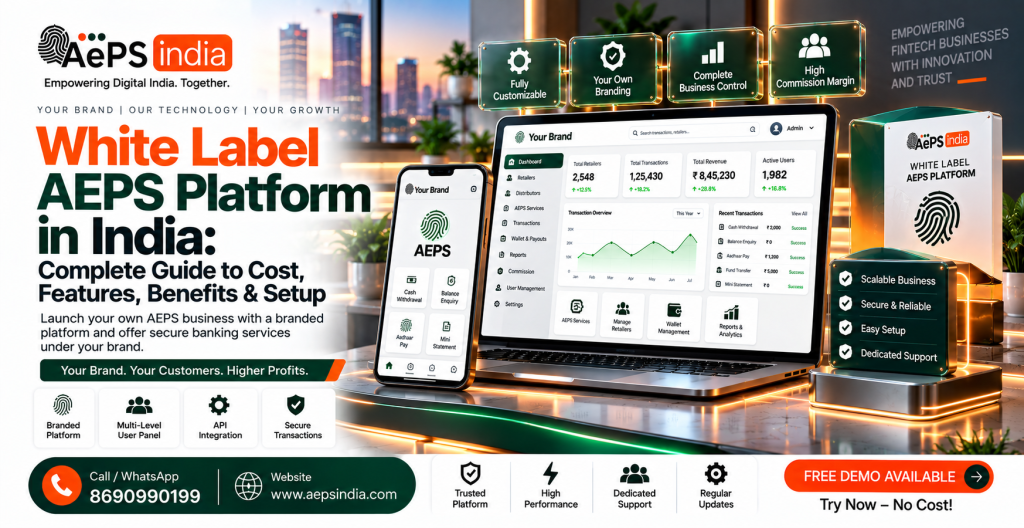
Starting an AEPS business under your own brand requires more than just an AEPS API. A White Label AEPS Platform provides a ready-to-brand technology solution that can help fintech companies, payment businesses, distributors, and digital service providers offer supported Aadhaar Enabled Payment System services under their own business identity.
With a white-label platform, the technology provider manages the underlying software while the business can operate the Aeps platform using its own brand name, logo, domain, website, application, and business interface, depending on the selected Aeps india. This can reduce the time and technical effort required to build AEPS platform completely from the beginning.
A White Label AEPS Platform is a ready-made, customizable Aeps software solution that lets you launch your own branded Aeps and digital banking business without building the technology from scratch.
A complete White Label AEPS Platform can include an Aeps admin panel, Aeps retailer panel, Aeps distributor panel, AEPS API integration, user Aeps onboarding, transaction management, wallet or ledger management, commission controls, reports, service management, and other business-management features. The exact features depend on the Aeps india and customization requirements.
AEPS allows customers to access supported banking services through authorised touchpoints using Aadhaar-based authentication. Depending on the available best AEPS infrastructure, services can include cash withdrawal, balance enquiry, mini statement, cash deposit, and other supported transactions. Businesses should confirm the exact services and transaction flow available through their selected Aeps india before launching Aeps platform.
For a growing AEPS business, retailer and distributor management is an important part of the Aeps b2b platform. A white label Aeps system can provide separate access levels so that the business owner can manage its network, while retailers and distributors can use their respective Aeps dashboard for transactions and other permitted activities.
AEPS API Integration is another important part of a white label Aeps platform. The Aeps API connects the Aeps application with the required best AEPS service infrastructure and handles transaction requests, responses, status information, and other required data. A reliable implementation should also consider authentication, transaction security, error handling, callbacks or status updates, and proper server-side processing.
The cost of a White Label AEPS Platform is not the same for every business. Pricing can depend on the features included, best Aeps API or service charges, number of users, customization, Android Aeps application or web application requirements, admin and distributor panels, branding, hosting, technical support, and additional financial services. Therefore, businesses should compare the complete solution rather than looking only at the initial Aeps software price.
A white label AEPS platform can be useful for fintech startups, payment service businesses, AEPS distributors, digital service centers, retailers, entrepreneurs, and companies that want to build their own branded financial-services platform. It can also be combined with other services such as BBPS, DMT, recharge, payout, or other digital payment services when the required integrations are available.
At Aeps India, businesses can explore a White Label AEPS Platform based on their business model and operational requirements. The solution can be planned around branding, retailer and distributor management, AEPS integration, transaction processing, reporting, Aeps wallet management, Aeps commission, applications, and other required features.
If you want to launch AEPS services under your own brand, selecting a b2b Aeps platform that matches your required services, business structure, technical requirements, scalability, and support needs is an important first step.
In this complete guide, you will learn what a White Label AEPS Platform is, how it works, its key features, benefits, AEPS API integration, retailer and distributor management, wallet and commission management, security considerations, customization options, White Label AEPS Platform cost, setup requirements, and how to choose the right solution for your business.
What Is a White Label AEPS Platform?
A White Label AEPS Platform is a pre-built, ready-to-use software solution for the Aadhaar Enabled Payment System that businesses can rebrand and launch under their own company name, logo, and domain.
How Does a White Label AEPS Platform Work?
A white-label AEPS platform is a ready-made, customizable banking software that lets a business offer Aadhaar-enabled payment services under its own brand name and logo.
How It Works
- The Provider Build the Tech: AEPS India owns the core Aeps bank API, server infrastructure, and bank connections.
- Rebranding: You purchase or license Aeps software and apply your own company name, domain, colors, and logo.
- Network Creation: You act as the Aeps admin. You can create accounts for distributors, retailers, or local merchants who use the best Aeps system on the ground.
- Customer Transactions: A customer visits an agent, provides their Aadhaar number, selects a bank, and scans their fingerprint on a certified Aeps biometric device to complete a transaction.
- Real-Time Settlement: The top Aeps system authenticates the user via UIDAI and the National Payments Corporation of India (NPCI), processing the cash movement instantly.
AEPS Services Available on a White Label Platform
An AEPS White Label Platform allows businesses to launch custom-branded digital banking and financial portals using pre-built infrastructure without developing the technology from scratch.
Core AEPS Services
- Cash Withdrawal: Customers can withdraw money from their bank accounts using biometric authentication (fingerprint scanner).
- Balance Enquiry: Real-time checking of bank account balances via Aadhaar verification.
- Mini Statements: Access to recent transaction histories and account logs.
- Aadhaar-to-Aadhaar Fund Transfers: Direct peer-to-peer or account-to-account money movements.
Documents Required for White Label AEPS Platform
To launch a White Label AEPS (Aadhaar Enabled Payment System) Platform, you must submit comprehensive corporate, financial, and personal KYC documentation to your API or software provider to comply with NPCI and banking partner regulations.
1. Company & Business Entity Proofs
If you are registering as a registered company or private limited firm, you need core incorporation records:
- Certificate of Incorporation: Proof that your business is legally registered.
- MOA & AOA: Memorandum of Association and Articles of Association outlining company scope.
- PAN Card of the Company: For corporate tax and financial tracking compliance.
- Board Resolution: A formal signed resolution authorizing the launch of the AEPS portal and designating authorized signatories.
2. Director / Promoter KYC Documents
Personal identification records for all directors or authorized Aeps india:
- Photo ID Proof: Aadhaar Card, Voter ID, or Passport.
- PAN Card: Mandatory personal tax ID for all directors.
- Address Proof: Utility bill, passport, or recent lease agreement.
- Passport-Sized Photographs: Recent photographs of the directors/promoters.
3. Business Address & Outlet Proof
- Company/Office Address Proof: Electricity bill, property tax receipt, or rent agreement.
- Business Registration Proof: Shop & Establishment Certificate, GST Registration, or MSME/Udyam Certificate.
4. Financial & Settlement Details
- Cancelled Cheque or Bank Statement: A company bank account proof or bank statement/memo required for settling daily commission earnings and payout liquidity.
5. Technical & Hardware Prerequisites
While not “documents,” these are mandatory Aeps onboarding requirements:
- Biometric Device: STQC-certified Aeps fingerprint or Aeps iris scanner (such as Mantra) for authentication.
- Digital KYC: Completion of Video KYC or physical biometric verification for the best Aeps admin promoter.
Who Use White Label AEPS Platform
Fintech startups, entrepreneurs, and digital service providers use White Label AEPS platform to launch branded banking and financial services without building the technology from scratch.
Who Uses White Label AEPS Platforms?
- Fintech Startups & Entrepreneurs: Aeps india wanting to enter the digital payments market quickly under their own brand name and logo.
- Distributor & Super Distributor Networks: Businesses that manage a chain of regional agents and want to control commissions, tracking, and transaction limits.
- Retailer Networks & Local Shops: Local store owners and Common Service Center (CSC) operators who want to offer mini-banking services (cash withdrawals, balance checks) to rural or underserved customers.
- MSMEs & Digital Service Businesses: Aeps india expanding their service portfolio to include utility payments, domestic money transfers (DMT), and Aadhaar-based payouts.
Top Use Cases of White Label AEPS Platform
A white label AEPS (Aadhaar Enabled Payment System) platform is a ready-made, brandable digital banking infrastructure that allows businesses to offer biometric-based financial services under their own company name and logo.
Top Use Cases of White Label AEPS Platforms
- Fintech Startups & Neo-Banks: Launch proprietary digital banking applications and micro ATM networks quickly without spending months or lakhs on core Aeps banking Software development.
- B2B Multi-Level Reselling Networks: Build and manage hierarchical distribution networks (Master Distributors, Distributors, and Retailers) to earn Aeps commission margins on every transaction.
- Local Retailer & Kirana Store Enablers: Transform local brick-and-mortar shops into mini-banks or cash-points where customers can walk in for instant cash withdrawals and balance checks.
- Assisted Rural Banking & Financial Inclusion: Extend basic financial services like mini-statements and cash deposits to unbanked, semi-urban, or rural regions using Aadhaar biometric verification.
- Embedded Value-Added Services (VAS): Bundle AEPS with secondary financial features such as BBPS Software, and mobile recharges inside a single unified portal.
White Label AEPS Mobile App in Important
A White Label AEPS Mobile App lets businesses launch a custom-branded Aadhaar Enabled Payment System application without building the banking infrastructure from scratch.
Why It Is Important
- Fast Market Launch: Cuts Aeps software development and regulatory Aeps setup times down from months or years to just a few days.
- Low Initial Investment: Removes the massive costs of custom coding, heavy technical overhead, and security audits.
- Full Brand Ownership: Displays your own company logo, custom color schemes, and domain name directly to users and agents.
- Built-in Regulatory Compliance: Integrates mandatory RBI guidelines, NPCI protocols, and biometric safety frameworks automatically.
- Revenue and Network Growth: Empowers you to run Aeps B2B network by onboarding sub-distributors, managing merchant commissions, and tracking real-time payouts.
White Label AEPS Platform for Fintech Startups
A white-label AEPS platform is a ready-made Aadhaar Enabled Payment System software that lets you launch banking services under your own brand name and logo.
Benefits for Startups
- Rapid Deployment: Launches in weeks instead of 12–18 months of custom coding.
- Low Initial Cost: Starts at budget-friendly Aeps setup fees (approx. ₹50,000 upwards) compared to massive core development costs.
- Focus on Growth: Shifts your energy entirely to marketing, distribution, and merchant acquisition.
White Label AEPS Platform for B2B Networks
A white-label AePS (Aadhaar Enabled Payment System) platform lets you launch a fully branded digital banking and financial services portal under your own company name, logo, and domain without building the technology from scratch.
Benefits for B2B Entrepreneurs
- Zero Development Cost: Skip building complex banking middleware or undergoing lengthy direct Aeps API integrate from scratch.
- Fast Go-Live: Platforms are pre-loaded with KYC verification, wallet systems, and reporting tools ready for immediate deployment.
- New Revenue Streams: Earn a passive Aeps commission on every transaction processed by your sub-distributors and retail network.
White Label AEPS Retailer & Distributor Management
A White Label AEPS platform lets you launch your own branded digital banking business using pre-built technology from a Aeps india.
How Retailer & Distributor Management Works
- Full Admin Control: You get a master admin panel to manage your entire business hierarchy under your own logo, domain name, and brand colors.
- Multi-Tier Creation: Create and manage unlimited accounts for Master Distributors, Distributors, and Retailers directly from your dashboard at no extra hierarchy cost.
- Commission Slabs: Set and customize individual commission and surcharge structures for each distributor and retailer tier.
- Onboarding & Tracking: Track real-time transaction volumes, monitor live wallet balances, and verify agent KYC approvals.
White Label AEPS Platform Business Model
A White Label AEPS (Aadhaar Enabled Payment System) Platform lets you launch your own branded digital banking and micro-ATM business using pre-built technology from a Aeps india.
How the Business Model Works
- Structure Hierarchy: Parent API/Tech Provider → You (White Label Owner) → Distributors → Retailers/Agents → Customers.
- Branding Control: Operate via your own logo, company name, custom domain, and Android mobile application.
- Service Stack: Bundle AePS (cash withdrawals, balance checks, mini-statements) alongside BBPS (Bill Payments).
Features White Label AEPS Platform
A White Label AEPS (Aadhaar Enabled Payment System) Platform is a ready-to-use digital banking solution that lets businesses launch financial services under their own brand name and logo.
Core Features
- Custom Branding: Rebrand the web portal and mobile Aeps app with your own company name, logo, color themes, and domain.
- Admin Control Panel: Manage multi-level channel partners (super distributors, distributors, and retail agents), track transactions, and set Aeps commission structures from a single Aeps dashboard.
- Aadhaar & Biometric Authentication: Secure customer verification using Aadhaar numbers and fingerprint/iris scanners (supporting devices like Mantra) without needing passwords or OTPs.
- Essential Banking Services: Offer services like cash withdrawals, balance inquiries, mini statements, and Aadhaar Pay.
- Multi-Bank Routing & Auto Failover: Route transactions through multiple banking partners dynamically to maintain high success rates and prevent downtime.
- Real-Time Settlement & Reporting: Get instant or scheduled fund settlements (T+0 or T+1) alongside automated transaction reconciliation and live reports.
- Extended Fintech Integration: Easily bundle additional financial options like BBPS utility bill payments, micro-ATMs, and mobile recharges.
Benefits White Label AEPS Platform
A White Label AEPS (Aadhaar Enabled Payment System) Platform lets businesses offer biometric banking services like cash withdrawals, balance checks, and mini-statements under their own brand name, logo, and domain.
Key Benefits
- Own Branding & Identity: Customize Aeps portal, admin panel, and Aeps mobile app with your corporate brand, logo, and color scheme.
- Fast Market Entry: Launch your digital banking service in days using pre-built, tested Aeps earning software instead of developing technology from scratch.
- Cost-Efficient: Eliminate heavy upfront Aeps software development cost, infrastructure overhead, and complex regulatory setup.
- Multiple Revenue Streams: Earn steady commission margins on every transaction processed by your agent, distributor, or retailer network.
- Complete Admin Control: Manage multi-level agent hierarchies, set customized commission slabs, and monitor transaction health from a single dashboard.
- Financial Inclusion: Empower local retail shops in rural and semi-urban areas to function as micro-ATMs, serving underserved communities.
- Bundled Services: Easily integrate Aeps complementary financial tools like Bharat Bill Payment System Software, mobile recharges, and money transfer Software (DMT).
White Label AEPS Platform Development
Launching White Label AEPS platform lets you offer biometric banking services like cash withdrawals, balance inquiries, and mini-statements under your own brand name without building complex banking infrastructure from scratch.
1. Choose a White Label Technology Provider
- Select an authorized Aeps india that holds robust NPCI (National Payments Corporation of India) compliance and secure banking APIs.
- Verify that Aeps india offer multi-bank routing, high uptime guarantees (99.99%), and built-in security features like ISO compliance.
2. Sign Agreement and Complete Business KYC
- Sign the legal service agreement and contract with your chosen Aeps india.
- Submit company registration documents, GST certificates, PAN card, and Director/Owner KYC details as mandated by regulatory guidelines.
3. Brand Customization & Portal Setup
- Provide your brand assets, including your company logo, preferred color themes, splash screens, and favicon.
- Map your custom domain or subdomain (e.g.,
://yourdomain.com) to the Aeps india server infrastructure. - Configure your Android or iOS mobile applications with your unique Aeps service app name and branding.
4. Configure Services and Commission Slabs
- Select your core banking utilities: AePS (cash withdrawal, balance check, mini statement) and Value-Added Services like BBPS (bill payments), DMT (money transfer), and Micro ATM integration.
- Set up multi-level user hierarchies (Admin → Super Distributor → Distributor → Retailer).
- Define custom commission and surcharge structures for every transaction tier.
5. Sandbox Testing
- Test all user flows using the Aeps india sandbox/test environment.
- Run test biometric scans, mock cash withdrawals, and ledger/wallet updates to ensure error-free communication between the front-end Aeps service portal and Aeps banking APIs.
6. Go Live and Build Your Network
- Launch your production-ready web portal and mobile application on the live network.
- Aeps Onboard merchants, agents, and retailers by completing their individual e-KYC directly through your branded Aeps admin dashboard to start processing live transactions.
How to Launch Your Own White Label AEPS Platform
Launching a white-label Aadhaar Enabled Payment System (AEPS) platform requires partnering with a Aeps india to deploy a pre-built, custom-branded portal without building the core banking architecture from scratch.
1. Choose a Reliable White-Label Provider
- Select a technology partner: Find an experienced Aeps india that provides ready-to-deploy banking rails.
- Verify compliance: Ensure the Aeps india offers bank-grade security, data encryption, and compliance with National Payments Corporation of India (NPCI) guidelines.
2. Customize the Platform Under Your Brand
- Apply branding elements: Integrate your company name, logo, custom color schemes, and domain URL into the web portal and mobile application.
- Set up role-based panels: Get dedicated administrative controls, multi-level distributor channels, and retailer/agent login modules.
3. Activate Core and Value-Added Services
- Configure essential banking APIs: Enable Aadhaar biometric authentication for cash withdrawals, balance inquiries, and mini statements.
- Bundle extra utilities: Add secondary financial services like best BBPS, and mobile recharges to increase Aeps payment platform utility.
4. Configure Commercials and Commissions
- Define commission structures: Set real-time automated commission slabs and markup margins for your distributors and merchants.
- Establish wallet management: Integrate a main administrative wallet to oversee fund flows, instant transaction settlements, and ledger ledgers.
5. Build Your Distribution Network
- Onboard agents and merchants: Recruit local shop owners, micro-entrepreneurs, and regional distributors to utilize your branded AEPS service application.
- Complete merchant KYC: Ensure every onboarded agent finishes mandatory identity verification and biometric device registration before processing live transactions.
White Label AEPS Platform Cost in India
A white-label AePS (Aadhaar Enabled Payment System) platform lets you launch a branded micro-banking portal with initial Aeps setup costs ranging from ₹10,000 to ₹1,20,000+, plus ongoing operational fees.
Cost Breakdown by Scale
| 📌 Model Type | 🗓️ Initial Setup Cost | 🗓️ Annual AMC | 💡 Best Suited For |
|---|---|---|---|
| Basic White-Label | ₹10,000 – ₹35,000 | ₹5,000 – ₹10,000 | Small startups & new resellers |
| Standard B2B Admin | ₹35,000 – ₹1,20,000 | ₹10,000 – ₹20,000 | Growing fintechs with merchant networks |
| Custom Bank API | ₹2,50,000 – ₹4,50,000+ | ₹30,000 – ₹50,000+ | Large enterprises |
Ongoing & Transactional Expenses
- Transaction Fees: ₹3 to ₹5 per cash withdrawal/balance check, or a percentage commission share (0.5% – 1%).
- Server & SSL Hosting: ₹2,000 – ₹5,000 monthly if not bundled in the AMC.
- KYC / Verification Setup: Nominal per-merchant KYC verification charges (e.g., via DigiLocker or face-auth APIs).
Hidden Costs & Considerations
- GST: Extra 18% GST applies to Aeps software setup and AMC invoices.
- Device RD Services: Aeps Biometric scanners (Mantra) require annual Morpho/Mantra RD service renewals per device (~₹375/year per device).
- Working Capital / Pre-funding: You need a security deposit or operational float wallet with Aeps india for instant settlements.
White Label AEPS Platform Wallet Management
A White Label AEPS Platform provides ready-made digital banking infrastructure allowing businesses to offer Aadhaar-enabled biometric payment services under their own brand.
Wallet Management Core Architecture
- Multi-Tier Ledger: Tracks funds across Admin, Master Distributors, Distributors, and Retailers.
- Real-Time Settlement: Automatically credits agent wallets upon successful AEPS cash withdrawal or balance inquiries.
- Fund Loading & Transfer: Enables manual/auto bank top-ups and peer-to-peer Aeps wallet transfers down the hierarchy.
- Commission Engine: Instantaneous calculation and split of markup or slab-based commissions.
Operational Workflow & Control
- Fund Flow: Admin loads the main pool account via virtual accounts/IMPS; downline distributors allocate limits to retailers.
- Auto-Reconciliation: Matches NPCI/bank responses to prevent hanging transactions or ledger discrepancies.
- Security & Limits: Enforces daily transaction caps, multi-factor authentication (MFA), and role-based access control (RBAC).
Risk & Compliance Considerations
- Liquidity Management: Maintaining adequate float in main payout/AEPS settlement accounts to prevent transaction failures.
- Regulatory Audits: Ensuring adherence to RBI guidelines on prepaid payment instruments (PPI) and escrow account monitoring.
White Label AEPS Commission Management
White Label AEPS Commission Management allows platform owners to configure, control, and automate multi-tier payout structures for cash withdrawals, balance inquiries, and mini-statements under their own brand.
Core Administrative Features
- Unified Ledgers: Track individual earnings, distributor overrides, and platform margins transparently.
- Automated Reconciliation: Generate GST-compliant invoices and daily sales reports without manual intervention.
- Dispute Management: Handle failed transaction chargebacks and commission reversals cleanly via admin overrides.
- Custom Slabs: Assign customized commission groups to high-performing agents to drive network engagement.
White Label AEPS Platform With API Integration
A White Label AEPS (Aadhaar Enabled Payment System) Platform with Aeps API Integrating allows fintech startups, B2B aggregators, and business networks to launch their own branded digital banking portal. Instead of building complex financial infrastructure from scratch, you license a pre-built best Aeps platform, apply your own brand name, logo, and domain, and embed secure Aeps API to turn local retail shops into functional mini-ATMs.
Integration & Compliance Steps
To launch Aeps platform legally and securely in India, the technical and business onboarding spans four main phases:
- KYC & Corporate Verification: You must submit legal business documentation (PAN, GST registration, corporate bank accounts, and promoter Aadhaar) to sign the vendor and banking agreement.
- API Integration: Developers embed the Aeps documentation SDKs into your app/website. This phase demands security implementations like SSL pinning and IP whitelisting. Note: Storing raw biometric data or Aadhaar numbers locally is strictly prohibited by UIDAI regulations.
- Biometric Hardware Mapping: Integration of UIDAI-certified Aeps fingerprint or Aeps iris scanners (such as Mantra, devices) to securely capture biometric strings on the agent interface.
- Go-Live & Onboarding: Whitelabeling templates (your color scheme, logo) are deployed, allowing you to begin onboarding agents via your custom Aeps admin portal.
White Label AEPS Platform for Admin Panel
A White Label AEPS Platform with an Admin Panel is a ready-made, brandable Aeps solution that lets you launch your own Aadhaar Enabled Payment System business without building Aeps payment software from scratch.
Key Admin Panel Features
- Commission Engine: Set flexible, tiered commission margins for distributors and retailers.
- Wallet Management: Add funds, track ledger balances, and process automated bank settlements.
- Real-Time Reports: View detailed analytical logs for success/failure rates, fast Aeps API uptimes, and audit trails.
White Label AEPS Platform Branding & Customization
A white-label AEPS platform lets businesses launch custom-branded Aadhaar-based banking services without building infrastructure from scratch.
Key Branding & Customization Features
- Custom Domain & Logo: Run the web portal and mobile app under your own company name, brand identity, and custom domain.
- Admin & Merchant Dashboards: Manage sub-distributors, create retailer networks, and monitor live transactions via a branded control panel.
- Branded Notifications: Send client receipts, SMS updates, and email notifications styled with your corporate identity.
- Commission Management: Set up custom commission structures and payout hierarchies for your agent network.
White Label AEPS Platform Security
White label AEPS (Aadhaar Enabled Payment System) platform security relies on UIDAI-compliant biometric authentication, bank-grade end-to-end encryption, and NPCI regulatory standards.
Core Security Features
- Biometric Verification: Transactions require live Aeps fingerprint or iris scans verified directly through UIDAI servers, eliminating traditional card skimming or PIN theft.
- End-to-End Encryption: Data packets containing sensitive customer information and biometric templates are encrypted from the terminal device to the host banking server.
- Multi-Factor Authentication (MFA): Admin panels, retailer logins, and transaction approvals use secondary verification layers, such as OTP or device binding.
- AI-Powered Fraud Detection: Modern Aeps platform monitor transaction behavior in real time to flag suspicious patterns, cloning attempts, or anomalous velocity.
- NPCI & Regulatory Compliance: top Aeps System adhere strictly to guidelines set by the National Payments Corporation of India (NPCI) and the Reserve Bank of India (RBI).
Essential Safety Protocols for Operators
- Role-Based Access Control (RBAC): Restrict administrative privileges in your white label Aeps portal so that staff or sub-distributors only access data necessary for their roles.
- Device Whitelisting: Allow Aeps biometric scanner devices (such as certified Mantra scanners) only when properly registered and paired with authorized agent profiles.
- Secure Audit Trails: Maintain unalterable Aeps b2b system logs for every cash withdrawal, balance check, and fund transfer to simplify compliance tracking and fraud investigations.
White Label AEPS Platform Transaction Management
A White Label AEPS platform transaction management system allows you to oversee, track, and settle Aadhaar-based biometric transactions under your own brand identity for around ₹7,200 to ₹44,000 for setup.
Core Transaction Management Features
- Real-Time Monitoring: Track cash withdrawals, balance checks, and mini-statements instantly.
- Auto-Settlement: Direct movement of funds to merchant or master distributor accounts.
- Dispute & Refund Handling: Automated logging and reversal workflows for failed transactions.
- Commission Engine: Real-time margin distribution across retailers, distributors, and admins.
- Audit Trails: Comprehensive government-compliant transaction logs and biometric data encryption.
Management Workflow Phases
Phase 1: Initiation
- Customer inputs Aadhaar and selects bank.
- Biometric fingerprint capture.
Phase 2: Authorization
- Routing via NPCI Gateway to UIDAI.
- Instant status response (Success/Fail).
Phase 3: Settlement
- Ledger update and commission split.
- Instant SMS/WhatsApp notification to end-user.
White Label AEPS Settlement & Reconciliation
White label Aadhaar Enabled Payment System (AePS) settlement and reconciliation manages the automated movement, matching, and payout of cash-withdrawal or deposit funds from NPCI/bank switches to your branded Aeps platform merchant wallets.
Settlement Workflows & Timelines
- Instant Settlement: Cash withdrawal amounts reflect in the retailer/merchant wallet immediately after biometric authentication.
- T+1 / End-of-Day Payout: Master pool account funds settle to the white label Aeps Software designated corporate bank account via IMPS/NEFT/RTGS.
- Pending/Failed Reversals: Auto-reversals trigger within 24–48 hours for dropped transactions or timeout errors at the UIDAI/Bank switch level.
Automated Reconciliation Process
- Log Matching: Compares low cost Aeps API request logs with host response data (NPCI/Bank) to confirm transaction success or failure.
- Dispute Management: Tracks chargebacks, double-debit complaints, and explicit mismatch logs on the admin dashboard.
- Ledger Auto-Posting: Generates balanced general ledger (GL) entries and commission distributions per distributor/retailer slab.
Best Practices for Platform Owners
- Multi-Bank Routing: Configure auto-failover across backup best Aeps banking API to minimize transaction drops during peak hours.
- Ledger Audits: Run daily automated script matching between switch settlement reports and internal wallet balances.
- Buffer Capital: Maintain sufficient liquidity in master virtual accounts (VAN) to handle instant holiday or weekend payouts.
White Label AEPS Platform Compliance & Regulatory Considerations
Launching a white-label Aadhaar Enabled Payment System (AePS) platform in India requires strict adherence to mandates from the Reserve Bank of India (RBI), National Payments Corporation of India (NPCI), and the Unique Identification Authority of India (UIDAI).
The compliance landscape features updated risk frameworks focusing on agent accountability and data security.
Key Compliance & Regulatory Requirements
RBI Framework for AePS Operators (ATO)
- Mandatory KYC: Complete and continuous verification for all last-mile agents and operators.
- Bona Fide Use: Restrict Aeps system API exclusively to authorized AePS transactions, blocking unauthorized or ancillary services.
- Real-Time Monitoring: Implement tracking mechanisms to detect abnormal transaction behaviors or fraud flags at the operator level.
NPCI & UIDAI Security Protocols
- Biometric Certification: Use strictly STQC-certified and L1/L2 compliant Aeps biometric fingerprint or Aeps iris scanner device.
- Data Masking: Prohibit storing raw Aadhaar numbers or biometric templates locally in server logs or databases.
- End-to-End Encryption: Enforce multi-layer encryption, secure SSL pinning, and server IP whitelisting for all high speed Aeps API callback.
Operational & Business Constraints
- One Operator, One Bank: Align agent onboarding configurations with current network restrictions limiting multi-mapping abuse.
- Partner Liability: Aeps india carry indirect legal liability under the Payment and Settlement Systems (PSS) Act, 2007, for sub-merchant misbehavior.
- Audit Trails: Maintain comprehensive, unalterable transaction logs for all cash withdrawals, balance inquiries, and mini-statements.
White Label AEPS Biometric Device Integration
White label AEPS biometric device integration connects a custom-branded financial portal or app to AEPS API Service using STQC-Aeps certified hardware for secure, cardless Aadhaar authentication.
How Biometric Integration Works
- RD Service Installation: Download the Registered Device (RD) service application for your specific scanner brand from the Play Store or Aeps earning portal.
- Device Binding: Link the scanner’s unique serial number to your host Android app or Windows PC software.
- PID Block Generation: Capture the customer’s fingerprint or iris scan, which the local RD service instantly encrypts into a secure PID (Personal Identification) block.
- API Routing: Transmit the tokenized, encrypted payload through instant AEPS API Integration gateway to central NPCI and UIDAI switches for bank authorization.
Supported Hardware & Requirements
- Approved Scanners: UIDAI-compliant devices like the Mantra MFS100, Mantra MFS110 (L1 certified devices are recommended).
- Host Platform: An Android smartphone/tablet (connected via OTG) or a Windows PC.
- Connectivity: A stable internet connection to ensure real-time UIDAI validation and instant transaction processing.
White Label AEPS Platform vs Custom AEPS Platform
A white-label AEPS platform is a pre-built, ready-to-deploy Aadhaar Enabled Payment System software that you rebrand with your own company logo, colors, and domain, while a custom AEPS platform is built from scratch entirely according to your specific technical and business needs.
White-Label AEPS Platform
- Speed to Market: Launches quickly, often within days or weeks, because the core infrastructure and banking Aeps API are already built.
- Cost-Effective: Requires a much lower initial investment since development costs are shared across multiple clients using the same software provider.
- Maintenance: Handled entirely by the Aeps india, including cloud hosting, bug fixes, and security patches.
- Limited Control: Customization is restricted to visual branding (logos, color schemes, themes) and predefined settings like commission slabs.
- Dependencies: Your platform relies heavily on the uptime, security, and policies of the Aeps india.
Custom AEPS Platform
- Full Ownership & Control: You own the source code and have total freedom over features, user interface design, workflows, and third-party integrations.
- Scalability & Flexibility: Built specifically to scale with your unique business model without being restricted by a vendor’s pre-packaged limitations.
- High Development Cost: Demands a heavy upfront budget for dedicated software developers, UI/UX designers, and compliance management.
- Longer Deployment Time: Takes months to design, code, test, and secure proper banking approved reliable Aeps API connection.
- Ongoing Maintenance: Requires an in-house or contracted technical team to manage continuous updates, server costs, and security audits.
White Label AEPS Platform vs AEPS Software
A White Label AEPS Platform is a complete, ready-to-deploy business ecosystem (including admin panels, distributor/retailer hierarchies, and Aeps wallet system) branded with your name, whereas trusted AEPS Software refers strictly to the underlying digital application or the specific Aadhaar Enabled Payment System API code required to process biometric Aadhaar transactions.
Platform vs. Software Comparison
| Feature | White Label AEPS Platform | AEPS Software / API |
|---|---|---|
| Definition | End-to-end business setup with branding, web/app portals, and multi-level management. | The core technical codebase or API used to execute Aadhaar authentication. |
| Target User | Fintech startups, enterprises, and master distributors launching a B2B brand. | Developers or companies embedding banking features into an existing app. |
| Control Panel | Includes a full Admin Dashboard to manage retailers, commissions, and ledgers. | Usually limited to backend transaction endpoints or basic integration tools. |
| Setup Cost | Higher (₹15,000 to ₹1,20,000 for pre-branded portals). | Lower/Modular (₹7,500 to ₹35,000 for standard API setup). |
| Ready-to-Use | Yes; includes wallet, user onboarding, and real-time settlement tracking. | No; requires custom front-end development and hosting setup. |
White Label AEPS Platform
- Complete Ecosystem: Delivers ready-made web and mobile applications.
- Custom Branding: Features your logo, domain, and custom color scheme.
- Network Hierarchy: Lets you create unlimited distributors and retail agents.
- Financial Control: Automates commission distribution and real-time settlements.
AEPS Software / API
- Core Functionality: Provides raw endpoints for cash withdrawals and balance checks.
- Integration Flexibility: Designed to merge seamlessly into an existing software stack.
- Development Required: Demands external front-end design and database configuration.
- Lower Overhead: Eliminates extra features if you only need transaction routing.
Aeps india Only One of The White Label AEPS Platform Provider in India
Aeps india one of the right White Label AEPS Platform provider requires evaluating critical operational, security, and financial factors to ensure a reliable and profitable branded digital banking business.
Key Factors to Consider
- Security and Compliance: Ensure the Aeps india strictly follows NPCI guidelines and UIDAI Aadhaar compliance, featuring robust data encryption and secure biometric authentication.
- Transaction Success Rate and Uptime: Look for a high uptime (99%+) and reliable processing infrastructure to minimize transaction failures and reduce customer drop-offs.
- Commission and Pricing Structure: Compare per-transaction earnings, commission margins, settlement speeds, and check for any hidden setup or maintenance charges.
- Admin Panel and Network Management: A strong White Label AEPS Admin Software must offer smooth multi-level hierarchy controls to manage super distributors, distributors, and retail agents effortlessly.
- Customization Capabilities: Verify the depth of branding available, including your own company name, logos, color schemes, web portals, and mobile apps.
- Technical Support: Immediate and reliable technical assistance is vital for resolving stalled or failed transactions and system downtime.
- Service Diversification: Opt for platforms that bundle additional financial Aeps transaction API like BBPS service software, Mini ATM to boost daily revenue.
Why Choose AEPS India for White Label AEPS Platform?
Aeps india is an White Label AEPS Platform provider lets businesses launch fully branded digital banking services instantly without building complex core technology from scratch.
Key Benefits of a White Label AEPS Provider
- High Success Rate & Uptime: Look for 99%+ uptime reliability to minimize transaction failures and maintain user trust.
- Complete Brand Ownership: Customize Aeps platform admin panel, mobile Aeps apps, domain, and receipts with your own company name, logo, and color theme.
- Fast Market Entry: Deploy a ready made Aeps platform in days or weeks instead of spending months or years on best Aeps software development.
- Security & Compliance: Ensure adherence to UIDAI and NPCI guidelines with secure end-to-end encryption.
- Fast Settlements: Check for automated real-time or T+0/T+1 payout settlements to keep retailer cash flow healthy.
- Low Cost Efficiency: Avoid heavy upfront capital investments in server infrastructure, technical engineering teams, and regulatory maintenance.
- New Revenue Streams: Earn recurring commission income on every successful transaction like cash withdrawals, balance inquiries, and mini statements.
- Technical Focus: Let the Aeps india manage backend server uptime, security patches, and NPCI/RBI regulatory compliance while you focus on marketing and agent networks.
- Comprehensive Admin Control: Monitor transactions, manage distributor-retailer hierarchies, and configure custom commission slabs from a unified dashboard.
Conclusion
A White Label AEPS Platform can help fintech businesses, payment companies, distributors, and digital service providers launch AEPS services under their own brand. Instead of developing every component from the beginning, a white-label platform can provide the core high volume Aeps software, user management, transaction features, branding options, and AEPS integration needed to operate the service.
The right platform should offer more than a branded website or application. Important features can include an AEPS Admin Panel, retailer and distributor management, reputed AEPS API integration, Aeps wallet management, commission management, transaction tracking, reports, service controls, user roles, notifications, and business monitoring. The exact features available will depend on the high volume Aeps platform and its Aeps india.
A White Label AEPS Platform is a ready-made, customizable Aeps software solution that lets you launch your own branded Aadhaar Enabled Payment System (AEPS) business.
The cost of a White Label AEPS Platform can also vary from one business to another. Pricing may depend on factors such as the required AEPS services, web and Android applications, branding, Aeps Balance Enquiry API or banking integration, Aeps admin features, retailer hierarchy, customization, support, security requirements, and additional financial services. Therefore, businesses should compare the complete solution rather than looking only at the initial Aeps software price.
For businesses planning to build their own AEPS network, a white label Aeps model can also provide a practical way to manage retailers, distributors, transactions, commissions, wallets, and reports from a centralized system. It can be useful for businesses that want to expand their digital financial services while maintaining their own brand identity.
At Aeps India, businesses can explore a White Label AEPS Platform based on their business model and operational requirements. The solution can be planned around the required top AEPS services, branding, user hierarchy, high volume Aeps API connectivity, transaction management, and other digital financial services that the business wants to provide.
Before selecting a white-label platform, check the AEPS integration, supported services, retailer onboarding process, transaction workflow, wallet and Aeps commission system, admin controls, reporting, security, customization options, technical support, and total cost. These factors can make a significant difference when the platform grows from a small retailer network into a larger digital financial services business.
If you want to start an AEPS business under your own brand, contact Aeps India to discuss your White Label AEPS Platform requirements, available features, integration options, customization, setup process, and pricing.
Build your branded AEPS business with a platform designed around your business requirements.
Frequently Asked Questions About White Label AEPS Platform
A White Label AEPS Platform is a ready-to-use AEPS solution that businesses can launch under their own brand. It can include a branded website, admin panel, retailer and distributor management, AEPS integration, wallet, commission and transaction management.
The Aeps india configures the AEPS platform according to the business requirements and connects the required trusted AEPS services. The business can then manage its Aeps business platform, onboard retailers or distributors, process supported AEPS transactions and monitor operations from the admin panel.
Depending on the provider, a White Label AEPS Service Platform can include a branded Aeps portal, custom domain, admin panel, retailer and distributor management, wallet management, commission management, AEPS API integration, biometric-device support, transaction reports, settlement management and mobile app support.
The cost depends on features, branding, API integration, mobile app, customization, hosting, maintenance, biometric requirements, transaction charges and support. Businesses should compare the complete setup and recurring costs before selecting a platform.
Yes. A White Label AEPS Platform allows eligible businesses to offer supported AEPS services using their own business name, branding and other configurable platform elements, subject to the applicable provider and service arrangements.
Yes, own-domain branding can be supported in a White Label AEPS Platform. The exact domain setup, SSL, hosting and DNS requirements depend on the platform provider and selected configuration.
Yes, a complete White Label AEPS Platform can include an admin panel for managing users, retailers, distributors, wallets, commissions, transactions, settlements, reports, services and other platform settings.
Yes. The platform can support retailer and distributor onboarding and management. Depending on the configuration, administrators can manage user profiles, IDs, wallets, commissions, transactions and reports.
Yes. A White Label AEPS Platform can support multiple user levels such as admin, master distributor, distributor and retailer. The available hierarchy and controls depend on the platform configuration.
AEPS API integration may be included or offered as part of the platform, depending on the Aeps india. The API can connect supported AEPS services with the website, application or backend system.
Yes, supported AEPS transaction flows can work with compatible biometric devices. Device compatibility, authentication requirements and supported device models depend on the AEPS service and integration arrangement.
RD Service, or Registered Device Service, allows a supported registered biometric device to communicate with the application during biometric authentication. The required RD Service depends on the device and AEPS implementation.
A White Label AEPS solution may include a branded mobile application, depending on the selected package. Businesses should confirm whether Android or other app support, branding, publishing and maintenance are included.
Yes. Depending on the Aeps india, businesses can customize elements such as logo, domain, colors, branding, website content, user interface and selected platform features. Advanced customization may involve additional charges.
The platform can calculate commissions according to configured commission slabs or business rules. Commissions can be assigned to applicable retailers, distributors and other user levels, with transaction-wise records and reports where supported.
Wallet management allows users to maintain and monitor their available platform balance. Depending on the configuration, administrators can manage fund allocation, wallet credits and debits, transaction history, ledger records and related reports.
The launch time depends on branding, domain configuration, API and service activation, documentation, customization, testing and onboarding requirements. A ready-made platform can generally reduce development time compared with building the complete system from scratch.
Yes. Startups can use a White Label AEPS Platform to launch supported AEPS services without developing every platform component independently. The solution can be scaled according to the startup’s user network and business requirements.
White Label AEPS and custom development serve different requirements. White Label can reduce development effort and speed up deployment, while custom development can provide greater control over functionality and architecture. The suitable option depends on the business’s budget, timeline and customization requirements.
Yes. AEPS India provides White Label AEPS Platform solutions for businesses looking to launch supported AEPS services under their own brand. Available features, integrations, customization, pricing and onboarding requirements should be confirmed according to the business’s specific requirements.
AEPS Debit Facility: What It Means, Why It Is Disabled & How to Enable It
Trusted AEPS Software Provider Company in India – Full Business Guide 2026
Best AEPS Admin Panel for Startups and Fintech Companies
About Author

