Micro ATM: What Is It, How It Works, Benefits & Services
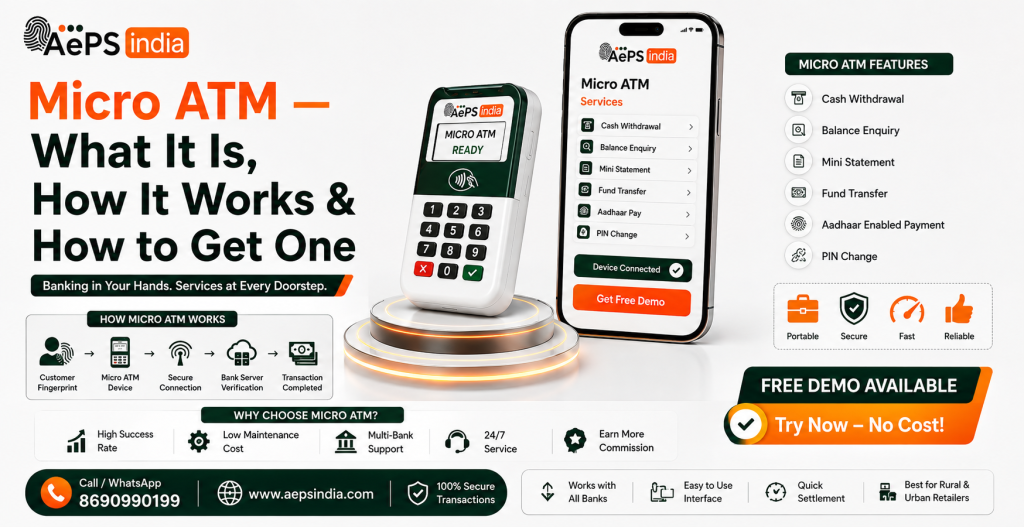
Are you looking for a reliable Micro ATM solution to offer convenient banking and cash withdrawal services to customers through your business? A Micro ATM is a compact banking device used through an authorized banking and payment ecosystem to help customers perform supported transactions using debit cards or Aadhaar-based authentication, depending on the device, service arrangement, and available network.
For retailers, fintech businesses, Business Correspondents, distributors, and digital service providers, a Micro ATM can help bring supported banking services closer to customers who may not always have easy access to a traditional bank branch or ATM. Instead of investing in a large physical banking setup, businesses can use a portable Micro ATM machine as part of an authorized digital banking service model.
A micro ATM is a portable, handheld card-swipe device used by local shop owners and banking agents (Business Correspondents) to function as a mobile mini-bank. It connects via mobile data to let customers withdraw cash and check account balances using a debit card and PIN, or via biometric Aeps fingerprint scanning through Aadhaar (AePS).
With a suitable Micro ATM solution, supported services may include cash withdrawal, balance enquiry, mini statement, debit card transactions, and Aadhaar-enabled services, depending on the connected bank, payment network, device, and authorized service provider. This makes Micro ATM technology useful for businesses that want to expand their digital financial service offerings.
AEPS India provides Micro ATM solutions for businesses looking to build or expand their digital banking and assisted payment services. The right solution can be combined with a business workflow that includes retailer onboarding, transaction monitoring, settlement support, and centralized management according to the selected service model.
Before choosing a Micro ATM provider in India like Aeps india, it is important to evaluate device compatibility, supported transaction services, connectivity, security features, onboarding requirements, transaction reporting, technical support, commercial terms, and the applicable banking or payment network requirements. Aeps india should fit your actual business model rather than simply offering a device.
Whether you are planning to start Micro ATM business, add Micro ATM services to an existing retail outlet, build a digital banking network, or expand your fintech service portfolio, AEPS India can help you explore a suitable Micro ATM solution based on your business requirements.
In this complete guide, you will learn what a Micro ATM is, how it works, its key features, supported services, benefits for retailers and businesses, device and integration requirements, business setup process, cost factors, and how to choose the right Micro ATM solution in India.
What Is a Micro ATM?
A micro ATM is a pocket-sized, portable card-swipe machine used by authorized banking agents or local shopkeepers to deliver basic banking services. It connects to a mobile network to let people withdraw cash or check account balances using a debit card and PIN, acting as a mobile bank branch.
How Does a Micro ATM Work?
A Micro ATM is a small, portable card-swipe device operated by a bank agent or local shopkeeper (Business Correspondent). It connects to the bank via mobile data to let people in local areas do basic banking like cash withdrawals and balance checks without visiting a bank branch.
How the Process Works
- Card Insertion: The customer puts their debit card into the Micro ATM machine.
- PIN Entry: The user types their secret PIN on the keypad to confirm who they are.
- Bank Check: The machine sends the details safely through the internet to the central bank server.
- Cash Handover: Once the bank approves, the shop owner gives physical cash from their cash box to the customer.
- Digital Transfer: The money amount moves electronically from the customer’s bank account to the shop owner’s account.
- Receipt: A paper slip or text message confirmation prints out for the user.
What Is a Micro ATM Machine?
A micro ATM machine is a portable, handheld point-of-sale (POS) terminal used by bank-appointed Business Correspondents (BCs) to deliver basic banking services in remote or unbanked areas.
What Services Does a Micro ATM Provide?
A micro ATM is a portable, handheld device operated by a banking agent or merchant to deliver essential financial services. It bridges the gap in remote or unbanked regions by connecting directly to bank networks via mobile data to process real-time transactions using debit cards or biometric verification.
Core Banking Services
- Cash Withdrawals: Get cash instantly using a domestic debit card and PIN or via Aadhaar biometric authentication.
- Cash Deposits: Deposit money directly into a linked bank account through an authorized agent.
- Balance Inquiries: Check the current available balance in a bank account.
- Mini Statements: View or print a brief record of recent transactions.
- Fund Transfers: Send money safely between bank accounts or Aadhaar-linked IDs.
Which Cards Can Be Used at a Micro ATM?
Micro ATMs accept almost all domestic bank-issued debit cards and ATM-cum-debit cards connected to major card networks like RuPay, Visa, and Mastercard, as well as regional or cooperative bank cards.
Supported Card Networks
- RuPay: Widely used domestic card network in India, fully compatible with all micro ATM devices.
- Visa: Standard international and domestic debit cards issued by various partner banks.
- Mastercard: Globally recognized debit cards issued across multiple financial institutions.
- Regional Bank Cards: Local cooperative and rural bank debit cards linked to national switching networks.
Important Details
- PIN Requirement: You must use your confidential 4-digit or 6-digit ATM PIN to authorize card transactions on a micro ATM terminal.
- Alternative Authentication: Micro ATMs also support biometric authentication via an attached scanner using an Aadhaar card number, meaning physical plastic cards are not strictly required if you use an best AEPS transaction mode.
- Credit Cards: Traditional credit cards generally do not work for standard cash withdrawals at micro ATMs, as these terminals are meant for direct bank account access through debit or prepaid instruments.
Key Things to remember about Micro ATM
A Micro ATM is a portable, handheld terminal used by authorized banking agents or shopkeepers to deliver basic financial services like cash withdrawals, balance checks, and mini-statements without needing a traditional bank branch.
Benefits & Uses
- Financial Inclusion: Brings banking directly to remote, rural, or unbanked populations where full-scale bank branches are unavailable.
- Merchant Earnings: Gives local shopkeepers an extra stream of income through small commissions on each completed transaction.
- Low Setup Cost: Eliminates heavy infrastructure needs like secure walk-in rooms, heavy air conditioning, or constant physical security.
Facilities Available at Micro ATM
A micro ATM is a portable, handheld card-swipe device used by authorized bank agents or business correspondents (BCs) to deliver essential banking services directly to customers, bridging the gap where traditional Micro ATM are unavailable.
Authentication & Identity Services
- Aadhaar-Enabled Payment System (AEPS): Perform transactions using your Aadhaar number paired with biometric fingerprint authentication instead of a physical card or PIN.
- e-KYC Verification: Complete digital identity checks and customer verification processes for bank account openings.
Documents Required for Micro ATM Registration
To apply for a Micro ATM (mATM) dealership or merchant device as an agent/retailer in India, you need basic KYC and business verification documents, including a PAN card, Aadhaar card, active bank account details, and passport-size photographs.
Identity and Address Proof
- PAN Card: Mandatory for financial tracking and identity verification.
- Aadhaar Card: Used for e-KYC and identity confirmation.
- Alternative Address Proof: Voter ID card, passport, or driving license.
Business and Financial Proof
- Passport-Size Photographs: Recent color photos of the applicant.
- Bank Account Proof: Cancelled cheque, copy of passbook, or a recent bank statement for settlement of daily transactions and commissions.
- Shop/Business Address Proof: Electricity bill, telephone bill, or rent agreement for your storefront or kiosk.
List of Supported Banks
Micro ATMs in India are fully interoperable via National Payments Corporation of India (NPCI) networks, meaning they support debit cards (RuPay, Visa, Master) from almost all major public sector, private sector, and payments banks across the country.
Public Sector Banks
- State Bank of India (SBI)
- Punjab National Bank (PNB)
- Bank of Baroda
- Canara Bank
- Union Bank of India
- Bank of India
- Central Bank of India
- Indian Bank
- UCO Bank
- Bank of Maharashtra
Private Sector Banks
- HDFC Bank
- ICICI Bank
- Axis Bank
- Kotak Mahindra Bank
- Yes Bank
- IndusInd Bank
- IDFC First Bank
Payments & Regional Banks
- Fino Payments Bank
- NSDL Payments Bank
- RBL Bank
- Utkarsh Small Finance Bank
- Regional rural and cooperative banks tied up with major switch networks.
Who Can Become a Micro ATM Merchant or Agent?
A micro ATM is operated by an authorized Business Correspondent (BC) or banking agent such as a local shopkeeper, pharmacy owner, or village entrepreneur and can be used by any customer holding a valid domestic bank debit card and PIN to perform basic financial transactions.
Who Can Operate a Micro ATM (As an Agent)
- Local Merchants & Shop Owners: Individuals running small businesses like grocery stores (kirana shops), medical stores, or recharge outlets.
- Registered BCs: Indian citizens aged 18 or older who are formally appointed by scheduled commercial banks or authorized fintech service providers.
- Community Workers: Village-level entrepreneurs, local coordinators, and members of women’s self-help groups.
Who Can Use a Micro ATM (As a Customer)
- Any account holder of a major public sector, private sector, or regional rural bank in India.
- Customers who possess a valid debit card (Visa, RuPay, or Mastercard) and their secret PIN.
- Individuals looking to perform transactions like cash withdrawals, balance inquiries, or mini-statements in semi-urban and rural areas.
Why Use Micro ATM
A micro ATM is a portable, handheld card-swipe device operated by local business agents or shopkeepers. People use micro ATMs to perform basic banking services like cash withdrawals, balance checks, and mini statements without needing to travel far to find a traditional bank branch or standard ATM.
Key Benefits for Users
- Easy Access: Brings banking to rural, remote, or semi-urban areas where standard Micro ATM are rare.
- Biometric Security: Supports Aadhaar Enabled Payment System (AePS) transactions using fingerprint verification.
- Interoperable: Works with debit cards from most major banks.
Benefits for Small Businesses and Agents
- Low Setup Cost: Requires only a small pocket-sized device, mobile internet, and no heavy infrastructure.
- Extra Income: Local shopkeepers can earn commission fees on every cash transaction they process for customers.
- More Foot Traffic: Turning a local shop into a mini-banking hub attracts more daily visitors.
What Is Required to Use a Micro ATM?
To use or operate a micro ATM, specific requirements are divided between what the customer needs to make a transaction and what the merchant/operator needs to set up the service.
Customer Requirements
To withdraw cash or check your balance using a micro ATM operated by a banking agent:
- Valid Bank Card: A domestic debit, credit, or RuPay/Visa/Mastercard card.
- PIN or Biometrics: Your secret ATM PIN or Aadhaar-linked fingerprint verification for authentication.
- Active Account: A functional bank account with sufficient balance.
Merchant & Operator Requirements
If you want to set up and run a micro ATM point (such as at a local retail or kirana store):
- Micro ATM Device: A portable, NPCI-certified card-swiper/biometric handheld terminal.
- Internet Connectivity: Active mobile data or GPRS connection via the device or a paired smartphone.
- Bank Partnership: Registration as an authorized Business Correspondent (BC) or partnership with a financial service provider.
- KYC Documentation: Proof of identity and address, such as an Aadhaar card and PAN card.
- Cash Float: Physical cash in the shop’s till or cash drawer to hand over to customers during withdrawals.
Key Aspects of Micro ATM
A micro ATM is a compact, portable handheld device operated by local banking agents or merchants to deliver basic financial services to remote or underserved areas without needing a traditional Micro ATM infrastructure.
Core Features
- Portability: Small, lightweight design that agents can easily carry anywhere.
- Biometric Verification: Fingerprint scanners allow safe identification using Aadhaar numbers (AePS).
- Card & Digital Support: Reads debit cards via swipe or chip and connects to central bank servers using mobile data (GPRS/4G).
- Built-in Printer: Generates instant paper receipts for completed transactions.
Major Advantages
- Low Cost: Eliminates heavy setup costs, rent, electricity, and security required for large traditional Micro ATMs.
- Financial Inclusion: Reaches rural and remote populations who live far from regular bank branches.
- Merchant Earnings: Local store owners earn extra commission income on every processed transaction.
Cash Withdrawal Process Using a Micro ATM
To withdraw cash using a micro ATM, visit an authorized local shop or banking correspondent. Provide your bank details and insert or swipe your debit card (or give your Aadhaar number), enter your PIN or use your fingerprint for verification, input the desired amount, and collect the physical cash from the operator.
Step-by-Step Withdrawal Process
- Visit an Agent: Go to a certified local merchant, retail shop, or banking correspondent who carries a handheld micro ATM device.
- Share Details: Tell the operator your bank name and present either your debit card or your Aadhaar number.
- Choose Transaction: Select the cash withdrawal option on the device interface.
- Verify Identity:
- Using a Debit Card: Insert or swipe your card in the terminal and type your secret 4-digit or 6-digit ATM PIN.
- Using Aadhaar (AePS): Place your finger on the attached biometric scanner for thumb impression verification.
- Enter Amount: Type the exact amount of cash you want to withdraw.
- Process and Collect Cash: The device connects to the bank server via a mobile network for instant approval. Once approved, the shopkeeper hands over the physical cash and gives you a printed or digital receipt.
Cash Withdrawal Process Using a Micro ATM
Simple and secure Micro ATM withdrawal process
Visit Agent
Micro ATM agent ke paas jayein.
Enter Details
Required banking details submit karein.
Authenticate
Biometric authentication complete karein.
Receive Cash
Successful verification ke baad cash receive karein.
Cash Withdrawal Request
Micro ATM for Banks, Fintechs and Retail Networks
A Micro ATM (mATM) is a portable, handheld, GPRS or cellular-connected terminal operated by a designated merchant or business correspondent. It bridges the financial inclusion gap by allowing customers to perform interoperable banking transactions such as cash withdrawals, balance inquiries, and mini-statements using standard debit cards or biometric Aadhaar authentication via the NPCI network.
Value for Traditional Banks
- Expanded Footprint: Extends banking reach into remote rural and semi-urban areas without the heavy capital expenditure of brick-and-mortar branches.
- Reduced Infrastructure Cost: Replaces expensive, high-maintenance standalone ATM kiosks that require continuous air conditioning and heavy security.
- Relief for Crowded Branches: Offloads routine balance checks and low-value cash dispenses from physical bank counters to field agents.
Value for Fintechs
- Hyperlocal Aggregation: Enables fintech platforms to rapidly build scalable agency-banking networks using local kirana store owners as touchpoints.
- New Revenue Streams: Generates transaction-based fee and commission income on every card swipe or biometric authentication.
- Ecosystem Stickiness: Integrates cash-in/cash-out services with digital wallets, driving deeper customer engagement and cross-selling opportunities.
Value for Retail Networks
- Increased Footfall: Attracts neighborhood residents looking for accessible cash services directly into local convenience shops or pharmacies.
- Cash Management: Helps retail merchants efficiently cycle and liquidate excess daily cash collections by paying out cash withdrawals to customers.
- Cross-Selling Potential: Turns transactional visitors into retail buyers who purchase store goods during their cash-access visits.
Micro ATM Device
SECURE BANKING
Micro ATM for Rural and Semi-Urban Banking
Micro ATMs are small, portable, battery-powered card swipe and biometric machines operated by authorized local agents to deliver basic banking services in rural and semi-urban areas.
Key Benefits
- Financial Inclusion: “They bring banking services to unbanked and underbanked populations, promoting financial inclusion.
- Accessibility: Eliminates the need to travel long distances to nearby towns just to check balances or withdraw cash.
- Local Empowerment: Allows small kirana store owners and local retailers to function as mini-banks while earning a small commission on transactions.
- Cost-Effective: Much cheaper and easier for financial institutions to deploy in remote villages than full-scale, permanent ATM brick-and-mortar setups.
Rural Banking Micro ATM
Financial Inclusion for Semi-Urban Areas
| Account No. | Service | Amount | Time | Status |
|---|---|---|---|---|
| XXXXX4512 | Cash Withdrawal | ₹ 2,000 | 10:20 AM | Success |
| XXXXX8890 | Balance Inquiry | ₹ 0 | 11:15 AM | Success |
| XXXXX1123 | Cash Deposit | ₹ 5,000 | 12:05 PM | Pending |
| XXXXX6671 | Cash Withdrawal | ₹ 1,500 | 01:40 PM | Success |
Micro ATM Technology and Architecture
A Micro ATM (mATM) is a portable, handheld terminal operated by local shopkeepers or Business Correspondents (BCs) to deliver core banking services. Unlike traditional ATMs, it has no cash storage or internal dispenser; cash withdrawals are handed over physically from the agent’s cash drawer while accounts balance digitally in real time.
Core Technology Components
- Hardware: Handheld POS-style units equipped with a magnetic stripe/chip card reader, a physical keypad, a thermal receipt printer, and an interoperable biometric scanner.
- Biometric & Card Interface: Supports PIN-based debit/RuPay card entry or cardless Aadhaar-enabled biometric authentication (fingerprint scan).
- Connectivity Module: Utilizes cellular data (GPRS/3G/4G SIM cards), Wi-Fi, or Bluetooth tethering to a smartphone application to bridge field operations with banking servers.
- Software & Application Layer: Manages transaction workflows, end-to-end data encryption, instant digital receipt generation, and agent commission records.
System Architecture Flow
- Front-End Capture: The operator inputs transaction parameters while the customer swipes/inserts a card or provides fingerprint verification.
- Secure API Gateway: Encrypted transaction packets travel from the handheld terminal via mobile internet to the fintech or aggregator gateway.
- ATM Switch & Payment Network: The request passes through the bank’s ATM switch and national payment switches (such as NPCI or UIDAI for biometric matching).
- Core Banking Solution (CBS): The host bank validates account data, debits or credits funds instantly, and sends an authorization or decline response back to the terminal.
Micro ATM Architecture
Real-time Transaction & Network Monitoring
| Terminal ID | Auth Code | Transaction Type | API Response | Status |
|---|---|---|---|---|
| MATM-4401 | AUTH-9921 | Cash Withdrawal | 200 OK | Processed |
| MATM-8812 | AUTH-4410 | Balance Inquiry | 200 OK | Processed |
| MATM-2290 | AUTH-1102 | Cash Deposit | 503 Timeout | Retrying |
| MATM-3314 | AUTH-8841 | Mini Statement | 200 OK | Processed |
Micro ATM Device Features
A micro ATM is a pocket-sized, portable handheld terminal used by banking agents to deliver basic financial services like cash withdrawals, balance checks, and mini statements directly to customers. It acts as a mobile point-of-sale (POS) unit connecting to bank networks via cellular data without needing cash-dispensing vaults.
Hardware Features
- Compact & Portable: Lightweight, handheld design easy to carry for doorstep or rural banking.
- Card Reader: Integrated magnetic stripe, smart card, and EMV chip reader for debit or credit cards.
- Biometric Scanner: Built-in STQC-certified fingerprint or iris scanner for Aadhaar-based verification.
- Thermal Printer: On-board receipt printer for instant physical transaction slips.
- Secure PIN Pad: PCI-PED compliant physical or touchscreen keypad for safe PIN entry.
Functional Features
- Core Banking Services: Supports cash withdrawals, balance inquiries, fund transfers, and mini statements.
- Dual Authentication Modes: Accepts traditional Debit Card + PIN or cardless Aadhaar Enabled Payment System (AePS) biometric validation.
- Interoperability: Works across major national banking networks and card types (RuPay, Visa, Mastercard) via NPCI.
- Connectivity Options: Features 4G/3G GPRS and Wi-Fi capabilities for real-time core banking server connectivity.
Benefits of Using a Micro ATM for Cash Withdrawal
Micro ATMs serve as a critical bridge for financial inclusion, offering a portable, secure, and convenient alternative to traditional bank branches and large automated teller machines, particularly in rural and semi-urban areas. Operated by authorized business correspondents (BCs) or local merchants, these handheld point-of-sale (PoS) style devices process essential banking tasks by utilizing mobile data networks.
Benefits for Customers
- Proximity and Convenience: Eliminates long travel distances to city centers or massive bank queues by bringing banking right to your local grocery store.
- Biometric Authentication: Integrate AePS, allowing cash withdrawals using just a fingerprint or thumbprint verification without needing a physical debit card.
- Interoperable System: Allows you to access and withdraw funds seamlessly regardless of which bank holds your savings or current account.
- Human-Assisted Service: Provides a more personalized and comfortable transaction process for elderly or tech-averse users since a local agent operates the terminal.
- Instant Verification: Delivers real-time SMS alerts and immediate printed receipts for transaction tracking and security assurance.
- Zero or Low Fees: Avoids the heavy out-of-network operational fees frequently associated with traditional, commercial ATMs.
Benefits for Merchants and Agents
- Passive Revenue Streams: Earns shop owners a clear commission or transaction fee for every cash withdrawal processed on the machine.
- Increased Foot Traffic: Draws more community members to your establishment for banking needs, which naturally boosts sales for your core business items.
- Dual-Function Technology: Doubles as a standard merchant PoS system, meaning the exact same device can accept retail card payments for store goods.
- Low Upkeep and Overhead: Features zero or low maintenance costs compared to heavy retail terminal setups and requires no technical expertise to deploy.
Benefits for Banks and the Banking Ecosystem
- Highly Cost-Effective: Saves financial institutions major infrastructure investments in space rental, security guards, electricity, and hardware maintenance.
- Wider Geographical Reach: Enables rapid banking network expansion into deep rural, low-connectivity, and underserved pockets where standard internet cabling is absent.
- Streamlined Welfare Disbursements: Acts as a trusted mechanism for direct government benefits and subsidy payouts to remote citizens efficiently.
How to Get a Micro ATM Machine with AePS India (Step-by-Step)
To apply Micro ATM device, choose an authorized Aeps India, register as a merchant or agent on their Aeps portal, complete your KYC verification, and purchase or lease the hardware device.
Requirements to Apply
- Be at least 18 years old.
- Own a small shop, retail outlet, or fixed business service point.
- Have a smartphone (Android) with an active internet connection.
- Possess an active bank account for settlements.
Application Steps
- Choose a Provider: Select an RBI-approved Aeps india company offering Micro ATM and best AePS services.
- Register Online: Visit the official website or download the Aeps india provide application of Aeps india to fill out a retailer registration form.
- Submit KYC Documents: Upload or submit clear copies of your:
- PAN card
- Aadhaar card
- Passport-size photograph
- Shop or business address proof (electricity bill, rent agreement)
- Bank account proof (cancelled cheque or passbook copy)
- Pay Device Charges: Pay the applicable hardware and activation fees to purchase or lease the portable card-swipe/biometric unit.
- Installation and Activation: Once verified, the Aeps india will ship the device. Install their merchant app on your phone, pair the device via Bluetooth or USB, complete initial training, and start processing customer transactions.
How Much Does a Micro ATM Cost?
The micro ATM cost structure breaks down into one-time hardware purchases (₹1,499 to ₹15,000), optional Micro ATM software setup or licensing fees (₹5,000 to ₹35,000), and an agent commission model where retailers earn ₹1 to ₹15+ per transaction instead of paying recurring overhead.
Hardware and Setup Costs
- Basic Handheld Devices: Compact mPOS card-swipe or Bluetooth terminals (such as Mantra AF60S) cost ₹1,499 to ₹2,500.
- All-in-One Terminals: Devices featuring integrated thermal printers and Aeps fingerprint scanners for AePS run ₹5,000 to ₹15,000.
- Software Licensing / White-Label Setup: Ready-made B2B Micro ATM portal setups or Aeps API integration range from ₹5,000 to ₹35,000, with optional Annual Maintenance Charges (AMC) around ₹10,000+ for custom Micro ATM platform.
Commission and Revenue Structure (Agent Model)
Agents and shop owners act as banking correspondents, earning slab-based payouts per successful transaction rather than paying fixed monthly maintenance:
- Low-Value Withdrawals (₹500 – ₹1,999): ₹1.00 to ₹4.50 per transaction.
- Mid-Value Withdrawals (₹2,000 – ₹2,999): ₹4.00 to ₹7.00 per transaction.
- High-Value Withdrawals (₹3,000 – ₹10,000): ₹7.00 to ₹15.00+ per transaction.
- Balance Inquiry & Mini-Statements: Flat ₹1.00 to ₹3.00 per query.
How Do Micro ATM Agents Earn Money?
A micro ATM business makes money by earning a commission or fee on every financial transaction such as cash withdrawals, balance checks, or mini-statements processed through the handheld device for local customers.
How Income is Generated
- Transaction Commissions: Every time a customer uses their debit card or biometric verification to withdraw cash, the operator (banking correspondent or merchant) earns a fixed or percentage-based commission from the Aeps india.
- Extra Foot Traffic: For shopkeepers, the device brings more people into the store, which directly increases regular retail sales and impulse purchases.
- Cash Management: Retailers can effectively rotate and manage their daily shop cash collections by giving physical cash to customers in exchange for digital bank transfers into their merchant accounts.
Typical Revenue & Cost Structure
- Commissions per withdrawal: Usually range between fixed small amounts or tiered percentages based on the total withdrawal size set by the service aggregator network.
- Device setup cost: Low initial investment to purchase or lease the portable micro ATM reader and connect via a smartphone application.
- Settlement: Funds disbursed to customers are instantly debited from their accounts and credited back to the agent’s working digital wallet along with the earned commission.
How to Start a Micro ATM Business
To start a micro ATM business, register as an agent with a trusted, RBI-approved Aeps india and complete your Know Your Customer (KYC) verification.
Step-by-Step Launch Process
- Select a Provider: High Aeps commission structures and device costs among approved Aeps india.
- Complete Registration: Submit your identity and address proofs through the provider’s portal or mobile app.
- Procure the Device: Purchase or lease the micro ATM terminal, which typically costs between ₹1,500 and ₹5,000.
- Install and Test: Download the partner application, pair your device via Bluetooth or network sync, and run test transactions.
- Go Live: Offer cash withdrawals, balance inquiries, and mini statements to earn a commission on every successful customer interaction.
Micro ATM Transaction Limits and Charges
Micro ATMs (mATMs) allow customers to perform basic banking transactions using a portable card-swipe device with a debit card and PIN. Standard per-transaction limits for cash withdrawals are capped at ₹10,000, while customer charges typically align with normal ATM usage (free monthly quotas followed by roughly ₹21 to ₹23 plus GST per financial transaction).
Transaction Limits
- Minimum Withdrawal Amount: Generally ₹100 per transaction.
- Maximum Per-Transaction Limit: ₹10,000 for cash withdrawals and fund transfers.
- Daily/Aadhaar-linked Limits: Cumulative daily limits often match regular debit card limits (e.g., up to ₹25,000 total depending on the bank), though individual mATM card swipes remain restricted to ₹10,000 per invocation. AePS-tied monthly parameters may restrict usage to specific thresholds (such as 10 transactions or ₹50,000 per month depending on the issuer).
Charges and Fees
- For Cardholders (Customers): Standard rules grant a few free transactions per month depending on whether it is your own issuing bank or a different provider. Exceeding the free limits incurs standard financial transaction fees ranging from ₹21 to ₹23 + GST per withdrawal, and around ₹6 to ₹10 + GST for non-financial queries (like balance checks). However, many local merchant-operated micro-ATMs may charge independent convenience or cash-handling fees, which should be confirmed with the merchant beforehand.
- For Merchants/Operators: Aeps india compensate business correspondents or store owners via a fixed Micro ATM commission structure per successful financial transaction rather than charging them usage fees.
Micro ATM Security and Customer Authentication
Micro ATMs use portable point-of-sale (POS) devices managed by banking correspondents to deliver financial services in remote areas. They secure transactions and authenticate customers using a dual approach: traditional card-and-PIN verification and government-backed biometric identification through the Aadhaar Enabled Payment System.
Customer Authentication Methods
- Biometric Verification: Customers scan their fingerprint on a certified attached scanner. This fingerprint matches against centralized UIDAI biometric databases via encrypted matching services.
- Card and PIN: Customers insert any domestic or international debit card and enter their secret 4-digit PIN, mimicking standard ATM checks.
- Two-Factor Elements: Combines physical possession (card or unique Aadhaar ID number) with inherence (fingerprint) or knowledge (PIN).
Network and Device Security
- End-to-End Encryption: Transaction data is completely encrypted from the handheld POS terminal through mobile GPRS/4G gateways to the central bank switch.
- Interoperable Switches: Transactions route securely through national switches like the National Payments Corporation of India (NPCI) infrastructure.
- Agent Regulation: Because human agents or merchants operate the machines, security heavily relies on device binding, unique agent credentials, and real-time transaction tracking to stop fraudulent withdrawals.
Advantages and Limitations of Micro ATM
A Micro ATM is a portable, handheld card-swipe device used by authorized local agents to deliver basic banking services in remote or unbanked regions.
Advantages of Micro ATM
- Financial Inclusion: “Micro-ATMs play a crucial role in extending banking services, especially to rural and remote areas where traditional banking.
- Low Cost: Devices are inexpensive to buy, set up, and run compared to big traditional ATM kiosks that need rooms, heavy security, and AC units.
- Portability: “They can be used anywhere, unlike fixed ATMs.
- Local Jobs: Local shop owners earn commissions by working as banking agents, boosting community income.
- Easy ID Check: Users can verify transactions using a debit card and PIN or via fingerprint scans through the Aadhaar Enabled Payment System (AePS).
Limitations of Micro ATM
- Operator Dependency: “Operator dependency (no 24/7 access)” means users can only get cash when the local shop or agent is open.
- Cash Limits: Local agents often run out of physical cash in their tills during heavy demand.
- Network Failures: Devices rely heavily on mobile networks (GPRS/4G) to connect to bank servers, so bad signal stops work.
- No Cash Storage: The machine itself doesn’t hold or dispense cash; the human agent hands physical money from their shop cash register.
RBI Guidelines for Micro ATMs
The Reserve Bank of India (RBI) governs Micro ATMs handheld point-of-sale devices used by Business Correspondents (BCs) to ensure secure, interoperable banking in unbanked or remote areas. Guidelines require NPCI certification, end-to-end data encryption, strict adherence to EMV Chip and PIN security standards, and a mandatory automated reversal timeline of T+5 days for failed transactions.
Authorization & Operation
Authorized Agents: Devices must be run strictly by registered Business Correspondents or agents tied to scheduled commercial banks.
Float Limit: Individual operators generally cannot hold cash float amounts exceeding prescribed bank/regulatory limits (typically ₹50,000) during operations.
Deployment Areas: Priority deployment focuses on rural, unbanked regions, village panchayat offices, or mobile banking vans.
Security & Technology Standards
- EMV & PIN Compliance: All Micro ATMs must support secure processing of chip-and-PIN cards from inception, matching standard ATM security frameworks.
- Encrypted Communication: Devices must use secure, end-to-end encrypted protocols for routing transactions through authorized payment switches.
- Interoperability: Must support transactions for domestic debit cards and trusted AEPS across banks.
Transparency & Customer Service
- Transaction Slips: Every successful or declined transaction must generate an instant physical printed receipt or digital confirmation.
- Turn Around Time (TAT): For failed transactions where an account gets debited but cash fails to dispense, RBI mandates automatic reversal within T+5 days; otherwise, banks must pay a compensation penalty of ₹100 per day of delay.
What Happens If a Micro ATM Transaction Fails?
If a micro ATM transaction fails and your account is debited without cash being dispensed, the deducted amount is typically auto-reversed back to your bank account within a few working days under RBI guidelines.
What Happens Behind the Scenes
- Automatic Reversal: Most failed transactions undergo auto-reconciliation and reverse within T+5 calendar days (where ‘T’ is the transaction date).
- Delayed Compensation: If the bank fails to credit your account within the 5-day window, they are liable to pay a penalty of ₹100 per day of delay.
- Agent Interlock: Since micro ATMs are operated by Business Correspondents (BCs) or local shopkeepers, sometimes connectivity drops after the bank authorizes the debit. The system matches the merchant terminal logs with the central switch to trigger the refund.
Steps to Take
- Save the Receipt: Keep the transaction slip or failure receipt provided by the micro ATM agent. Note down the RRN (Retrieval Reference Number) or transaction ID from your SMS alert.
- Check Status: Wait a few hours, as many technical glitches resolve during preliminary batch processing. Check your mobile banking app to see if an auto-credit occurs.
- Lodge a Complaint: If the money is not returned within T+5 days, contact your issuing bank (the bank where your account is held) and provide the transaction details along with the micro-ATM location and agent ID.
- Escalate: If the bank does not resolve the issue within 30 days, you can escalate the matter through the RBI Complaint Management System.
How to Check a Micro ATM Transaction Status
You can check a Micro ATM (mATM) transaction status using the merchant app’s history log, your bank’s mobile app, or by contacting customer support with your transaction reference number.
Check via the Micro ATM Operator/Merchant App
- Open the App: Log in to the business or banking correspondent app (such as Aeps india) used to process the payment.
- Go to Transaction History: Navigate to the ledger, report, or transaction status section.
- Look Up the RRN: Locate the transaction using the 12-digit Retrieval Reference Number (RRN) or transaction ID from the receipt or screen prompt.
Review Status Meanings:
- Success: “Amount already credited in your wallet.”
- Pending: “Please check final status after 90 minutes.”
- Failed: “Amount will get auto reversed within 3-4 working days (after date of transaction).
Check via Customer Bank Account
- Open Mobile/Net Banking: Log into your personal bank application or check your registered mobile number for instant SMS alerts.
- View Passbook/Statement: Check your recent account statements or ledger to see if the amount was actually debited or reversed.
- Note Reference Details: If money left your account but the transaction failed or cash was not dispensed, record the date, time, and RRN. Contact your bank’s helpline if the automatic reversal fails within standard RBI guidelines (typically T+5 days).
Micro ATM Transaction Status
Transaction ID aur registered mobile number se status check karein.
AEPS vs Micro ATM — Key Differences
AEPS (Aadhaar Enabled Payment System) uses an Aadhaar number and fingerprint biometric scan. A Top Micro ATM uses a physical debit card and a secret PIN code (similar to a standard Micro ATM). AEPS requires only a cheap fingerprint scanner, while a Trusted Micro ATM requires a dedicated card-swipe terminal.
Comparison Table
| Feature | AEPS (Aadhaar Enabled Payment System) | Micro ATM |
|---|---|---|
| Primary Identifier | Aadhaar Number | Debit/ATM Card |
| Authentication Method | Fingerprint / Biometric scan | PIN (Personal Identification Number) |
| Required Hardware | L1 Biometric Fingerprint Scanner | Handheld POS/Card Terminal |
| Approximate Setup Cost | ₹1,500 – ₹3,000 (Low cost) | ₹10,000 – ₹25,000 (Higher cost) |
| Target User Group | Rural or unbanked individuals without cards | Urban/semi-urban cardholders |
| Handling Failed Scans | Fails if fingerprint doesn’t match | Bypasses biometric wear-and-tear issues |
Key Similarities & Shared Use Cases
- Services Offered: Both allow cash withdrawals, balance checks, and mini-statements.
- Interoperability: Both are regulated via the NPCI and work across multiple national bank networks.
- Business Model: Local shop keepers and local banking agents use both to service last-mile cash needs.
Micro ATM vs Traditional ATM
A Micro ATM is a portable, handheld terminal operated by a local banking agent or shopkeeper that uses biometric or card data for basic transactions. In contrast, a Traditional ATM is a large, standalone, self-service machine deployed in urban or commercial areas to independently dispense and accept cash.
Operational and Structural Differences
- Operation Model: Traditional ATMs are 24/7 self-service kiosks; best micro ATM require a human operator or business correspondent to process the transaction.
- Portability and Size: Traditional ATMs are heavy, stationary infrastructure requiring dedicated space and power; micro ATMs are pocket-sized, lightweight, and mobile.
- Authentication: Traditional ATMs rely strictly on a plastic debit/credit card and a numeric PIN; micro ATM device can authenticate via card-and-PIN or via biometric fingerprint scanning linked through an Aadhaar-enabled system.
- Cash Handling: Traditional physical ATMs store and dispense cash directly from internal cassettes; a micro ATM system does not hold cash itself the human agent physically hands over the cash from their retail drawer after the digital transaction clears.
- Setup and Maintenance Cost: Traditional units demand high capital for real estate, AC units, heavy security, and wired leased lines; best micro ATM device use standard mobile data and cost very little to deploy via local merchants.
Direct Comparison
| Feature | Traditional ATM | Micro ATM |
|---|---|---|
| Type of Device | Large automated kiosk | Portable handheld device |
| Managed By | Self-service / Bank managed | Local retailer or banking agent |
| Network Connection | Leased telephone/fiber lines | Cellular mobile data / Wi-Fi |
| Primary Location | Urban centers, banks, malls | Rural areas, local grocery shops, tier-3/4 towns |
| Card Necessity | Required (Debit/Credit Card) | Optional (Can use Biometrics/Aadhaar) |
Micro ATM vs POS Machine
A Micro ATM is a portable device used by bank agents to deliver basic banking services like cash withdrawals using debit cards or biometrics. A POS (Point of Sale) machine is a terminal used by merchants to process customer payments for goods and services. While they use similar handheld hardware, their core purpose differs.
Comparison Table
| Feature | Micro ATM | POS Machine |
|---|---|---|
| Primary Purpose | Basic banking & cash dispensing/deposits | Retail purchase payments & sales tracking |
| Biometric Support | Usually includes fingerprint/iris scanner | Not required / Generally absent |
| Cash Dispensation | Yes (handled manually by the agent) | No (cashless sales only) |
| Operator | Bank agent or authorized correspondent | Merchant or store cashier |
| Transaction Types | Withdrawal, deposit, balance check, fund transfer | Sale, refund, inventory logging, card payment |
Common Micro ATM Transaction Problems and Solutions
Common Micro ATM transaction failures typically stem from network timeouts, biometric authentication mismatches, or card-reading errors. Immediate troubleshooting involves re-initializing the application, checking GPRS/SIM connectivity, cleaning the device’s biometric scanner or chip slot, and ensuring proper app-to-host synchronization via your banking correspondent portal.
Network and Connectivity Failures
- Problem: Transaction times out or shows “Server Not Responding / Host Unreachable” due to poor mobile network coverage in rural or semi-urban areas.
- Solution: Switch the SIM slot or toggle airplane mode on the paired smartphone/terminal to refresh the network. Ensure the active SIM has an active data pack with strong signal strength.
Biometric Authentication Mismatch (Aadhaar/AEPS)
- Problem: Fingerprint scan fails repeatedly (“Authentication Failed” or “Device Not Connected”).
- Solution: Clean the customer’s finger and the scanner glass surface with a dry cloth. Ask the customer to place the center of their thumb or index finger firmly on the scanner. Re-plug the OTG/USB cable if using an external biometric device.
Card Reading and Chip Errors
- Problem: Device displays “Card Read Error” or fails to detect the debit card.
- Solution: Wipe the microchip and magnetic stripe of the card. Insert the card firmly into the EMV chip reader slot facing the correct direction. If the chip reader is faulty, try a fallback swipe option if supported by the application.
App Sync and DLL / Installation Errors
- Problem: Pop-ups freeze, or terminal shows dynamic link library (DLL) or installation failures (common on Verifone or Ingenico devices).
- Solution: Close the active menu, restart the Micro ATM hardware, and re-trigger the service via your merchant/BC portal. Ensure the Micro ATM application and device firmware are updated to the latest version.
Account Debited but Transaction Failed
- Problem: Customer’s account is debited via SMS, but cash is not handed over or the receipt is not generated.
- Solution: Do not panic or repeat the transaction immediately. Note down the RRN (Retrieval Reference Number) or transaction ID. Inform the customer that as per NPCI/RBI guidelines, failed transactions auto-reverse within T+5 working days. Check the transaction status in your application’s pending/history log for automated reversal confirmation.
Aeps India is The Best Micro ATM Provider in india
Aeps india one of the best micro ATM provider for your business, prioritize high transaction success rates, clear commission payouts, secure RBI and NPCI compliance, and 24/7 technical support. Aeps india ensures fast setups, durable hardware, and interoperability with all major debit cards.
Commission Structure and Pricing
- High payout margins: Aeps india offering strong, transparent per-transaction commissions without hidden fees.
- Real-time credits: Choose micro ATM platforms that instantly credit your earnings to your wallet or bank account.
- Device affordability: Compare upfront micro ATM hardware purchase costs and check if maintenance or best micro ATM software subscription fees apply.
Security and Compliance
- Regulatory approval: Aeps india and hardware are officially approved by the Reserve Bank of India (RBI) and National Payments Corporation of India (NPCI).
- Data protection: The micro ATM system must use secure end-to-end encryption for PIN and card data inputs.
Reliability and Performance
- High success rates: Frequent transaction failures harm customer trust and stall your business.
- Network uptime: Opt for Aeps india with robust server infrastructure to minimize downtime.
- Connectivity options: Ensure the best micro ATM device supports flexible network links like GPRS, Bluetooth, or Wi-Fi to handle local signal drops.
Services and Compatibility
- Interoperability: The micro ATM must accept RuPay, Visa, and Mastercard debit cards from all major national and private banks.
- Extra utility features: Look for best micro ATM platform bundling AePS, best BBPS and mobile recharges.
Support and Training
- Merchant assistance: Reliable customer care should be easily reachable to fix device lockouts or transaction failures fast.
- Onboarding guidance: The Aeps india company should provide simple operational training for you and your staff.
Why Choose AEPS India for Micro ATM Solutions?
Aeps india is a reliable Micro ATM Solution Provider requires evaluating regulatory compliance, high transaction success rates, clear commission payouts, and hardware compatibility. Aeps india ensures secure financial transactions, fast settlements, and minimal downtime for your retail or kiosk business.
Security and Compliance
- Regulatory Mandates: Aeps india follows guidelines set by the Reserve Bank of India (RBI), National Payments Corporation of India (NPCI), and UIDAI.
- Data Protection: Look for end-to-end encryption and PCI-DSS compliance to secure card and biometric data.
Reliability and Performance
- Uptime & Success Rate: Choose top Micro ATM platforms guaranteeing high operational uptime (99.9%) to prevent failed transactions.
- Settlement Speed: Verify that the Aeps india offers instant or same-day wallet and bank settlements to maintain steady cash flow.
Cost and Earnings
- Commission Structure: Compare per-transaction margins and hidden fees to maximize your earning potential.
- Device Pricing: Evaluate upfront hardware costs against built-in features like thermal printers and biometric scanners.
Features and Usability
- Interoperability: The terminal must accept debit cards across major networks (RuPay, Visa, Mastercard) alongside Aadhaar-enabled payment systems (AEPS).
- Customer Support: Responsive technical help and staff training keep your service running smoothly during operational hours.
Buy MICRO ATM for Your Business
Get a reliable MICRO ATM solution for offering convenient banking services at your business location. Connect with our team to discuss your MICRO ATM requirements, pricing, availability, and business setup.
Conclusion
A Micro ATM can help businesses, retailers, and banking service providers extend basic banking access through a compact digital device. For entrepreneurs building a fintech or assisted banking network, the Aeps india is not just about purchasing a device it is about having a reliable setup that fits the required business model, supported services, Micro ATM onboarding process, technical integration, and applicable banking or partner requirements.
With a suitable Micro ATM solution, authorized retailers and agents can offer supported services such as cash withdrawal, balance enquiry, mini statement, and other available banking transactions through the relevant banking and payment infrastructure. This can help businesses create an additional digital service point for customers while managing their retailer or agent network more efficiently.
A micro ATM is a small, portable handheld devicethat functions like a miniature bank card or swipe machine (PoS). Bank Mitras (banking associates) or agents use it to provide basic banking services like withdrawals, deposits, and balance checks to people in rural or remote areas.
Aeps india one of the Micro ATM provider in India, it is important to evaluate device compatibility, supported services, transaction workflow, security, technical support, settlement processes, reporting, and applicable compliance requirements. A reliable solution should match your actual business needs rather than simply offering a long list of features.
AEPS India provides Micro ATM solutions for businesses looking to expand their digital banking and assisted payment services. Depending on the selected solution and authorized partner arrangement, businesses can discuss Micro ATM devices, service integration, retailer onboarding, transaction workflows, and operational requirements before launch.
Whether you are building a retailer network, expanding an existing fintech business, or looking for a Micro ATM solution for your business, choosing the right technology and service partner is an important first step.
Ready to start or expand your Micro ATM business? Contact AEPS India to discuss your requirements and explore a suitable Micro ATM solution for your retailer network, digital banking business, or assisted financial services platform.
Frequently Asked Questions (FAQs)
A Micro ATM is a portable banking device that allows customers to access selected banking services through an authorised agent or Business Correspondent. Depending on the device and banking setup, services may include cash withdrawal, balance enquiry, cash deposit, fund transfer and mini statement. Micro ATMs are particularly useful in locations where conventional ATM or branch access is limited.
A Micro ATM connects to the relevant banking network through an authorised agent’s device. The customer selects a supported service, provides the required authentication such as card and PIN or another supported method, and the transaction is processed through the banking network. After successful authorisation, the agent completes the transaction and provides confirmation or a receipt.
Depending on the bank, device and service provider, a Micro ATM can support services such as cash withdrawal, balance enquiry, cash deposit, fund transfer and mini statement. Some implementations can also support Aadhaar-based transactions through AePS. The exact services should be confirmed with the Aeps india before deployment.
Not necessarily in every implementation. Card-and-PIN transactions are a common Micro ATM use case, while some devices or banking setups also support biometric/Aadhaar-based authentication. For example, Fino’s mATM specifically describes debit-card and PIN authentication, whereas other Micro ATM implementations may support additional authentication methods.
Supported card networks depend on the Micro ATM and banking arrangement. Common networks can include Visa, Mastercard and RuPay. Fino states that its mATM accepts debit cards from these networks, but customers should confirm supported cards with the specific service provider.
There is no single universal limit that applies to every Micro ATM. Limits can depend on the bank, transaction type, account and service provider. Fino currently states a ₹100 minimum and ₹10,000 maximum for its mATM, while other bank implementations can have different rules. Always verify the applicable limit before processing a transaction.
Micro ATM system designed for interoperable banking transactions, but actual availability depends on the participating banks, card network and service configuration. Some Micro ATM implementation support customers from multiple banks rather than being restricted to the agent’s own bank.
Yes, balance enquiry is one of the commonly supported Micro ATM services. The customer provides the required authentication, and the system retrieves the available account information from the banking network, subject to the participating bank and service configuration.
Some Micro ATM implementations support mini statements. Availability depends on the device, Aeps india. A mini statement can provide recent transaction information without requiring the customer to visit a traditional branch.
Yes, cash deposit can be supported by Micro ATM implementations, although availability depends on the participating bank and service configuration. Customers should confirm whether cash deposit is enabled on the specific Micro ATM before using the service.
Some Micro ATM setup support fund transfer in addition to cash withdrawal and balance enquiry. The availability and transaction limits depend on the bank and the specific implementation. Jammu and Kashmir Grameen Bank, for example, lists fund transfer among its Micro ATM transaction options.
No. A traditional POS terminal is primarily designed for accepting card payments at a merchant location, whereas a Micro ATM can provide assisted banking services such as cash withdrawal and balance enquiry. Some Micro ATM devices may use POS-like hardware, but their banking functionality is different.
Yes, Micro ATMs generally need connectivity to communicate with the banking network and process transactions. Depending on the device, connectivity may use mobile data such as GPRS/3G/4G or another supported connection. A weak or unavailable network can cause transaction delays or failures.
If a transaction fails, first check the transaction status and whether the customer’s account was debited. Keep the transaction/reference number and receipt for investigation. If the account was debited but cash was not received, the customer should raise the issue through the authorised Aeps india or the account-holding bank according to the applicable dispute and reversal process.
Do not attempt the transaction repeatedly without checking the status. Keep the transaction reference number, date, amount and receipt, and report the issue to the authorised Aeps india. The transaction can then be investigated and handled under the applicable reversal or dispute process. The exact resolution timeline depends on the bank and transaction type.
Micro ATMs are generally operated through authorised agents or Business Correspondents appointed under the relevant banking arrangement. A person should not independently provide banking services merely by purchasing a device; proper onboarding, authorisation and applicable KYC/business requirements must be completed first.
The usual process involves selecting an authorised Aeps india, completing the required KYC and onboarding, meeting eligibility conditions, obtaining or activating the supported device and completing the required training or verification. The exact process varies by Aeps india for example, separately addresses how a person can become its Aeps india.
A Micro ATM business can generate transaction-based income where an agent receives applicable commissions or margins, but profitability is not guaranteed. It depends on location, transaction volume, Micro ATM commission structure, cash availability, operating costs and the services offered. Aeps india describe profitability as dependent on business and transaction factors rather than a fixed income.
There is no single commission amount applicable to Aeps india. Commission can vary by transaction type, provider, agent category, business arrangement and applicable terms. Before joining, ask for the current commission structure and settlement terms in writing.
Yes. Micro ATMs are specifically useful for extending assisted banking services into rural, semi-urban and other areas where traditional branch or ATM access may be limited. Portable devices allow Aeps india to provide selected services closer to customers.
Micro ATMs can depend on agent availability, cash availability, network connectivity and the services supported by the particular device or bank. They also do not necessarily provide the full range of services available through a conventional ATM.
Operating hours depend on the agent outlet, Aeps india. Some Micro ATM services may follow the merchant’s operating hours, while others can be restricted by banking or settlement schedules. Fino, for example, states that its mATM availability depends on the merchant outlet’s working hours.
Yes. One of the main purposes of a Micro ATM is to extend selected banking services beyond traditional branch and ATM locations through authorised agents or BCs. This is particularly useful in remote areas.
Some Micro ATM implementations support biometric authentication, while others may primarily use card-and-PIN authentication. The available method depends on the device, bank and service configuration. Jammu and Kashmir Grameen Bank describes Micro ATM devices with both card-swipe and fingerprint options.
Yes, some devices and service platforms can support both Micro ATM and AEPS functionality. In such cases, the authentication method and transaction flow depend on which service the customer uses. PaySprint notes that both systems can be complementary and may be operated by the same BC agent.
Many Micro ATM implementations provide a receipt or transaction confirmation after processing. The exact receipt format printed, digital or SMS/app-based depends on the Aeps india for example, describes receipt generation after successful transactions.
A failed or disputed transaction may be subject to reversal or refund according to the applicable bank and network process. If the customer is debited but the service is not completed, the transaction should be reported with its reference number rather than assuming an immediate reversal. The actual resolution timeline depends on the transaction and responsible Aeps india.
Where an authorised Aeps india offers Micro ATM API-based integration, fintech businesses can integrate supported transaction functionality into their own application, Micro ATM portal or Micro ATM agent platform. Before integration, businesses should verify Micro ATM API documentation, authentication, supported transactions, device compatibility, transaction-status handling, settlement and compliance requirements.
Micro ATM Service in India – Complete Guide to Micro ATM Services
Best Micro ATM Software Solution in India: Features, Cost & Benefits
Micro ATM Software Development Company in India – Features, Cost & Benefits
About Author

