AEPS Portal Service: Features, Benefits & Complete Guide
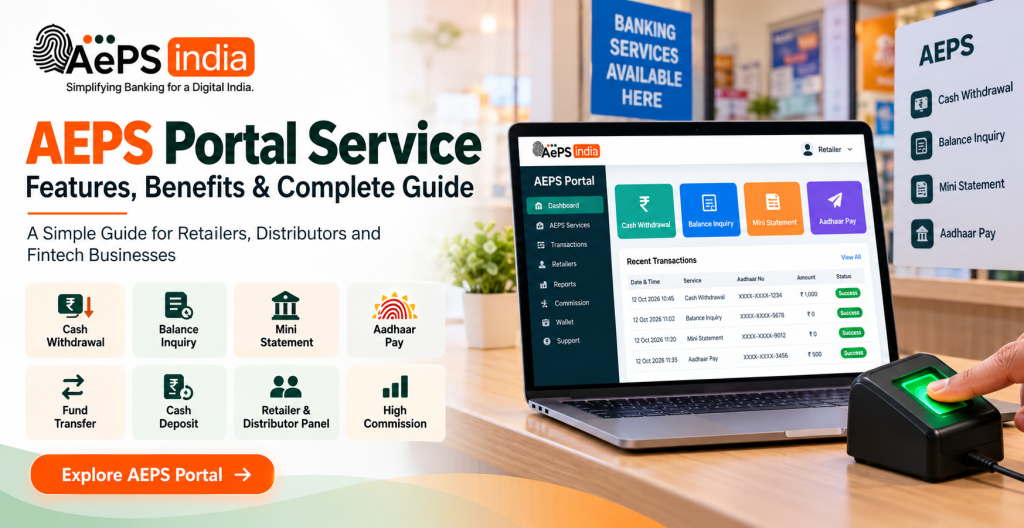
An AEPS Portal Service helps fintech businesses, banking service providers, distributors, and entrepreneurs offer Aadhaar Enabled Payment System (AEPS) services through an organized digital platform. If you are planning to start or expand an AEPS business in India, choosing the right AEPS portal can help you manage transactions, monitor retailer activity, track commissions, and handle daily operations from a centralized dashboard. Aeps India helps businesses explore AEPS software and Aeps API integration options based on their operational requirements.
A suitable AEPS Portal Service Provider can offer features such as cash withdrawal, balance enquiry, mini statement, transaction history, retailer and distributor management, commission configuration, reporting, and admin controls. Depending on the authorized banking or service-provider integrations, additional services may include cash deposit, Aadhaar Pay, and Micro ATM functionality. Actual service availability depends on the Aeps india authorization, eligibility, and applicable requirements.
Before selecting an AEPS Portal Service in India, compare the features, integration process, biometric device compatibility, Aeps API documentation, transaction-status tracking, failed-transaction handling, settlement procedures, data protection practices, and technical support. Pricing is important, but you should also understand ongoing maintenance costs, system scalability, and the provider’s authorization arrangements before launching your platform.
With Aeps India, businesses can explore AEPS portal solutions, AEPS API integrated, and white label Aeps platform options according to their needs. Depending on the selected configuration, the Aeps platform may support retailer management, transaction monitoring, commission management, reporting, and integration with supported digital financial services. The right Aeps setup depends on your business model, expected transaction volume, budget, and future expansion plans.
Whether you are a fintech startup, distributor, or established Aeps india, choosing the right AEPS Portal Service is an important step toward building an organized and sustainable operation. Contact Aeps India to discuss your requirements and explore suitable AEPS service software and Aeps API integrating options.
In this guide, you will learn how an AEPS Portal Service works, which features matter when choosing a provider, how b2b Aeps software and Aeps API integration support AEPS operations, and what to check before investing in an best AEPS platform. These considerations can help you compare available options and make a more informed decision for your business.
What Is an AEPS Portal Service?
An AePS (Aadhaar Enabled Payment System) portal service is a bank-led digital platform developed by the National Payments Corporation of India (NPCI) that allows customers to perform cardless and PIN-free financial transactions using their Aadhaar number and biometric authentication (such as a fingerprint scan).
How Does an AEPS Portal Work?
An AePS (Aadhaar Enabled Payment System) portal is a bank-led digital platform developed by the National Payments Corporation of India (NPCI) that lets users perform cardless, PIN-free financial transactions using just their 12-digit Aadhaar number and biometric verification (fingerprint or iris scan).
How an AEPS Portal Works
- Customer Request: A customer visits a local micro-ATM, Point of Sale (PoS) terminal, or authorized Aeps india.
- Details Inputted: The agent enters the customer’s bank name, Aadhaar number, and desired service type (e.g., cash withdrawal or balance check) into the Aeps portal.
- Biometric Authentication: The customer places their finger on a UIDAI-certified Aeps biometric scanner connected to the terminal or mobile device.
- Verification & Settlement: The data routes through NPCI to the UIDAI database for identity matching and connects to the user’s bank for real-time account debit/credit and settlement.
Types of AEPS Portal Services Available in India
An Aadhaar Enabled Payment System portal in India provides cardless, PIN-less financial and banking services using an Aadhaar number and biometric authentication (fingerprint or iris scan) through authorized Aeps india.
Main Types of AEPS Services Available
- Cash Withdrawal: Allows customers to withdraw money directly from their Aadhaar-linked bank accounts at retail or agent outlets without a physical debit card.
- Cash Deposit: Enables customers to deposit cash into their bank accounts through authorized banking correspondents.
- Balance Inquiry: Provides real-time checks on the available balance in an Aadhaar-linked bank account.
- Mini Statement: Lets users view a summary of their recent bank account transactions.
- Fund Transfer (Aadhaar-to-Aadhaar / Interbank): Supports money transfers between bank accounts linked with Aadhaar numbers.
- Aadhaar Pay: Facilitates direct merchant payments where customers authenticate via biometrics to pay for goods or services.
- Micro ATM / Kiosk Services: Integrates handheld hardware devices to handle basic banking functions at local shops turned into micro-banks.
AEPS Portal Service for Fintech Businesses
An AEPS (Aadhaar Enabled Payment System) Portal is a digital banking and Aeps financial software platform that allows fintech businesses, retailers, and Business Correspondents (BCs) to process cardless banking transactions using a customer’s Aadhaar number and biometric authentication. Developed under the NPCI AePS Guidelines, the system turns local retail outlets and digital kiosks into micro-ATMs.
Core Models for Fintech Businesses
- White-Label AEPS Portal: Lets you launch AEPS platform under your own brand name, custom domain, and logo while the underlying tech and Aeps bank API are managed by the Aeps india.
- B2B / Multi-Tier Admin Portal: Enables tiered management structures with dashboards for Super Distributors, Distributors, Retailers, and Support Teams to track transactions and commission earnings.
- API Integration: Allows tech-first fintech startups to integrate AEPS transaction capabilities directly into their existing mobile apps or web ecosystems.
Documents Required for AEPS Portal Services?
To register as a merchant, agent, or Business Correspondent (BC) to offer AePS portal services, you need identity, address, and financial verification documents.
Mandatory Documents Required
- Aadhaar Card: Serves as your primary identity proof and is required for biometric authentication.
- PAN Card: Mandatory for financial verification, tax compliance, and KYC processing.
- Bank Account Details / Proof: A copy of your bank passbook, cancelled cheque, or recent bank statement to receive commission payouts and settlements.
- Passport-Sized Photograph: A recent color photograph for your agent or retailer profile.
- Linked Mobile Number: An active mobile number directly seeded/linked with your Aadhaar card and bank account for OTP verifications and transaction alerts.
- Email Address: A working email ID for account activation, portal credentials, and official communication.
- Address / Business Proof: Utility bill (electricity/water), rent agreement, or shop/business registration certificate (required if operating a physical retail outlet).
Essential Non-Document Requirements
Aside from physical or digital paperwork, setting up an AePS portal/agent account requires:
- Biometric Device: A UIDAI-certified or STQC-certified Aeps fingerprint or Aeps iris scanner (such as Mantra, Aratek, or Evolute).
- Device & Internet: A working smartphone (Android), tablet, or computer/laptop with a stable internet connection to run AePS application or run Aeps portal.
- Age Requirement: Must be at least 18 years old.
Who Can Use AEPS Portal Services?
Anyone in India with an Aadhaar-linked bank account can use Aadhaar Enabled Payment System services.
The ecosystem involves two primary groups of users:
1. Bank Customers (End-Users)
- Eligibility: Any individual holding a bank account in India that is linked to their 12-digit Aadhaar number.
- Requirements:
- The bank account must be active and mapped with Aadhaar.
- Biometric authentication (Aeps fingerprint or Aeps iris scan) via a Aeps india.
- Key Use Cases: Rural citizens, underbanked populations, or anyone wanting cardless/PINless banking without visiting a physical bank branch.
2. Touchpoint Operators & Merchants (Service Providers)
- Business Correspondents (BCs) / Agents: Authorized bank agents, local shopkeepers, or micro ATM operators who set up a banking point using a registered biometric device and a paired smartphone, tablet, or laptop.
- Micro-Merchants: Small business owners and local shopkeepers who accept digital payments from customers using Aadhaar and biometric verification (such as via BHIM Aadhaar Pay).
Why Use AEPS Portal Services?
You should use the AePS service portal because it lets you perform basic banking services safely and easily using only your Aadhaar number and fingerprint scan, without needing a debit card, ATM PIN, or bank passbook.
Key Reasons to Use AEPS Services
- No Debit Card or PIN Required: Access your funds using just your Aadhaar number and biometric authentication (fingerprint or iris scan).
- No Need to Travel Far: Withdraw cash, check your balance, or get mini statements locally through nearby Aeps india in rural and underserved areas.
- Interoperable Banking: Transact using any participating bank’s account at any AePS-enabled touchpoint, regardless of which bank operates the machine.
- Government Benefit Transfers: Receive and withdraw direct benefit transfers (DBT) such as MGNREGA wages, social security, and old-age pensions directly at your doorstep.
- High Security: Prevent unauthorized transactions because every action requires mandatory biometric verification.
- Business Opportunities: Retailers and shopkeepers can turn their shops into mini ATM provide local banking services and earn transaction commissions.
Key Aspects of AEPS Portal Service
The Aadhaar Enabled Payment System (AePS) portal service is a bank-led digital Aeps platform developed by the Aeps indiathat allows cardless, PIN-free financial transactions using Aadhaar and biometric verification.
Key Aspects and Features
- Core Banking Services: Provides interoperable access to cash withdrawals, cash deposits, balance enquiries, mini statements, and fund transfers.
- Cardless & PIN-Free: Eliminates the need for physical debit cards, credit cards, or ATM PINs; transactions rely strictly on a 12-digit Aadhaar number and biometric data (fingerprint or iris scan).
- Interoperability: Enables customers to use a micro-ATM terminal of any participating bank to access accounts held in another bank.
- Financial Inclusion: Expands last-mile banking services to rural and unbanked populations by turning local retail shops and service points into mini-banks.
- Aadhaar Pay (Merchant Payments): Allows small merchants and rural shopkeepers to accept digital payments directly from a customer’s bank account via biometric confirmation.
- Additional Use Cases: Supports micro-insurance premium collections, eKYC for paperless account opening, and supplementary value-added services like mobile/DTH recharges through agent portals.
AEPS Portal Service for Fintech Startups, Distributors and Retailers
An AEPS Service Portal is a digital, bank-led Aeps platform develop via the Aeps india that lets businesses, distributors, and local shops offer cardless, PIN-less financial services using Aadhaar and biometric authentication.
Solutions by Business Role
1. Fintech Startups & Developers
- AEPS API Solutions: Developer-friendly backend code connections meant to embed cardless, biometric banking directly into existing fintech best Aeps apps.
- White-Label AEPS Portal: Fully trusted Aeps platform featuring custom domains, logos, and UI control for companies launching their own banking service line.
2. Distributors & Master Distributors
- B2B / Admin Portal: Comprehensive infrastructure to onboard sub-agents, create retail IDs, monitor live transaction volumes, and manage commission structures.
3. Retailers, Kirana Stores & Local Agents
- Retailer / Agent ID: Low-cost, ready-to-use access that turns a local shop into a mini-ATM or micro-bank branch.
- Required Hardware: A registered RD-service compliant Aeps biometric device (such as Mantra) paired with a smartphone, tablet, or computer.
Features AEPS Portal Service
An best Aeps portal is a digital Aeps banking platform that allows authorized retail agents, merchants, and business correspondents to provide cardless, PIN-free financial services to customers using their Aadhaar number and biometric authentication.
Key Features of an AePS Portal Service
- Cardless & PIN-Free: Transactions require only a 12-digit Aadhaar number, the bank name, and a Aeps fingerprint device or Aeps iris scan device no debit card, smartphone, or ATM PIN is needed.
- Interoperable Network: Developed by the Aeps india, the best Aeps system allows customers to use any bank’s account at any authorized AePS touchpoint across the country.
- High Security: Uses UIDAI-backed biometric authentication (fingerprint/iris) and encrypted data routing to prevent fraud and unauthorized access.
- Single-Dashboard Management: Retailers and agents manage all transactions, commission trackings, and reports from a unified web or mobile Aeps portal.
- Real-Time Settlement: Aeps india offer instant or 24/7 payouts and wallet-to-bank settlements for agents.
- Micro-ATM & Mobile Compatibility: Can be operated using Android smartphones, tablets, or dedicated micro-POS/biometric scanners.
- Business & Income Opportunity: Local shopkeepers and small business owners can earn per-transaction commissions while turning their stores into local mini-banks.
Benefits AEPS Portal Service
An AePS earning portal allows customers to perform cardless, PIN-free banking transactions using just their 12-digit Aadhaar number and biometric authentication (fingerprint or iris scan) through authorized Business Correspondents (BCs) or micro-ATMs.
Core Benefits for Customers & Citizens
- Cardless & PIN-Free: Eliminates the need to carry physical debit/credit cards or remember PINs and one-time passwords (OTPs).
- High Security: Uses unique biological identifiers (fingerprints or iris scans) tied to UIDAI records, reducing risks associated with stolen cards or forgotten PINs.
- Bank Interoperability: Customers of any participating bank can use any AePS-enabled touchpoint or micro-ATM across the country, regardless of their specific bank.
- Financial Inclusion: Brings essential banking services to rural and unbanked populations who live far from traditional bank branches or ATMs.
- Government Benefit Access: Simplifies receiving Direct Benefit Transfers (DBT) and government welfare funds directly through Aadhaar-linked accounts.
- Low Digital Literacy Friendly: Simple biometric verification makes it easy for individuals with minimal digital or formal banking experience.
Core Benefits for Retailers & Business Owners
- Turn Shops into Mini-Banks: Local kirana stores, pharmacies, and service centers can act as micro-ATMs, driving foot traffic into their physical locations.
- Earn Commission: Retailers earn a transaction-based commission on every cash withdrawal, balance check, or mini-statement processed through the portal.
- Business Operations Dashboard: Complete AEPS portal offer integrated digital wallets, settlement tracking, real-time server status, and automated reports.
AEPS Portal Development
Developing AePS portal involves building a secure, compliant Aeps software architecture that connects merchants, banks, the Aeps india, and the UIDAI for biometric authentication.
Phase 1: Requirements Definition & Regulatory Compliance
- Regulatory Approval: Partner with an Aeps india since direct switch connectivity requires heavy regulatory compliance.
- Compliance Standards: Ensure strict adherence to UIDAI data security, encryption standards (such as AES-256), and NPCI guidelines for biometric capture.
- Business Model Choice: Decide whether to build via custom Aeps mini statement API integration from scratch or use a White Label AePS Software solution provided by a Aeps india.
Phase 2: Core Architecture & Software Development
- AEPS API Integration Layer: Connect to AePS Balance Inquiry API to handle authentication and transaction requests (cash withdrawal, balance inquiry, mini statements, and fund transfers).
- Biometric Authentication Module: Integrate Aeps Software Develop Kits (SDKs) for STQC-certified Aeps fingerprint device or certified Aeps iris scanners device (e.g., Mantra) to capture and encrypt raw biometric data safely without storing it.
- Transaction Processing & Multi-Bank Routing Engine: Build the logic to route transactions through high-uptime banking switches and handle instant success, failure, or timeout responses.
- Admin & Agent Management Dashboard: Develop a backend web or mobile Aeps panel to manage multi-tier hierarchies (Admin, Master Distributors, Retailers/BC Agents), track live transactions, calculate commissions, and run T+0/T+1 settlements.
Phase 3: Hardware & RD (Registered Device) Integration
- Procure STQC certified Aeps biometric devices and link them with the respective manufacturer’s Registered Device (RD) service driver.
- Ensure device compatibility across Android mobile apps and web browser interfaces.
Phase 4: Testing & UAT (User Acceptance Testing)
- Sandbox Environment: Connect and test all transaction flows using the mock/sandbox Aeps API provided by the Aeps india.
- Security Audit: Conduct vulnerability assessment and penetration testing (VAPT) to secure agent logins, Aeps wallet data, and traffic routing.
- UAT & Pilot Launch: Run a limited pilot with a small group of business correspondents or retailers to monitor settlement accuracy and error-handling mechanisms.
Phase 5: Deployment & Agent Onboarding
- Deploy the top Aeps portal and mobile Aeps application to cloud infrastructure with high uptime guarantees (>98%).
- Onboard agents via e-KYC (Aadhaar and PAN verification), map their best Aeps biometric devices, and activate their banking correspondent status to begin live transactions.
AEPS Portal Service Setup Process: Step by Step
Setting up an trusted AePS portal as a merchant or agent involves registering with an authorized AePS india, completing KYC verification, and configuring certified Aeps biometric hardware.
Step 1: Gather Required Documents
Before starting the registration, keep these documents ready:
- Aadhaar Card (must be linked to your mobile number and bank account)
- PAN Card (mandatory for identity and tax compliance)
- Bank Account Details (passbook, cancelled cheque, or statement linked to your Aadhaar)
- Proof of Address (Voter ID, Driving License, or Passport)
- Passport-sized Photograph and a working mobile number/email address
Step 2: Choose an Authorized Service Provider
- Select an Aeps india.
- Visit their official website or download their Aeps merchant application.
Step 3: Complete Agent Registration & KYC
- Fill out the online Agent/Merchant Registration Form with your personal details, shop/business address, and bank information.
- Submit your digital KYC documents (Aadhaar, PAN, and bank proof).
- Complete video KYC or physical verification as required by the AePS india (typically approved within 24 to 48 hours).
Step 4: Purchase and Setup Biometric Hardware
- Acquire an STQC-certified biometric Aeps fingerprint scanner or Aeps iris scanner device (common compatible brands include Mantra).
- Plug the device into your smartphone (Android) or computer/laptop.
- Install the respective RD Service (Registered Device) driver application from the Aeps device manufacturer to enable live biometric capture.
Step 5: Portal Activation and Login
- Once your KYC is verified and approved, the Aeps india will issue your unique Agent/Aeps Merchant ID and Aeps portal credential.
- Log in to the AePS web dashboard or mobile Aeps app.
- Link your fast Aeps biometric device to the best Aeps app and start offering banking services (such as cash withdrawals, balance inquiries, and mini-statements) to customers.
AEPS Portal Service Cost in India
The cost structure of an AePS commission portal or reliable Aeps API depends on whether you are setting up as a Retailer/Agent, a Fintech Startup (White-Label), or an Enterprise / Direct Bank.
1. Setup and Integration Costs
- Retailers / Agents: ₹650 – ₹7,999 (often includes basic portal access and sometimes a starter biometric scanner).
- White-Label / B2B Portals: ₹12,000 – ₹35,000 for standard Aeps Cash Deposit API setup; ₹15,000 – ₹1,20,000+ for pre-branded white label Aeps admin panels and multi-Aeps service system.
- Direct Bank / Enterprise API: ₹2,50,000 – ₹4,50,000+ for direct connectivity and compliance with partner banks like ICICI Bank or Yes Bank.
2. Recurring & Maintenance Costs
- Annual Maintenance Fees (AMF): ₹10,000 – ₹40,000 per year (covers server uptime, security patches, and NPCI/UIDAI compliance updates).
- Software & Hosting Fees: ₹0 – ₹5,000 per month or ₹0 – ₹40,000 annually, depending on the Aeps india contract for domain, server hosting, and SMS gateways.
3. Transaction Charges & Commissions
- Agent Commissions: Retailers typically earn ₹5 to ₹13+ per successful cash withdrawal transaction (or structured via slab rates defined by the Aeps admin panel owner).
- Interchange & Routing Fees (Bank-to-Bank): Set by the National Payments Corporation of India (NPCI) for background settlement (e.g., ₹5 for cash withdrawal, ₹1 for balance inquiry, ₹3 for Aadhaar-to-Aadhaar fund transfer).
AEPS Portal Registration, KYC and Activation Process
To register and activate AePS agent/Aeps merchant portal in India, you must partner with an authorized AePS india.
1. Requirements for Agent Registration
To apply AePS agent (such as a local kirana shop owner or micro-entrepreneur), you need the following documents and equipment:
- Identity & Tax Proof: Aadhaar Card and PAN Card.
- Bank Details: An active bank account (for commission payouts and settlement) and a mobile number strictly linked to your Aadhaar.
- Contact Info: A working email address and active mobile number for OTP and login credentials.
- Business Proof: Shop address proof such as an electricity bill, rent agreement, or local business license (requested by some providers).
- Biometric Device: A UIDAI-certified Aeps fingerprint scanner (e.g. Mantra) compatible with Android or Windows.
2. Step-by-Step Registration & e-KYC Process
- Choose a Service Provider: Select a registered AePS india.
- Submit Basic Details: Fill out the online agent registration form with your name, mobile number, email, and shop/business address.
- OTP Validation: Verify your mobile number using the One-Time Password (OTP) sent to your phone.
- Agent e-KYC Verification: Complete the electronic Know Your Customer (e-KYC) process by entering your Aadhaar and PAN details, followed by a live Aeps fingerprint scan on your connected branded Aeps biometric device.
- Document Upload: Upload scanned copies or photos of your PAN card, Aadhaar card, photograph, and bank account proof.
3. Portal Activation
- Background Review: The AePS india reviews your application, PAN/Aadhaar details, and KYC status.
- Device Registration: Install the Aeps app or Aeps desktop software and register/whitelist your Aeps biometric scanner driver.
- Credential Issuance: Once approved, you receive your login credentials, dashboard access, and training guidelines via SMS or email.
- Go Live: Log into the AePS portal start offering cash withdrawals, balance inquiries, mini-statements, and Aadhaar-to-Aadhaar fund transfers to customers.
AEPS Portal Admin Panel: Features and Functions
An AePS Portal Admin Panel is the central backend control system used by fintech companies, banks, and payment service providers to manage Aadhaar Enabled Payment System (AePS) networks, agent hierarchies, and real-time financial transactions.
Core Features
- Hierarchical Network Management: Create, configure, and monitor multi-tier user levels, including Super Admins, Master White Label Aeps software, Distributors, Super Distributors, and Retailers/CSPs.
- Real-Time Transaction Monitoring: Track live customer transactions (cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay) routed through the National Payments Corporation of India (NPCI) gateway.
- Commission & Margin Configuration: Set automated, slab-based commission rules that split earnings in real-time across agents, distributors, and the primary admin wallet upon transaction completion.
- Wallet & Ledger Management: Oversee master float balances, process bank settlements (T+0 or T+1), and audit individual user ledger entries.
- Service ON/OFF Toggle: Enable or disable specific banking services, low cost Aeps API or individual retailer accounts with a single tap.
- White-Label Customization: Brand the web portal and Aeps mobile application with custom logos, company names, and domain settings.
Primary Functions
- Agent Onboarding & KYC: Verify and approve Know Your Customer (KYC) documents, assign service IDs, and manage biometric device integration (such as Mantra).
- Dispute & Refund Resolution: Handle customer transaction failures, track UIDAI/NPCI response codes, and process chargeback or refund requests.
- Reporting & Business Analytics: Generate granular audit trails, profit-and-loss summaries, daily volume reports, and ledger statements to analyze network performance.
- Security & Access Control: Enforce multi-layer encryption, role-based departmental permissions, and fraud-detection monitoring to maintain RBI and NPCI compliance.
AEPS Portal Commission, Wallet and Settlement Management
An AePS Portal manages commission structures, double-wallet systems, and fund settlements for Aeps india Server.
Commission Management
- Agent Earnings: Tracks per-transaction commissions for agents, typically ranging from ₹2 to ₹15+ depending on the transaction type and volume.
- TDS & Deductions: Automatically calculates and deducts Tax Deducted at Source (TDS) and platform service charges.
- Tiered Structures: Supports differential commission slabs for retailers, distributors, and super-distributors.
Wallet & Ledger Management
- Double-Wallet System: Separates the AePS Wallet (incoming cash withdrawal earnings and commissions) from the Main Wallet (used for utility bill payments, recharges, or fund transfers).
- Passbook & Ledgers: Maintains real-time digital passbooks, credit/debit logs, and balance top-ups.
- Dispute & Refund Handling: Tracks failed or stuck transactions, allowing admins to log tickets with the acquiring Aeps india.
Settlement Management
- T+0 (Instant Settlement): Allows agents and merchants to move funds immediately from their Aeps wallet portal to their linked bank account anytime.
- T+1 (Same/Next-Day Settlement): Automated batch processing that transfers accumulated funds to agent bank accounts on a scheduled timeline.
- Nodal Bank Routing: Controls the flow of liquidity between the AEPS nodal bank account, the Aeps payment platform internal pool accounts, and individual agent bank mappings.
AEPS Portal Security, Transaction Monitoring and Compliance
AEPS portals must follow strict security, monitoring, and compliance frameworks mandated by the National Payments Corporation of India (NPCI) and the Reserve Bank of India (RBI).
Security Standards
- Biometric Authentication: All transactions require UIDAI-certified, L1 Aeps biometric devices (fingerprint or iris) running active Registered Device (RD) services to prevent spoofing.
- Mandatory “One Operator, One Bank” Mapping: Strict mapping rules restrict a single operator/agent to a designated bank network to curb identity misuse.
- End-to-End Encryption: Biometric data and transaction requests are encrypted at the terminal layer and routed securely via the NPCI central switch to UIDAI.
- Multi-Factor Authentication (MFA): Enforced for high-value or risk-prone transactions.
Transaction Monitoring
- Real-Time Tracking & RRN Traceability: Aeps Admin panels use unique Retrieval Reference Numbers (RRN) to trace every cash withdrawal, balance check, mini-statement, and Aadhaar Pay transaction in real time.
- Multi-Bank Routing: Traffic is balanced across multiple banking partners to maintain high uptime (>98%) while flagging anomalies or failed authentication attempts.
- Agent & Tier Management: Centralized Aeps admin dashboard monitor agent onboarding, KYC status, transaction volumes, and active operational tiers.
Regulatory Compliance
- Due Diligence & KYC: Strict background verification, PAN and Aadhaar validation, and business address proofs are mandatory for last-mile Business Correspondents (BCs) and merchants.
- Settlement Controls: Nodal bank accounts handle automated or manual fund flows (such as T+0 or T+1 settlements) while tracking TDS deductions and commission structures.
Common AEPS Portal Problems and How to Handle Them
Aadhaar Enabled Payment System portals occasionally encounter technical and operational glitches that can disrupt transactions.
Here is a comprehensive guide to the most common AEPS portal problem and how to handle them effectively.
1. Biometric Authentication Failures
- The Problem: The smooth Aeps portal displays errors like “Fingerprint not matched” or “Biometric data did not match.” This is usually caused by worn-out fingerprints, dirty scanner lenses, or dry skin.
- How to Handle It:
- Clean the biometric scanner lens with a soft, lint-free cloth.
- Ask the customer to rub their hands together to warm them up, or use a small amount of moisturizer if their skin is too dry.
- Try registering a different finger (e.g., the thumb or index finger of the other hand).
2. Transaction Timeout / Pending Status
- The Problem: The network connection drops mid-transaction, leaving the status as “Pending” or showing a timeout screen. Cash may or may not be deducted from the customer’s bank account.
- How to Handle It:
- Do not re-initiate the transaction immediately to avoid double-deductions.
- Check your transaction history ledger after 5–10 minutes to see if the status updates to “Success” or “Failed.”
- If the money was deducted but the reliable Aeps portal shows “Failed,” reassure the customer that the amount will automatically reverse back to their account within 3 to 7 working days (per NPCI guidelines).
3. Server Down Errors (Bank or NPCI)
- The Problem: Errors like “Issuer Bank Server Down” or “NPCI Server Unavailable.” This happens when the destination bank’s core Aeps banking system or the central NPCI switch is facing heavy traffic or maintenance outage.
- How to Handle It:
- This is an external issue, so you cannot fix it locally.
- Ask the customer to wait for an hour or check if they have an alternate bank account linked to their Aadhaar that you can try instead.
4. Device Registration / Driver Errors
- The Problem: The high volume Aeps portal throws errors like “Device not registered,” “RD Service not found,” or “Error code 999.” This means the biometric device (Morpho, Mantra, NextBiometrics, etc.) isn’t communicating with the portal or its Registered Device (RD) service has expired.
- How to Handle It:
- Unplug the biometric device and plug it back in.
- Ensure the RD Service app (downloaded from the Google Play Store or PC driver page) is running in the background.
- Check the validity of your RD service subscription online. If expired, renew it.
- Clear your internet browser’s cache or restart the mobile application.
5. Account/Limit-Related Restrictions
- The Problem: Errors such as “Daily limit exceeded,” “Account not linked to Aadhaar,” or “Transaction not permitted to cardholder.”
- How to Handle It:
- Explain to the customer that banks set daily withdrawal limits on best AEPS (typically ₹10,000 per day or a limited number of transactions per month).
- Direct the customer to their home bank branch if their Aadhaar is not seeded/linked to their bank account properly.
Golden Rules for AEPS Retailers
- Maintain a physical register: Always write down the Date, Time, Customer Aadhaar Number (last 4 digits), RRN (Retrieval Reference Number), Amount, and Transaction Status. Get the customer’s signature. This is your primary shield in case of chargeback disputes.
- Check internet stability: Run a quick speed test before processing high-value transactions.
White Label AEPS Portal Service with Your Own Brand
A White Label AEPS Portal is a ready-made, customizable digital Aeps bank platform that lets your business offer Aadhaar-based financial services under your own company name, logo, and domain.
You can launch a branded Aeps financial portal via Aeps india or explore the Aeps platform setup guides on AEPS India.
Key Features Included
- Core Banking Services: Cash withdrawals, balance inquiries, mini-statements, and Aadhaar-to-Aadhaar fund transfers.
- Value-Added Services (VAS): Domestic Money Transfer (DMT), Best BBPS for utility bills, mobile/DTH recharges, and travel bookings.
- Admin & Network Control: Manage sub-distributors, create retailer networks, set custom commission tiers, and monitor live transactions via a centralized dashboard.
- Branded Assets: Custom web portal, branded Android Aeps mobile app and customized SMS/receipt notifications.
AEPS Portal vs AEPS pltaform: Key Differences
An AEPS Web Portal and an top AEPS Mobile App both deliver AEPS banking services, but they target different hardware environments, usage scenarios, and operator workflows. While web portals act as centralized Aeps administrative and heavy-duty Aeps retail dashboard, best Aeps mobile application turn smartphones into highly portable, on-the-go micro-ATMs.
Core Structural and Operational Differences
| Feature / Metric | AEPS Web Portal | AEPS Mobile App (Android Platform) |
|---|---|---|
| Primary Access Medium | Desktop, laptop, or PC web browsers. | Android smartphones and tablets. |
| Biometric Connectivity | Requires USB biometric scanners with custom desktop drivers (RD Services). | Connects seamlessly via USB OTG or Bluetooth scanners. |
| Ideal User & Environment | Fixed brick-and-mortar retail shops, fintech admins, and distributors. | Doorstep banking agents, mobile vendors, and field Business Correspondents. |
| Interface & Data Density | High-density dashboard; shows extensive ledgers, reports, and multiple wallet settlements. | Streamlined UI; optimized for rapid, one-tap micro-banking transactions. |
| Administrative Capabilities | Managing network structures, agent onboarding, bulk KYC, and distributor commissions. | Focused purely on transactional operations and immediate agent wallet checks. |
| Portability | Fixed or heavily restricted by desktop hardware footprints. | High mobility; works anywhere with a cellular network. |
| Peripheral Support | Direct integration with large thermal invoice printers and desktop PCs. | Integrates with compact Bluetooth thermal printers and handheld Micro-ATMs. |
Strategic Breakdown
- AEPS Web Portal: Serves as the operational backbone for fintech startups and Aeps B2B admin. It is Aeps designed for deep analytical tracking, managing wallet top-ups, reviewing transaction histories, and configuring commission slabs across large retailer networks.
- AEPS Mobile App: Aeps Design strictly for frontline execution. It provides a low-friction interface tailored for quick Aadhaar Pay software, cash withdrawal, balance inquiries, and mini-statement services directly at the customer’s side.
Aeps india One of The Right AEPS Portal Service Provider in India
Aeps india one of the right AEPS portal service provider requires evaluating several core technical, financial, and operational factors to ensure smooth business operations.
Key Factors to Consider
- Transaction Success Rate & Uptime: Look for a Aeps india that guarantees high uptime (ideally 99% or above) and a high transaction success rate (98%+) to avoid failed customer withdrawals and lost trust.
- Settlement Speed: Check how fast your funds settle into your bank account. Aeps india offer instant or same-day settlements.
- Security & Compliance: Aeps india has official NPCI certification, strong data encryption, and strict protection against fraud or unauthorized access.
- Commission & Charges: Compare Aeps commission structures across providers, but look beyond just the highest number; verify if there are hidden charges, maintenance fees, or excessive withdrawal limits.
- Platform Usability & Interface: The Highest volume Aeps portal or fast Aeps mobile app should feature intuitive navigation, fast processing speeds, multi-language support, and clear transaction history logs.
- Value-Added Services (VAS): Aeps india offers extra earning streams such as utility bill payments, mobile recharges, Micro ATM services, PAN card creation, or money transfers.
- Customer Support: Aeps india responsiveness by testing their support channels (phone, WhatsApp, or email) before signing up, as technical or biometric glitches require fast resolution.
- Hardware Compatibility: Ensure the Aeps commission platform smoothly supports UIDAI-certified biometric fingerprint or iris scanners.
Why Choose Aeps india for AEPS Portal Services?
Aeps india is a best AEPS portal service provider turns your retail shop into a local micro ATM software, allowing you to earn commissions while increasing customer footfall.
Key Reasons to Choose a Good AEPS Portal Provider
- High Transaction Success Rates: Aeps india offer 98%+ success rates and minimal technical downtime so customers do not leave frustrated.
- Attractive Commission Structures: Aeps india offers competitive per-transaction commissions or slab-based earnings on cash withdrawals, mini-statements, and balance inquiries.
- Instant Settlements (T+0 or Same-Day): Fast or immediate bank settlement options help you maintain continuous cash liquidity for your shop.
- Wide Biometric Device Support: The high commission Aeps portal should support multiple standard Aeps fingerprint scanners (such as Mantra).
- Multi-Bank Interoperability: A strong Aeps platform connects seamlessly across major nationalized and private banks managed through NPCI guidelines.
- Value-Added Services (VAS): Beyond basic cash withdrawals and balance checks, Aeps india integrate utility bill payments, mobile/DTH recharges, and fund transfers.
- Dedicated 24/7 Customer Support: Technical or server glitches happen; having responsive phone, chat, or email support prevents prolonged service outages.
- Detailed Reporting and Analytics: Real time Aeps dashboard let you track daily ledgers, commission summaries, and settlement records easily.
Conclusion: Choose the Right AEPS Portal Service with Aeps India
Choosing the right AEPS Portal Service is an important step for fintech startups, banking service providers, distributors, and entrepreneurs who want to offer best AEPS services through a digital Aeps platform. A suitable AEPS portal helps businesses manage transactions, monitor retailer activity, track commissions, and organize daily operations from a centralized dashboard. Before choosing a Aeps india, consider your business model, required features, integration needs, and long-term growth plans.
Aeps india is a reliable AEPS Portal Service Provider should offer essential features such as cash withdrawal, balance enquiry, mini statement, transaction history, retailer and distributor management, commission configuration, reporting, and admin controls. Depending on the authorized Aeps india integrations, additional services may include cash deposit, Aadhaar Pay API, and best Micro ATM functionality. Actual service availability depends on Aeps india authorization, eligibility, and applicable requirements.
When comparing AEPS Portal Services in India, look beyond the initial price. Review Aeps Cash Withdrawal API documentation, buy Aeps biometric device compatibility, transaction-status tracking, failed-transaction resolution, settlement procedures, security controls, system scalability, maintenance, and technical support. You should also verify the Aeps india authorization arrangements and understand how sensitive customer information is protected.
Aeps India helps businesses explore b2b AEPS portal, Aeps earning software, and best Aeps API integration options based on their operational requirements. Depending on the selected Aeps india, businesses can evaluate features for managing retailers, monitoring transactions, configuring commissions, reviewing reports, and connecting supported digital banking services. Selecting the right configuration can help organize business operations and prepare high volume Aeps platform for future expansion.
Whether you are launching a new AEPS business, upgrading an existing fast Aeps portal, or integrating AEPS services into a fintech application, choose a Aeps india that balances functionality, security, reliability, and cost. A well-planned implementation, supported by clear transaction-handling procedures and dependable technical assistance, can help you build a more manageable top AEPS operation.
Looking for an AEPS Portal Service for your business? Contact Aeps India to discuss your requirements and explore suitable modern AEPS software and modern Aeps API integration options.
Contact Aeps India: https://aepsindia.com/contact-us
Frequently Asked Questions About AEPS Portal Service
An AEPS Portal Service is a digital platform that enables eligible retailers and authorized business partners to facilitate Aadhaar Enabled Payment System (AEPS) transactions. Depending on the services enabled, customers can use it for cash withdrawal, balance enquiry and mini statements through Aadhaar-based biometric authentication.
An AEPS Portal Service provider may offer best Aeps service portal software, an admin dashboard, retailer and distributor management, transaction reports, commission configuration and low cost Aeps API integration. The exact services depend on the Aeps india offering and the business arrangement.
Aeps india can be contacted to discuss best white label AEPS portal requirements, including branding, Aeps portal customization, user management and integration options. Confirm the available features, licensing terms, third-party dependencies and Aeps onboarding requirements before purchasing.
The cost depends on whether you need an existing portal, a white label Aeps solution or custom Aeps software development. API integration, hosting, biometric devices, maintenance and third-party service charges may also affect the total cost. Request an itemized quotation from Aeps india before making a decision.
Check for the top AEPS services you require, retailer and distributor management, transaction history, wallet ledger, commission configuration, failed-transaction tracking, reconciliation reports, access controls and technical support. Verify that the features are included in your selected plan.
API integration is generally required when the faster Aeps portal must communicate with an external AEPS service platform. The integration connects supported functions with the Aeps india. Requirements depend on whether you are purchasing a ready-made portal or integrating AEPS into your existing Aeps service application.
Documents depend on the Aeps india, business model and applicable Aeps onboard rules. Business identity, PAN, bank details and KYC documents may be requested. Additional verification or authorization may be necessary before AEPS services can be activated.
Yes, this may be possible when your existing technology is compatible with the required AePS API Solution and the Aeps india permits integration. Before starting, confirm most Aeps API documentation, authentication requirements, supported fast Aeps platforms, transaction status handling and testing arrangements.
AEPS transactions generally require a compatible registered biometric device and the applicable authentication software or RD service. Device compatibility and registration requirements should be confirmed with the Aeps india before purchasing hardware.
An AEPS portal provide transaction records, status updates, commission rules and reports according to its configured features. Businesses should verify how commissions are calculated, when they are credited, how reversals are handled and how transaction records are reconciled.
Check the transaction reference, current status and Aeps india reconciliation process before initiating another transaction. Avoid repeating a transaction until its status has been verified. If the issue remains unresolved, contact the Aeps india with the reference number and relevant transaction details.
Aeps india supported services, integration documentation, security controls, pricing, Aeps onboarding process, transaction reconciliation, support arrangements and contractual terms. Ask for a demonstration and verify relevant authorizations and service dependencies before committing.
A portal with a suitable B2B hierarchy can support retailer and distributor accounts, role-based access, transaction reporting and commission configuration. Confirm the number of supported users, hierarchy options and management features available in your selected solution.
An High speed AEPS portal may suit fintech startups that want to offer Aadhaar-enabled banking services through an eligible business model. Startups should first assess onboarding requirements, Aeps india agreements, technical integration, operating costs and applicable regulatory obligations.
Businesses evaluating Aeps india can discuss their requirements for Higher volume AEPS portal software, Aeps API Services, retailer and distributor management, customization and technical support. Request a product demonstration, feature list and written quotation to confirm that the proposed solution meets your needs.
Contact Aeps india with your business model, required AEPS features, expected number of retailers, integration requirements and preferred portal type. Review the proposal, onboarding conditions, pricing and support terms before proceeding with registration and implementation.
Trusted AEPS Panel: Features, Benefits and Business Opportunities
AEPS System in India: How It Works for Banking Transactions
Why Businesses Should Integrate AEPS API in 2026
About Author

