AEPS Software Provider Company in India – Best AEPS Software Solutions
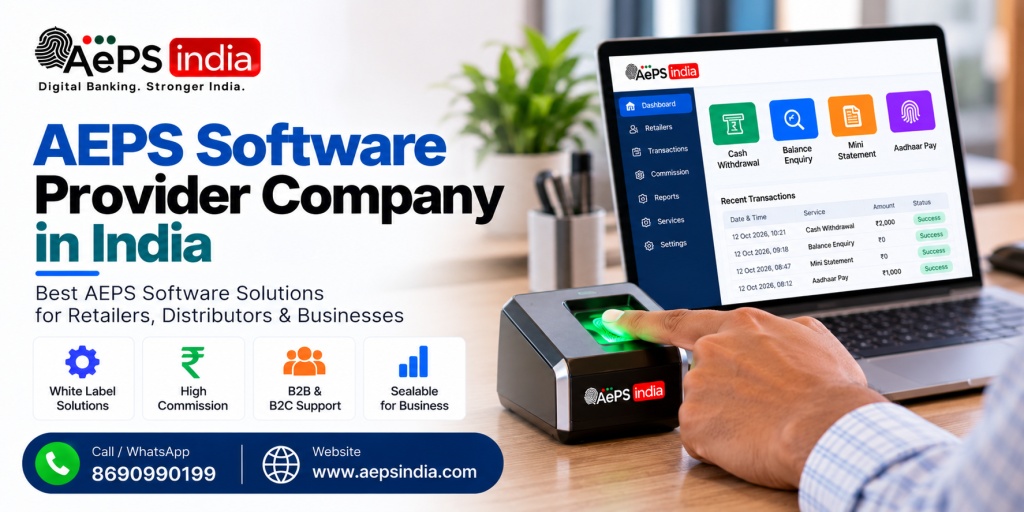
An AEPS Software Provider Company helps fintech businesses, banking service providers, distributors, and entrepreneurs launch digital banking services through the Aadhaar Enabled Payment System (AEPS). If you are looking for an AEPS Software Provider Company in India, Aeps India can help you explore software and API integration options suited to your business requirements. Whether you want to start new AEPS business, build a white-label platform, or integrate AEPS services into an existing fintech application, choosing the right software solution is essential for managing transactions and supporting business growth.
A reliable AEPS software solution can provide features such as cash withdrawal, balance enquiry, mini statement, retailer and distributor management, commission configuration, transaction history, reporting, and an Aeps admin dashboard. Depending on the authorized Aeps india and available integrations, your platform may also support cash deposit, Aadhaar Pay, and Micro ATM services. Actual service availability depends on provider authorization, eligibility, and applicable banking requirements.
An Aadhaar Enabled Payment System (AePS) software provider company builds and manages Aeps digital platforms that let retailers and fintech businesses offer basic banking services such as cash withdrawals, balance inquiries, and mini-statements using Aadhaar biometric verification.
Before selecting an AEPS Software Provider Company, compare more than just the initial price. Important factors include Aeps API integration capabilities, Aeps biometric device compatibility, transaction-status tracking, failed-transaction management, settlement processes, data security, system scalability, technical support, and ongoing maintenance. You should also verify the Aeps india authorization arrangements and understand how customer information is protected.
Aeps India helps businesses explore AEPS software, AEPS API integrated and white label Aeps platform options based on their operational goals. Depending on the selected solution, businesses can evaluate tools for managing retailers, monitoring transactions, configuring commissions, reviewing reports, and connecting supported financial services. Selecting the right Aeps setup can help streamline daily operations and provide a foundation for expanding your digital banking business.
If you are planning to launch or upgrade your AEPS platform, choosing the right AEPS Software Provider Company is an important step toward building a reliable digital banking service. Contact Aeps India to discuss your requirements and explore suitable software options.
In this guide, we explain what an AEPS software provider company does, which features to look for, how best AEPS software and Aeps API integrating work, what affects development and implementation costs, and how to evaluate a Aeps india before making a decision. Whether you are a startup, distributor, or established fintech business, this information can help you compare available options and identify a solution that matches your needs.
What Is an AEPS Software Provider Company?
An AEPS (Aadhaar Enabled Payment System) software provider company is a technology or fintech firm that develops and supplies the digital infrastructure, web portals, mobile Aeps apps, and Application Programming Interfaces (APIs) required to run Aadhaar-based banking transactions.
AEPS Software Provider Company Work?
An AEPS (Aadhaar Enabled Payment System) software provider company builds and maintains technology platforms that allow local retail shops, business correspondents (BCs), and fintech startups to act as mini-banks.
Core Functions & How It Works
- Biometric & Aadhaar Authentication: The Aeps service software connects customer transactions to the NPCI infrastructure using an Aadhaar number and Aeps fingerprint or Aeps iris scan via a certified Aeps biometric device.
- Basic Banking Services: It enables agents to process cash withdrawals, cash deposits, balance inquiries, mini-statements, and Aadhaar Pay for customers.
- White-Label & API Solutions: Aeps india offer ready-to-use white label Aeps portals, best mobile Aeps apps (Android/iOS), and admin/distributor panels so businesses can launch banking services under their own brand name.
- Multi-Bank Routing & Switch Integration: The branded Aeps software connects backend systems to multiple partner banks to ensure high uptime and transaction interoperability across different banks in India.
- Commission & Settlement Management: It tracks every transaction in real time, manages wallet balances, calculates retailer/agent commissions, and handles automated or instant settlements into bank accounts.
What Services Does an AEPS Software Provider Offer?
An AEPS (Aadhaar Enabled Payment System) software provider delivers cardless and PINless banking infrastructure that lets retail shops, micro-ATMs, and fintech startups operate as mini-bank branches.
Core Banking Services
- Cash Withdrawal: Customers can withdraw money from their Aadhaar-linked bank account using biometric (fingerprint or iris) authentication.
- Balance Enquiry: Real-time checking of available account balances.
- Mini Statement: Generation of recent transaction history summaries.
- Cash Deposit: Direct cash deposits into Aadhaar-linked accounts (where supported by the bank partner).
- Aadhaar Pay (Merchant Payments): Biometric payment acceptance for merchants with higher transaction limits (up to ₹50,000).
- Fund Transfers: Aadhaar-to-Aadhaar or domestic money transfers (DMT via IMPS/NEFT).
Who Can Use AEPS Software Provider Company
Aeps india is an AEPS Software Provider Company can be used by a wide range of businesses, entrepreneurs, and digital service providers looking to offer Aadhaar-enabled banking services.
Who Can Use AEPS Software?
- Retailers & Kirana Shop Owners: Local grocery stores, medical shops, and neighborhood outlets can turn their shops into “mini-ATMs” or banking touchpoints to offer cash withdrawals, balance inquiries, and mini-statements while earning commissions.
- CSP (Customer Service Point) Agents: Authorized banking correspondents who deliver micro-banking and financial inclusion services in rural and semi-urban areas.
- Distributors & Channel Partners: Businesses that manage a network of sub-agents or retailers and require distributor panels to oversee transactions, wallet loads, and commission distributions.
- Fintech Companies & Startups: Firms building or scaling digital banking, payment, or multi-service platforms that want to white label Aeps or integrate AEPS Service API directly into their own apps and websites.
- Digital Payment Service Providers: Enterprises offering utility bill payments (BBPS), domestic money transfers (DMT), mobile recharges, or micro ATM services alongside Aadhaar-based banking.
Why Use AEPS Software Provider Company
Partnering with an Aeps india for AEPS Software Provider (Aadhaar Enabled Payment System) allows retail shops, fintech startups, and digital business owners in India to turn their outlets into functional mini-banking centers.
Key Reasons to Use an AEPS Software Provider
- Cardless & PIN-Less Transactions: Enables customers to perform cash withdrawals, balance inquiries, and mini-statements using only their Aadhaar number and Aeps fingerprint device or Aeps iris scan device.
- New Revenue Streams (Commissions): Retailers and agents earn a commission on every successful banking transaction processed through the Aeps service platform.
- Regulatory Compliance & Security: Aeps india build NPCI- and UIDAI-compliant infrastructure, meaning businesses do not need to acquire separate, complex regulatory certifications.
- Low-Cost Infrastructure: Eliminates the need for expensive physical bank branches or complex point-of-sale (POS) hardware; standard smartphones or micro-ATMs with a best Aeps biometric device are sufficient.
- Real-Time Settlement & Automation: Features automated commission calculations, real-time wallet settlements, and integrated user/transaction management dashboards.
- Financial Inclusion Support: Expands basic financial services to rural and remote areas (“Bharat”) where traditional banking is sparse.
- Multi-Service Integration: Can easily bundle AEPS with other fintech offerings like Domestic Money Transfer (DMT), mobile recharges, bill payments, and micro-ATMs.
Key Aspects of AEPS Software Provider Company
Aeps india is an Aadhaar Enabled Payment System Software Provider Company develops and maintains technology infrastructure that lets retailers, Customer Service Points (CSPs), and fintech startups offer basic banking services using Aadhaar and biometric verification.
Key Aspects & Technical Features
- NPCI & Regulatory Compliance: Operates on approved banking switches ensuring alignment with Digital India and Reserve Bank of India (RBI) guidelines.
- Biometric Authentication: Integrates UIDAI-compliant fingerprint or iris scanner protocols (such as Best Finger Detection) for secure user verification.
- White-Label & API Solutions: Provides custom-branded Aeps mobile apps, Aeps admin panels, and multi service Aadhaar Enabled Payment System API that fintech businesses can integrate into their own ecosystems.
- Real-Time Settlement & Commissions: Features automated ledger tracking, instant transaction processing, and automated commission payouts for agents and distributors.
- Security & Fraud Prevention: Implements end-to-end encryption, multi-factor authentication, and bug-fixed architectures to block cyber threats.
AEPS Software for Retailers, Distributors and Master Distributors
An AEPS Software Provider delivers a multi-tiered B2B Aeps digital banking platform that enables retailers, distributors, and master distributors to offer Aadhaar-enabled biometric financial services.
Core Roles in AEPS Software Hierarchy
Master Distributor / White Label Owner:
- Manages the top-level admin dashboard, branding (white-label portal/app), and overall system architecture.
- Creates and oversees downline super distributors, distributors, and retailers.
- Configures global commission margins, best Aeps API integrations, and settlement structures.
Distributor:
- Acts as an intermediate layer between the master distributor and local merchants.
- Recodes, activates, and manages a network of retail agents.
- Earns commission overrides on every transaction processed by downline retailers.
Retailer / CSP (Customer Service Point):
- The last-mile touchpoint interacting directly with end customers.
- Performs biometric fingerprint authentication to deliver cash withdrawals, balance inquiries, mini statements, and Aadhaar Pay.
Why Business Need AEPS Software Provider Company
A business needs an Aadhaar Enabled Payment System (AePS) software provider company to turn retail or fintech networks into cardless, biometric mini-banks without building complex banking infrastructure from scratch.
Key Reasons Businesses Need an AePS Software Provider
- Turn Retail Shops into Mini-Banks: An AePS platform lets local kirana stores, CSPs (Customer Service Points), and agents offer essential banking services like cash withdrawals, balance inquiries, mini statements, and fund transfers using only an Aadhaar number and fingerprint/biometric scan.
- Bypass Complex Compliance & NPCI Certification: Building direct connections to the National Payments Corporation of India (NPCI) and banking partners requires heavy legal, regulatory, and technical compliance. Working with an established software provider lets you run on their pre-approved NPCI infrastructure.
- Generate Recurring Revenue & Commissions: Partnering with an AePS provider opens a daily-use transactional service. Your network earns real-time automated commissions on every cash withdrawal or balance check.
- Centralized Dashboard and Network Management: Instead of managing manual spreadsheets or fragmented logs, a provider’s white-label or API platform handles distributor/retailer hierarchies, wallet management, real-time transaction tracking, and automatic settlement slabs.
- Drive Financial Inclusion in Rural Areas: It bridges the gap in semi-urban and rural locations where physical bank branches and ATMs are far apart, allowing local merchants to serve unbanked or underbanked populations.
Features AEPS Software Provider Company
Aeps india is an AEPS (Aadhaar Enabled Payment System) software provider company delivers the core technical infrastructure, web portals, mobile apps, or APIs that allow businesses, retailers, and fintech startups to process cardless, biometric-based banking services.
Software & Platform Features
- White-Label & Custom Portals: Provides branded web and mobile Aeps app where companies can customize logos, colors, and dashboard layouts.
- Multi-Level Channel Management: Includes hierarchical dashboards (Super Admin, Master Distributor, Distributor, and Retailer/Merchant) to manage downstream networks.
- Automated Commission Engine: Calculates and credits margins or commissions in real time for every completed transaction.
- Instant Wallet & Payout Management: Supports real-time balance transfers, fund settlements, and cash-out options for agents.
- API Integration: Aeps india offers open and developer friendly Aeps API or ready-to-use SDKs to plug best AEPS into existing Aeps platforms.
Security & Compliance Features
- UIDAI & NPCI Compliance: Operates on pre-approved National Payments Corporation of India (NPCI) and RBI-compliant switches, bypassing the need for independent banking certifications.
- Biometric Device Integration: Supports certified Aeps fingerprint scanners and certified Aeps iris devices (Mantra etc.).
- End-to-End Encryption: Uses high-level data encryption and fraud-prevention protocols to protect sensitive customer data.
- Paperless e-KYC Onboarding: Enables fast, digital verification for retailers and agents.
Benefits AEPS Software Provider Company
An AEPS (Aadhaar Enabled Payment System) software provider company equips businesses, retailers, and fintech entrepreneurs with digital banking infrastructure to turn local shops into cardless, pinless micro-ATMs.
Key Benefits for Retailers & Business Correspondents (BCs)
- High & Steady Commissions: Earn Aeps commissions (ranging up to ₹10–₹15 per transaction or more) on cash withdrawals, balance checks, and mini-statements.
- Low Startup / Joining Fees: Most Aeps platform offer zero or minimal registration and infrastructure costs to set up the Aeps system.
- Instant Settlements: Receive daily or real-time wallet and bank settlements directly into your operating bank account.
- Increased Footfall: Acting as a local mini-bank drives more neighborhood customers into your retail store, boosting cross-sales for your primary business.
- Cardless & Pinless Operations: Customers only need their Aadhaar number and a biometric Aeps fingerprint scan, eliminating physical debit cards or memorized PINs.
Key Benefits for Fintech Entrepreneurs & White-Label Admins
- Launch Your Own Brand: White label Aeps APP and custom AEPS software solutions allow you to start a branded B2B fintech business under your own company name.
- Multi-Tier Network Management: Build and control hierarchical downlines including master distributors, distributors, and retail agents with automated margin-splitting engines.
- High Uptime & Multi-Bank Routing: Integrated multi-Aeps bank API (routing via NPCI standards) ensure high transaction success rates and minimal downtime.
- Comprehensive Admin Control & Analytics: Manage live transaction logs, automated compliance reporting, user wallets, and customer support ticketing from a single dashboard.
- Multi-Service Bundling: Easily cross-sell or integrate additional services like Micro ATM software, Bharat Bill Payment System software (BBPS), and mobile/DTH recharges.
Key Benefits for End Customers (Rural & Unbanked)
- Last-Mile Financial Inclusion: Access basic banking services locally without traveling long distances to physical bank branches.
- Convenient & Interoperable: Perform balance inquiries, cash withdrawals, cash deposits, and mini-statements across participating banks regardless of which bank holds their account.
- Enhanced Security: Multi-factor biometric fingerprint authentication drastically lowers the risk of card skimming, pin theft, or physical fraud.
Custom AEPS Software Development
The Aeps software development company process involves building or integrating a cardless, biometric-driven banking platform that connects retail agents, customers, the Unique Identification Authority of India (UIDAI), the National Payments Corporation of India (NPCI) switch, and destination banks.
Step-by-Step Development Process
1. Requirement Analysis & Scope Definition
- Determine the business model: AEPS API integration (building a proprietary app from scratch) vs. White label B2B AEPS software/Aeps portal (using a pre-built multi-tier network).
- Define user hierarchies (Super Admin, Master Distributor, Distributor, Retailer/Merchant) and core banking services (Cash Withdrawal, Balance Inquiry, Mini-Statement, Aadhaar-to-Aadhaar Fund Transfer).
2. System Architecture & Database Design
- Design a scalable cloud or dedicated server architecture with high-availability databases to handle real-time transaction logs and instant wallet updates.
- Implement Role-Based Access Control (RBAC) and encrypted ledger/wallet management engines.
3. Biometric Device & SDK Integration
- Integrate UIDAI-certified Aeps biometric hardware (fingerprint or iris scanners like Mantra etc.) using manufacturer-provided Registered Device (RD) Services.
- Build client-side or mobile modules to capture, compress, and strongly encrypt (AES-256) raw biometric payloads before routing. (Note: Biometric data is never stored locally.)
4. NPCI and Bank API Layer Integration
- Connect your trusted Aeps software with an authorized Aeps india to handle live authentication and financial request payloads.
- Build the routing logic to pass encrypted Aadhaar and biometric blocks to the NPCI switch and recipient bank, and parse real-time success or failure response codes.
5. Admin & Agent Dashboard Development
- Develop the web and mobile management panels featuring KYC onboarding modules, automated commission slab calculators, real-time transaction tracking, and dispute/grievance management.
- Integrate instant settlement (T+0) or wallet-crediting mechanisms.
6. Sandbox Testing & Compliance Certification
- Execute end-to-end transaction testing in bank and NPCI sandbox environments to verify payload security, biometric handshakes, and fail-safe handling.
- Ensure strict compliance with NPCI and UIDAI security guidelines before moving to a live production environment.
AEPS Software Pricing, Setup Charges and Maintenance Costs
AEPS software pricing in India varies based on whether you choose a basic developer setup, a white-label branded Aeps portal, or a direct bank enterprise integration.
1. One-Time Setup and Integration Charges
- Basic / Developer API Integration: ₹7,999 to ₹15,000 (for simple, self-managed Aeps developer scripts).
- Standard White-Label / Reseller Solutions: ₹12,000 to ₹35,000 (includes a branded B2B/B2C admin, distributor, and Aeps retailer panel).
- Custom White-Label / Feature-Rich Portals: ₹35,000 to ₹1,20,000+ (depending on multi-recharge, Aeps wallet systems, and additional utility integrations).
- Direct Bank / Enterprise API (e.g., ICICI Bank, Yes Bank): ₹1,50,000 to ₹4,50,000+ (provides direct bank connectivity and compliance controls).
2. Maintenance and Recurring Costs
- Annual Maintenance Charges (AMC): ₹9,999 to ₹40,000 per year (covers server upkeep, reliable Aeps software patches, and security updates).
- Monthly Portal / Hosting / SMS Gateway Charges: ₹0 to ₹5,000 per month depending on the contract and active transaction volume.
- Transaction / Routing Fees: Generally ₹0.25 to ₹1.50 per transaction or shared commission models depending on the Aeps india partner.
3. Additional Required Hardware
- STQC-Certified L1 Biometric Fingerprint Scanner: ₹2,000 to ₹3,500 (one-time hardware purchase).
- Smartphone, PC, or POS Terminal & Internet Connection: Variable cost based on existing equipment.
AEPS Admin Panel and Distributor Management System
An AEPS Admin Panel and Distributor Management System is a centralized B2B Aeps software platform that allows Aeps india to run and scale an Aadhaar Enabled Payment System network.
Core Architecture & Hierarchy
The platform typically operates on a multi-tier structure to manage funds, users, and commissions:
- Super Admin / Admin: Complete oversight of the entire ecosystem, bank switch configurations, system-wide transaction audits, and master limits.
- Master White Label / White Label: Enables sub-brands or partner businesses to run customized Aeps portals under their own name, logo, and domain.
- Super Distributors & Distributors: Manages regional or group-level onboarding, funding, and support for local merchants.
- Retailers / Agents / CSPs: The front-end micro-banking touchpoint where customers perform biometric cash withdrawals, balance inquiries, and mini-statements.
Aeps Biometric Device Support and Aadhaar Authentication
Aadhaar Enabled Payment System (AePS) requires STQC-certified L1 Aeps biometric devices that integrate with UIDAI Registered Device (RD) services to handle real-time identity authentication.
Supported Biometric Devices & Standards
- Certified Hardware: Only STQC-certified L1 Aeps fingerprint scanners (such as Mantra MFS100 L1) or approved iris scanners are permitted; older L0 devices are restricted or phased out.
- Registered Device (RD) Service: Every scanner must have its serial number registered on the manufacturer’s RD Service portal with an active license subscription to perform hardware-level encryption before data leaves the device.
Authentication Modes:
- Fingerprint & Iris Scanners: Mandatory for financial transactions like cash withdrawals and Aadhaar Pay.
- Face Authentication: Face auth for cash withdrawals and Aadhaar Pay is discontinued under NPCI guidelines, though it remains available for specific non-financial or 2FA workflows like balance inquiries, mini statements, and cash deposits.
Core Requirements for AePS & Authentication
- Customer Requirements: 12-digit Aadhaar number, customer bank name, consent, and a live Aeps fingerprint/iris scan (no debit card or PIN required).
Agent / Merchant Setup:
- Internet-connected smartphone (Android 7.0+), tablet, or Windows PC.
- Authorized AePS application, portal, or API integration.
- Active business KYC (PAN card, Aadhaar linked to mobile, settlement bank account, and business proof).
AEPS Wallet Management, Commission Calculation and Settlements
An AePS (Aadhaar Enabled Payment System) ecosystem manages agent liquidity, commission calculations, and fund payouts through three core pillars:
1. Wallet Management
- Working Ledger: The AePS wallet acts as a real-time digital ledger for Business Correspondents (BCs) and retail shop owners.
- Credit on Transaction: When a customer completes a cash withdrawal, the withdrawn amount plus the applicable commission credits instantly to the agent’s wallet.
- Liquidity Control: B2B Aeps Admins and b2b Aeps platform software manage wallet balances, set transaction limits, restrict unauthorized flows, and maintain audit trails.
2. Commission Calculation
- Slab-Based Payouts: Commissions are structured in tiered slabs based on the transaction type and amount rather than a flat percentage.
Cash Withdrawals:
- Low Value (₹100 – ₹2,000): ~₹1.50 to ₹5.00 per transaction.
- Mid Value (₹2,001 – ₹5,000): ~₹8.00 per transaction.
- High Value (₹5,001 – ₹10,000): ~₹12.00 to ₹15.00+ per transaction.
Non-Financial Services:
- Balance Inquiry: Free or ₹0.10 to ₹1.00 per check.
- Mini-Statements: ₹1.00 to ₹7.00 per request depending on the Aeps india.
- Aadhaar Pay (Merchant Sales): Percentage-based cut or flat incentive tiers (approx. 0.4% to 1.0% on merchant collections).
3. Settlements
Settlement Modes:
- T+0 (Instant / Same-Day Payout): Funds are moved immediately or multiple times a day from the AePS wallet to the agent’s designated bank account.
- T+1 (Next-Day Settlement): Standard batch processing settled on the next bank working day.
- Settlement Charges: Moving money from the AePS wallet to a mainstream bank account typically incurs a fee of ₹5.00 to ₹10.00 + GST per payout batch.
AEPS Software Transaction Reports, Reconciliation and Monitoring
Top AEPS software manages transaction reporting, reconciliation, and monitoring through centralized admin dashboards and automated NPCI (National Payments Corporation of India) file workflows.
Transaction Reports
- Granular Activity Logs: Tracks all core services Cash Withdrawal, Cash Deposit, Balance Inquiry, Mini Statement, and Aadhaar Pay.
- Status Classification: Separates transactions into successful, failed, or pending/timeout states in real time.
- Agent & Distributor Slabs: Generates reports segregated by Business Correspondent (BC), retailer ID, distributor hierarchy, and commission earned.
- Export & Audit Tools: Supports automated and manual data exports for accounting and statutory compliance.
Reconciliation
- NPCI File Integration: Automates the download of settlement and transaction files from the NPCI portal.
- Automated BC Segregation: Matches terminal logs against bank and switch responses to eliminate manual spreadsheet tracking.
- Managed File Transfer (MFT): Consolidates and uploads automated logs to enterprise banking and ledger systems.
- Dispute & Refund Handling: Flags mismatches (e.g., amount debited from customer account but not credited to retailer/terminal) to trigger automated chargebacks or T+0/T+1 settlements.
Real-Time Monitoring
- Terminal & Agent Health: Live visibility into active BC terminals, device connectivity, and geographic deployment.
- Failover & Routing Analytics: Monitors multi Aeps banking API routing paths and auto-failover events to maintain high transaction success rates.
- Fraud & Limit Alerts: Tracks velocity rules, suspicious fingerprint authentication patterns, and standard per-transaction limits (up to ₹10,000).
Security Features Required in AEPS Software Provider
Aeps india is a reliable AePS software provider must adhere to strict regulatory, data protection, and hardware security standards mandated in India.
Regulatory & Compliance Standards
- NPCI & RBI Certification: The Aeps earning software must be officially certified by the National Payments Corporation of India (NPCI) and follow Reserve Bank of India (RBI) guidelines for financial inclusion and safety.
- UIDAI Adherence: Full compliance with Unique Identification Authority of India (UIDAI) guidelines for capturing, processing, and handling biometric data.
- L1 Biometric Certification: Support for modern L1 (Level 1) certified biometric devices to ensure liveness detection and prevent spoofing.
Data & Transmission Security
- End-to-End Encryption (E2EE): Strong encryption protocols protecting sensitive customer details and financial data both during transmission across networks and at rest.
- Registered Device (RD) Service Integration: Mandatory integration with official RD services for fingerprint or iris scanners to encrypt biometric data at the hardware level before it leaves the scanner.
- Secure API & IP Whitelisting: Protected Aeps API communication channels paired with IP whitelisting to restrict portal access to authorized servers and terminals.
Fraud Detection & Access Control
- AI-Driven Fraud Monitoring: Real-time transaction monitoring and anomaly detection to flag suspicious or unauthorized activities immediately.
- Role-Based Access Control (RBAC): Granular admin and user permissions ensuring that sensitive dashboard controls (such as accounting or settings) are separated from agent/sales functions.
- Session & Password Security: Strict password policies, auto-logout on inactivity, and encrypted session management.
Audit & Transparency
- Comprehensive Audit Trails: Immutable logs tracking every login, transaction attempt, and best Aeps system modification for compliance and forensic reviews.
- Real-Time Transaction Alerts: Instant SMS, email, or webhook notifications sent to agents and account holders for every transaction processed.
AEPS Software Provider vs AEPS API Provider: What’s the Difference?
An AEPS Software Provider delivers a complete, ready-to-use trusted Aeps platform with Aeps panels (Admin, Distributor, Retailer) to manage users, commissions, and wallets, whereas an AEPS API Provider offers a set of code hooks and backend infrastructure to embed Aadhaar payment features directly into your own custom Aeps application or website.
Comparison Table
| Feature / Aspect | AEPS Software Provider | AEPS API Provider |
|---|---|---|
| Core Product | A turn-key, end-to-end white-label web/mobile platform | A set of Application Programming Interfaces (APIs) and backend endpoints |
| Target Audience | Startups or businesses wanting a quick, pre-built portal to onboard agents/retailers | Developers, fintechs, or enterprises building their own custom app or software |
| UI & Panels Included | Comes with built-in Admin Panel, Distributor Panel, and Retailer/Agent Panel | No UI provided; you must design and build your own user interface |
| Commission & Wallet Mgmt | Pre-integrated commission structures, wallet balances, and settlement reports | Requires custom logic to handle wallet balances, slabs, and commission payouts |
| Customization & Branding | Limited to white-label branding (logo, theme, domain) | Full flexibility to customize the user experience, flow, and features |
| Time to Launch | Fast (days to a couple of weeks, ready-made setup) | Longer (requires custom software development and testing) |
| Biometric / Hardware Support | Integrated RD service and device binding out-of-the-box | Requires custom integration of UIDAI-certified L1/L2 biometric scanners (e.g., Mantra, Morpho) |
White Label AEPS Software Provider Company
Aeps india is an White Label AEPS software provider Company lets you launch a branded digital banking and payment platform without building the underlying technology from scratch.
Key Features Included in White Label AEPS Solutions
- Custom Branding: Your own company name, logo, domain, and mobile Aeps application.
- Core Banking Services: Cash withdrawals, balance inquiries, mini statements, and Aadhaar Pay.
- Multi-Tier Network Management: Aeps Admin panels to create and manage super distributors, distributors, and retail agents.
- Automated Commissions & Settlements: Real-time or scheduled commission calculations and wallet management.
- Biometric Device Compatibility: Support for major fingerprint scanners like Mantra.
Aeps india One Of The Best AEPS Software Provider Company in India
Aeps india only one of the best AEPS (Aadhaar Enabled Payment System) software provider company in India depends on key technical, financial, and operational factors:
Key Factors to Consider
- Security & Compliance: Ensure the strong Aeps software adheres to NPCI guidelines, UIDAI biometric authentication standards, end-to-end data encryption, and PCI-DSS/ISO security compliances.
- Transaction Success Rate & Uptime: Aeps india that offer high uptime (ideally 99% or higher) and fast processing times to prevent failed biometric transactions.
- Commission & Settlement Structure: Evaluate per-transaction earnings, commission rates, and settlement cycles (real-time, instant, or end-of-day payouts) with transparent pricing.
- Integration & Developer Support: Check for clear high speed Aeps API documentation, SDK support, white-label options, and sandbox testing environments if you plan to integrate Aeps system into your own Aeps earning platform.
- Hardware & Biometric Compatibility: Verify that the fast Aeps platform supports widely used biometric fingerprint and iris scanner devices (such as Mantra).
- Dashboard & Admin Controls: Look for real-time reporting, transaction history, wallet management, retailer/distributor hierarchy controls, and automated dispute resolution workflows.
- Customer Support: Ensure dedicated technical support is available (preferably 24/7) to handle stuck transactions or server downtimes.
Why Choose Aeps India as Your AEPS Software Provider Company?
Aeps India one of the right AEPS software provider company is essential for fintech businesses, distributors, and local retailers looking to offer cardless, PIN-less banking services like cash withdrawals, balance inquiries, and mini-statements.
Key Reasons to Choose a Reliable AEPS Software Provider
- NPCI & Regulatory Compliance: Aeps india ensures full alignment with guidelines from the National Payments Corporation of India (NPCI) and the Reserve Bank of India (RBI), keeping your platform legally compliant.
- High Transaction Success & Uptime: Quality infrastructure guarantees stable multi-bank connectivity and fast processing speeds, reducing failed biometric or server-side transactions.
- Security & Biometric Protection: Robust encryption protocols safeguard customer Aadhaar data and financial records against fraud or unauthorized access.
- White-Label & Custom Branding: Aeps india offer white label Aeps solutions, allowing you to run web portals and branded mobile Aeps apps under your own brand identity rather than building everything from scratch.
- Multi-Level Administration & Dashboards: Built-in controls let you manage role-based access for admins, distributors, and retail agents, alongside real-time transaction monitoring.
- Automated Commission & Wallet Management: Streamlines instant settlements, agent commission splits, and account ledger tracking.
- Rural Financial Inclusion & Revenue Growth: Empowers local shops to act as mini-bank branches, driving high-frequency daily footfall and creating recurring revenue streams.
Conclusion: Aeps India is The Right AEPS Software Provider Company
Choosing the right AEPS Software Provider Company is an important step for fintech startups, banking service providers, distributors, and entrepreneurs who want to launch or expand their digital banking business. Aeps india should offer a solution that fits your business model, supports essential best AEPS services, and helps you manage transactions and daily operations efficiently. Before making a decision, evaluate the smooth Aeps software features, reliable Aeps API integration options, security measures, technical support, scalability, and overall cost.
A complete AEPS Software Solution may include cash withdrawal, balance enquiry, mini statement, retailer and distributor management, commission configuration, transaction reports, an admin dashboard, and transaction-status tracking. Depending on the authorized Aeps india integration, additional services may include cash deposit, Aadhaar Pay API, and Micro ATM functionality. Available top Aeps services depend on Aeps india authorization, eligibility, and applicable requirements.
An AePS (Aadhaar Enabled Payment System) Software Provider Company develops and supplies Aeps platforms, supply Aeps mini statement API and Aeps white label admin panels that let businesses offer cardless banking services.
When comparing an AEPS Software Provider Company in India, do not choose a solution based on price alone. Check top Aeps API documentation, buy Aeps biometric device compatibility, failed-transaction handling, settlement procedures, data protection practices, maintenance arrangements, and the availability of technical assistance. Also confirm the Aeps india authorization arrangements and the responsibilities involved in operating your AEPS business.
Aeps India helps businesses explore high volume AEPS software and leading Aeps API integration options according to their operational needs. Whether you are planning an fast AEPS portal, a white label Aeps b2b platform, or AEPS integration for an existing Aeps fintech application, selecting the right configuration can help you organize retailer operations, monitor transactions, manage commissions, and prepare your business for future growth.
Ultimately, the best AEPS Software Provider Company is one that understands your requirements and offers a suitable, secure, and maintainable solution with clear integration terms and dependable technical support. Compare your options carefully, verify the available services, and choose software that supports your long-term business objectives.
Ready to explore AEPS software for your business? Contact Aeps India to discuss your reputed AEPS software, API integration, or best white label Aeps platform requirements.
Contact Aeps India: https://aepsindia.com/contact-us
AEPS Software Provider Company with Aeps India
Looking for a reliable AEPS Software Provider Company? Aeps India can help you explore AEPS software solutions for your digital banking business. Contact our team to discuss software features, pricing, integration and business requirements.
FAQs About AEPS Software Provider Company – Aeps India
Aeps India is an AEPS software provider company offers software and integration solutions that enable businesses to provide Aadhaar Enabled Payment System (AEPS) services through supported banking and payment networks. These solutions may include retailer applications, admin panels, distributor management, biometric device integration, transaction reports, and commission management.
Aeps India is an AEPS software provider based on its supported banking partners, service availability, API documentation, biometric compatibility, transaction monitoring, settlement process, technical support, security practices, and total cost. Verify the Aeps India authorization and partner arrangements before launching your AEPS business.
AEPS software should offer the features relevant to your business model, such as cash withdrawal, balance enquiry, mini statements, retailer management, transaction history, status tracking, reconciliation, commission calculation, and administrative controls. API access, biometric device compatibility, and reporting tools may also be important.
Aeps India offer white-label solutions that allow businesses to launch services using their own brand identity. Depending on the package, customization may include the application name, logo, interface, retailer panel, and admin dashboard. Confirm branding rights, licensing, and applicable banking or network requirements before purchasing.
AEPS API integration connects a business application or fintech platform with an AEPS service provider’s supported infrastructure. It enables the application to send transaction requests, receive responses, retrieve transaction statuses, and integrate supported services. The exact process depends on the provider’s API documentation, authentication method, testing environment, and onboarding requirements.
AEPS software costs vary according to the features, white-label requirements, API access, customization, support, and integration services included. Some providers charge setup or recurring fees, while others use transaction-based commercial models. Request a written quotation covering implementation, maintenance, taxes, and any additional charges.
Yes, white-label AEPS software can be an option for businesses that want to operate under their own brand. You should first confirm the provider’s service arrangements, onboarding conditions, required documentation, commercial terms, and eligibility requirements. Software alone does not guarantee authorization to provide AEPS services.
Depending on the Aeps India and its supported banking arrangements, AEPS software may facilitate cash withdrawal, balance enquiry, and mini statements. Additional services may be available through separate integrations. Confirm the currently supported services before selecting a solution.
Many AEPS platforms include retailer and distributor management features. These may allow administrators to create accounts, assign roles, manage access, review transactions, configure eligible commission structures, and generate reports. Available features depend on the software package.
Device compatibility depends on the software, operating system, device model, and applicable Registered Device (RD) Service requirements. Before purchasing biometric hardware, confirm that the device and its RD Service are supported by the selected platform and applicable authentication ecosystem.
AEPS commissions depend on the Aeps India commercial agreement, transaction type, amount slab, applicable partner terms, and other conditions. Review the written commission chart, eligibility rules, settlement schedule, and any deductions before estimating business revenue. Commission rates should not be assumed to be identical across providers.
Settlement procedures vary by Aeps India arrangement. The software may display transaction records, settlement information, and reconciliation reports to help businesses track their funds. Confirm settlement timelines, cut-off times, failed transaction handling, and escalation procedures with the Aeps India.
Security depends on the platform’s implementation and operational controls. Evaluate authentication, role-based access, encrypted communications, audit logs, sensitive-data handling, transaction monitoring, and incident response procedures. Verify relevant security documentation instead of relying only on general claims that a platform is secure.
Yes, integration may be possible when the Aeps India offers a compatible API and your application meets its technical and operational requirements. The integration process typically involves reviewing documentation, obtaining credentials, testing supported transaction flows, handling errors, and completing the required approval process before production use.
Requirements vary according to the Aeps India, business structure, and applicable banking or network arrangements. Businesses may be asked for identity and address documents, business registration details, PAN information, bank account details, and other verification documents. Obtain the official checklist from the provider before beginning onboarding.
Check the available features, supported services, integration documentation, pricing, uptime and support commitments, transaction-status handling, reporting, device compatibility, security controls, and contract terms. Ask for a demonstration and test the important workflows before making a final decision.
Aeps India is an AEPS software provider generally focuses on the application and management tools used to operate AEPS services. Aeps India focuses on programmatic integration with supported services. Aeps India offer both. Compare the actual scope of each offering rather than relying only on the Aeps India.
Software with transaction-status tracking, reports, reconciliation tools, and support workflows can help businesses investigate failed or pending transactions. The resolution process depends on the transaction status, banking partner, and Aeps India procedures. Always follow the official process for checking the final status before retrying a transaction.
When evaluating Aeps India, review its available AEPS software features, supported services, integration options, retailer and distributor management tools, pricing, onboarding process, and customer support. Request a product demonstration and written details of its service arrangements to determine whether the solution meets your business requirements.
Start by contacting Aeps India to discuss your business model, expected transaction volume, required services, and branding or API integration needs. Request the feature list, pricing, onboarding checklist, technical documentation, and applicable service conditions. Verify all requirements before proceeding with implementation.
Best AEPS Application Provider in India: Complete Guide to AEPS Registration, Services & Benefits
AEPS Platform Provider in India – Complete Overview

AEPS Panel Service Provider: Everything You Need to Know in 2026
About Author

