AEPS White Label Software: Features, Benefits & Complete Guide
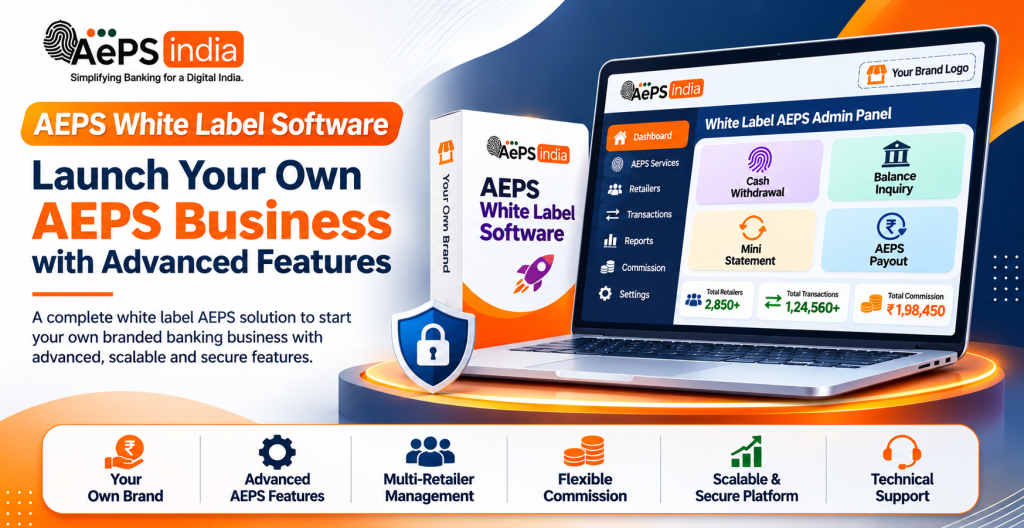
Looking for reliable AEPS White Label Software to start your own Aadhaar Enabled Payment System (AEPS) business in India? Aeps india is the right AEPS software provider is essential for launching banking services under your own company name, managing retailers and distributors, processing Aadhaar-based transactions and building a digital banking network. Whether you are a fintech startup, entrepreneur, distributor, retailer, CSC operator or an established Aeps india, white label AEPS software can help you establish your own branded Aeps platform without developing the entire technology from scratch.
Aeps India provides AEPS White Label Software solutions designed for businesses that want to launch and manage their own AEPS platform. With a white-label solution, you can establish your business identity using your own branding while managing AEPS services through a centralized admin panel, Aeps retailer portal and distributor management system. The Aeps platform designed to support business operations, transaction monitoring, commission management, wallet management and service activation.
A White Label AEPS (Aadhaar Enabled Payment System) Software is a ready-made, customizable digital Aeps banking platform that lets you launch your own branded micro-banking and financial services business without building the underlying technology, banking integrations, or NPCI certifications from scratch.
Through Aeps India’s AEPS platform, businesses can offer essential Aadhaar-enabled banking services, including cash withdrawal, cash deposit, balance enquiry, mini statement, Aadhaar-to-Aadhaar fund transfer and Aadhaar Pay API, subject to available banking and service integrations. The B2B Aeps platform can also support Micro ATM, BBPS and other digital financial services, helping businesses expand their service offerings through a single technology solution.
A reliable AEPS White Label Software solution should provide more than just a branded website or application. It should support biometric device integration, secure transaction processing, retailer and distributor onboarding, commission configuration, wallet and settlement management, transaction status tracking and detailed reports. Compatibility with supported STQC-certified Aeps biometric devices, such as Mantra is also an important consideration when selecting an AEPS india
With Aeps India, businesses can explore a white label AEPS platform with business management features, Aeps API integration and customization options. From managing retailer accounts and assigning commissions to monitoring transactions and controlling user activities, the Aeps b2b software helps organize day-to-day AEPS business operations. Businesses can also explore white-label branding and source-code options according to the selected solution and commercial agreement.
Whether you want to launch AEPS company, build a retailer network, provide Aadhaar-enabled banking services in rural and semi-urban areas or expand your existing fintech business, Aeps India can help you explore suitable AEPS software solutions according to your requirements.
Choose Aeps India to explore AEPS White Label Software and take the next step towards building your own branded Aadhaar-enabled banking services business.
In this guide, you will learn what AEPS White Label Software is, how an AEPS white-label platform works, which biometric devices are required, what banking services you can offer, how retailer and distributor management works, what features to check before purchasing AEPS software and how to choose the right AEPS software provider in India.
What is a AEPS White Label Software?
An AEPS white-label software is a ready-made digital banking platform for the Aadhaar Enabled Payment System (AEPS) that a business licenses, rebrands with its own logo, colors, and domain name, and offers to its own network of retailers, distributors, and customers.
Instead of building complex banking infrastructure, server connections, or NPCI/Aadhaar integrations from scratch, the business relies on a Aeps india for the underlying tech while controlling the brand and network locally.
AEPS White Label Software Work
An Aadhaar Enabled Payment System (AEPS) white-label software solution lets you launch your own branded digital banking and micro-ATM network (using your own company name, logo, domain, and admin panel) without building complex backend NPCI/RBI bank integrations from scratch.
How AEPS White-Label Software Works
- Core Infrastructure Provider: Aeps india manages the heavy-lifting: core Aeps bank API, NPCI compliance, server security, and multi-bank routing.
- Rebranding & Admin Panel: You license the Aeps service platform and customize it with your brand identity. You get a master Admin Panel to manage your business hierarchy (e.g., creating White Labels, Super Distributors, Distributors, and Retailers/CSPs).
- Field Operations (Retailers): Your agents or merchants use the portal or mobile app with a UIDAI-certified Aeps biometric device to process customer transactions on the ground.
- End-Customer Services: A customer visits an agent, shares their Aadhaar number and bank name, and scans their fingerprint to complete a transaction.
Why Choose AEPS White Label Software for Your Fintech Business?
Choosing an Aadhaar Enabled Payment System (AEPS) white label software allows Aeps india to launch micro-banking services quickly under their own brand name.
Key Benefits of AEPS White-Label Software
- Fast Market Deployment: Ready made white label Aeps platform can launch in weeks, bypassing 12 to 18 months of custom software development.
- Brand Ownership: Run cash withdrawals, balance inquiries, and mini-statements using your own company logo, domain, mobile Aeps app, and Aeps admin dashboard.
- Cost Efficiency: Save significant capital on building architecture, compliance audits, and maintaining backend infrastructure from scratch.
- Built-in Compliance & Security: Benefit from pre-integrated NPCI-certified workflows, multi-bank routing (for high uptime around 98–99.9%), and encrypted biometric/OTP authentication.
- Commission & Network Management: Control your merchant and distributor hierarchy, track real-time transactions, and automate payouts from a single centralized Aeps admin panel.
- Ecosystem Expansion: Easily bundle AEPS with complementary services like Domestic Money Transfers (DMT), BBPS bill payments, and mobile recharges to grow revenue streams.
Key Features of the Best AEPS White Label Software
AEPS (Aadhaar Enabled Payment System) white-label software is a ready-made, customizable Aeps bank platform that allows businesses to offer digital financial services under their own brand name, logo, and domain.
Branding & Customization
- White-Label Branding: Custom logos, color schemes, web portals, and Aeps mobile app interfaces reflecting your company’s brand.
- Custom Domain: Ability to host the Aeps portal on your own branded domain.
Network & Hierarchy Management
- Multi-Tier Structure: Aeps Admin panels that let you create and manage super distributors, distributors, and local retail agents (Business Correspondents).
- Retailer Onboarding: Digital KYC and setup tools for onboarding new agents onto your network.
- Role-Based Access Control: Separate, restricted dashboards and permissions for administrators, distributors, and retailers.
Administration & Financial Control
- Admin Dashboard: Centralized command center to monitor platform health, active users, and system logs.
- Commission Configuration: Flexible tools to set, update, and track commission structures across distributors and retailers.
- Transaction Monitoring & Status Tracking: Live tracking of transaction success, failure, or pending states with unique Request Reference Numbers (RRN).
- Automated Reconciliation & Settlement: Real-time or automated settlement systems paired with detailed audit and business reports.
Security & Compliance
- Biometric & OTP Authentication: UIDAI-compliant Aeps fingerprint or Aeps iris scanning for secure transaction verification.
- Encrypted Data Flow: End-to-end encryption for sensitive customer and banking parameters.
- Multi-Bank Routing & Auto Failover: High-uptime routing switches that automatically redirect traffic if a Aeps banking API drops.
AEPS Services Available in White Label Software
White label Aadhaar Enabled Payment System software allows businesses to offer biometric banking and financial services under their own brand name, logo, and domain.
Core AePS Services Available
- Cash Withdrawal: Biometric-authenticated cash dispensing for customers through retailers or micro ATM.
- Cash Deposit: Aadhaar-linked cash deposit facilities.
- Balance Inquiry: Real-time customer bank account balance checks using Aadhaar and fingerprint authentication.
- Mini Statement: Generation of recent transaction history and passbook summaries for customers.
- Aadhaar Pay: Merchant payment collection directly from a customer’s Aadhaar-linked bank account via biometric verification.
- Fund Transfers: Interbank or account-to-account transfers routed through NPCI-aligned workflows.
Common Bundled / Ancillary Services
Most white label AEPS platforms also include additional banking and utility services in the same B2B/B2C panel:
- Domestic Money Transfer (DMT): Instant bank-to-bank IMPS/NEFT money transfers.
- Micro ATM Services: Physical card swipe/dip transactions for debit/credit cards.
- Bharat Bill Payment System (BBPS): Electricity, water, gas, broadband, and post-paid bill payments.
- Recharges: Mobile and DTH recharges.
- Cash Management Services (CMS): EMI collection and cash drop services for NBFCs/banks.
- Travel & Other Services: Flight, bus, and train ticket bookings, plus PAN card assistance.
AEPS White Label Software for Distributors and Retailers
An AePS (Aadhaar Enabled Payment System) White Label Software lets you launch your own branded digital banking and micro ATM network without building the underlying infrastructure or managing direct NPCI/bank licensing.
How the Hierarchy Works
A white label Aeps B2B platform operates on a multi-tier structure managed via your own custom domain, logo, and brand colors:
- Master Admin / Brand Owner (You): Controls the overall best Aeps platform, sets commission slabs, manages Aeps mini statement API routing, views live transaction volumes, and creates distributor/retailer accounts.
- Distributors / Master Distributors: Aeps Onboard local merchants, manage lower-tier channel partners, and earn a cut of the transaction volume.
- Retailers / Agents: Use a web portal or Android Aeps app with a biometric device to deliver banking services to end-customers.
AEPS White Label Software Pricing in India
An AePS White-Label Software cost structure in India typically includes one-time Aeps setup fees, recurring maintenance and hosting charges, and per-transaction or commission-sharing models.
1. One-Time Setup & Deployment Costs
White label Aeps solution are pre-built platforms that allow you to run AePS business under your own brand, logo, and domain without building the core banking/NPCI infrastructure from scratch.
- Starter / Basic White-Label Portals: ₹7,999 to ₹15,000 (e.g., entry-level tiers covering basic branding, single wallets, and limited retailer counts).
- Standard / Multi-Tier White-Label Portals: ₹15,000 to ₹50,000 (includes multi-level distributor and retailer hierarchies, BBPS, money transfer/DMT, and custom subdomains/SSL).
- Enterprise / Branded App Solutions: ₹50,000 to ₹1,20,000+ (includes custom mobile apps, Aeps API access, and unlimited network levels).
- (Note: Direct bank-connected enterprise APIs without a white-label intermediary cost significantly more, ranging from ₹2.5 Lakhs to ₹4.5 Lakhs+.)
2. Ongoing & Recurring Operational Costs
Running an AePS white-label platform involves regular monthly or annual operational overhead:
- Monthly Server & Hosting Charges: ₹3,500 to ₹5,500 + GST per month (depending on network traffic and active agent limits, such as up to 150–500 retailers).
- Annual Maintenance / Technical Support: 15% to 20% of the b2b Aeps software/Aeps platform cost per year (or fixed annual maintenance contracts).
- SMS, Gateway, or Whitelabel Renewal Fees: Periodic charges for transactional SMS gateways, SSL certificates, or domain renewals (frequently bundled or billed yearly).
3. Transaction & Commission Structure
Rather than a flat Aeps software fee per transaction, AePS pricing operates on a margin- or slab-based commission system:
- Transaction Routing & Fees: Bank-to-bank routing or switch fees can range from nominal amounts up to a few rupees per transaction depending on the service (e.g., Cash Withdrawal, Balance Enquiry, Mini Statement, or Aadhaar Pay API).
- Agent & Admin Margins: Cash withdrawals or micro-ATM transactions generate commission slabs (ranging up to ₹9–₹13 per transaction depending on the volume , which are split across the admin, distributors, and retail agents.
Summary Table of Typical Costs
| Cost Component | Estimated Price Range (INR) | Frequency |
|---|---|---|
| White-Label Setup / Portal | ₹8,000 – ₹50,000+ | One-Time |
| Server & Cloud Hosting | ₹3,500 – ₹5,500 / month | Monthly |
| Annual Maintenance (AMC) | 15% – 20% of base cost | Yearly |
| Transaction / Slabs | Variable (₹0.25 to ₹10 routing / slab-based margins) | Per Transaction |
Documents Required to Start an AEPS White Label Business
To start an AEPS (Aadhaar Enabled Payment System) White Label Business in India, you need to submit corporate, financial, and personal KYC documentation to Aeps india.
1. Company & Business Entity Proofs
If you are registering as a Private Limited Company, LLP, or Partnership Firm, you must provide core incorporation and legal records:
- Certificate of Incorporation / Partnership Deed / LLP Agreement
- Memorandum of Association (MOA) and Articles of Association (AOA) (for companies)
- Board Resolution (a formal resolution passed by the board authorizing the best Aeps setup of the white label Aeps portal/service)
- Company PAN Card
- GST Registration Certificate (if applicable/requested by the Aeps india)
2. Director / Promoter / Partner KYC Documents
Personal identification records are required for all directors, owners, or authorized signatories:
- Photo ID Proof: Aadhaar Card, Voter ID, Passport, or Driving License
- PAN Card of all directors/promoters
- Passport-sized Photographs
- Digital Signature Certificate (DSC) (often required for company-level agreements or specific Aeps balance inquiry API/white-label Aeps onboarding)
3. Business & Office Address Proofs
Proof of the physical location or registered office of your business entity:
- Office Address Proof: Electricity bill, property tax receipt, or valid rent/lease agreement
- Business Registration Proof: Shop & Establishment License, MSME (Udyam) Registration, or trade license
4. Banking & Financial Documents
To manage settlements, commission payouts, and operational liquidity for your white label Aeps network:
- Cancelled Cheque, Bank Statement, or Bank Memo of the current/working account in the name of the company or firm.
AEPS White Label Software Development Process
An Aadhaar Enabled Payment System (AePS) white label Aeps software development and deployment process allows a business to launch branded banking and financial services (such as cash withdrawals, balance inquiries, and mini-statements) using an existing core infrastructure.
Step-by-Step White Label AePS Development & Launch Process
1. Requirement Analysis & Planning
- Define Business Model: Decide your hierarchy structure (Super Distributor → Distributor → Retailer/Merchant network).
- Branding & UI Scope: Finalize your company name, logo, color palette, mobile app theme, and custom domain/subdomain requirements.
- Select Services: Choose which services to bundle alongside AePS (e.g., Domestic Money Transfer [DMT], Bharat BillPay [BBPS], mobile/DTH recharges, or micro-ATMs).
2. Documentation & Compliance Verification
- KYC & Legal Papers: Submit corporate and personal KYC documents to Aeps india to align with NPCI and banking partner guidelines.
- Required Documents typically include: Company incorporation certificate, GST registration, PAN card, Aadhaar/PAN of directors, and cancelled cheque.
3. Software Customization & White-Label Branding
- Portal & App Rebranding: The Aeps india configures the master Aeps admin panel, distributor panels, and retailer login interfaces with your brand identity.
- Commission & Slab Configuration: Set up custom Aeps commission structures, surcharge rules, and real-time payout/settlement cycles for your network.
4. API & Banking Integration
- Core Banking / Switch Integration: The Aeps earning platform connects to underlying AePS switches, multi-bank routing engines, and biometric authentication modules (supporting L0/L1 fingerprint or Aeps iris scanner device).
- Failover Setup: Configuring auto-routing or failover mechanisms to switch banks seamlessly if a specific Aeps banking API drops.
5. Testing & Security Implementation
- Security Measures: Implementation of role-based access control (RBAC), end-to-end encryption, multi-factor authentication, and audit logs to meet compliance (such as ISO standards).
- Workflow Testing: Test biometric capture, mock cash-withdrawal/balance check flows, transaction status tracking (success, pending, failed), and wallet/ledger reconciliation.
6. Deployment & Network Onboarding
- Server & Cloud Setup: Deploy the b2b Aeps portal on secure cloud servers (with regular maintenance and database backups).
- Activate Network: Start Aeps onboarded your distributors and merchants, assign member IDs, distribute certified Aeps biometric scanner device settings, and go live.
7. Ongoing Maintenance & Support
- Monitor uptime, resolve gateway or transaction drops, apply compliance patches, and scale server resources as transaction volumes grow.
Security and Compliance in AEPS White Label Software
Security and compliance form the structural backbone of any Aadhaar Enabled Payment System (AePS) white-label software, as these Aeps platforms handle sensitive biometric data, Aadhaar numbers, and live banking transactions under strict regulatory oversight in India.
Core Regulatory & Statutory Compliance
AePS infrastructure operates under the purview of apex financial and data protection bodies:
- NPCI (National Payments Corporation of India) Guidelines: All best white label Aadhaar Enabled Payment System platform must route transactions through NPCI-approved banking rails, adhering to standardized messaging, settlement, and security protocols.
- RBI (Reserve Bank of India) Mandates: Best Aeps Software must conform to RBI’s regulatory frameworks for micro-banking, digital payment intermediaries, and customer grievance redressal.
- DPDPA (Digital Personal Data Protection Act): Compliance with data privacy laws requires explicit consent mechanisms, minimal data retention, and strict processing boundaries for biometric and demographic details.
- UIDAI Security Standards: Biometric capture (fingerprint/IRIS) must comply with UIDAI-certified L0/L1 RD (Registered Device) specifications to prevent spoofing or storing raw biometric images.
Technical Security & Data Protection Measures
Aeps india and operators must implement multi-layered defenses across the software architecture:
- End-to-End (E2E) & 256-bit Encryption: All data in transit and at rest including transaction requests, authentication payloads, and database records must use strong cryptographic standards (such as 256-bit encryption).
- Tokenization of Sensitive Data: Aadhaar numbers, bank account numbers, and personal identifiers must be tokenized or masked within logs and system interfaces to prevent internal or external exposure.
- API Security & Rate Limiting: Exclusively authenticated, signed secure Aeps API must be deployed with strict rate-limiting, IP-whitelisting, and automated auditing to block brute-force or injection attacks.
- Hierarchical Role-Based Access Control (RBAC): Granular permissions must govern the admin hierarchy ranging from Admin, Master White Label, and Super Distributors to Retailers/CSPs ensuring users only access data relevant to their tier.
- Multi-Factor Authentication (MFA) & Fallbacks: While biometric verification serves as the primary authentication step, secondary checks (such as OTP or PIN validations) add resilience during fallback or high-risk scenarios.
Fraud Prevention & Real-Time Monitoring
- Automated Audit Trails: Every transaction generates an immutable, timestamped log capturing device IDs, IP addresses, agent IDs, and biometric capture metadata.
- Anomaly & Risk Detection: Real-time monitoring tools flag suspicious patterns, such as repeated failed biometric attempts, velocity spikes, or unusual transaction volumes from a single CSP terminal.
- Auto-Settlement & Reconciliation: Automated backend reconciliations minimize manual intervention and human error, reducing leakage and settlement delays.
How to Choose the Best AEPS White Label Software Provider
Aeps india one of the best AEPS white label software provider requires evaluating several core technical, financial, and compliance factors. A white label Aeps software solution lets you launch a branded digital banking and micro ATM platform without building the backend infrastructure from scratch.
Key Factors to Evaluate
Transaction Success Rate & Uptime:
- Aeps india with high transaction reliability, multi-bank routing, and minimal server downtime so agent transactions do not fail during peak hours.
Security & Compliance:
- Ensure Aeps commission platform complies with UIDAI guidelines, RBI norms, and strong bank-level encryption, multi-factor authentication (2FA), and secure biometric (fingerprint/iris) device compatibility (such as Mantra).
White-Label Branding & Customization:
- Verify what is included: branded web portals, custom Android/iOS mobile Aeps apps, Aeps admin dashboards, retailer/distributor logins, and wallet management tools under your own logo and domain.
Settlement Speed & Payout Cycles:
- Check how fast transaction settlements and commission payouts happen (real-time automated wallet settlements vs. T+1 or manual cycles).
Supported Banking Services:
- Aadhaar Enabled Payment System API/software supports essential services like cash withdrawals, balance inquiries, mini statements, Aadhaar Pay, Domestic Money Transfer (DMT), Bharat Bill Payment System (BBPS), micro-ATMs, and recharges.
Transparent Pricing & Cost Structure:
- Review upfront setup costs (typically ranging from ₹15,000 to over ₹1 Lakh in the Indian market), ongoing maintenance fees, and per-transaction or Aeps Cash Withdrawal API charges. Avoid hidden charges.
Technical Support & Documentation:
- Aeps india offers reliable 24/7 technical assistance, Aeps API documentation, sandbox testing environments, and help with issue resolution.
Scalability & Multi-Tier Management:
- Check if the modern Aeps payment platform can handle a growing network of distributors, retailers, and high transaction volumes without lagging.
AEPS White Label Software vs Custom AEPS Software
An AEPS service software powers biometric banking transactions (such as cash withdrawals, balance inquiries, and mini statements). Choosing between a White Label AEPS Software and a Custom AEPS Software depends on your launch timeline, budget, and control requirements.
AEPS White Label Software
A White Label AEPS app solution is a pre-built, ready-made digital banking platform provided by a Aeps india that you rebrand with your own logo, color scheme, and company name.
- Launch Speed: Fast (can go live in days or a few weeks).
- Initial Cost: Lower, making it ideal for startups, small businesses, and new B2B fintech ventures.
- Features & Architecture: Pre-packaged with standard admin, distributor, and retailer/CSP (Customer Service Point) panels, wallet systems, and pre-integrated Aeps banking API.
- Customization: Limited to visual branding (logo, UI colors, and domain name); you cannot heavily alter the core engine or underlying architecture.
- Maintenance & Support: Handled largely by the Aeps india.
- Best For: Entrepreneurs and startups wanting quick market entry with minimal technical overhead.
Custom AEPS Software
Custom b2b AEPS software is built from the ground up (or heavily architected via bespoke code) specifically for your business requirements.
- Launch Speed: Slower (takes months of planning, development, compliance checks, and run Aeps Fund Transfer API testing).
- Initial Cost: High, requiring dedicated Aeps development and security investment.
- Features & Architecture: Tailor-made workflows, unique commission structures, proprietary security layers, and direct custom bank/NPCI/UIDAI integrations.
- Customization: 100% customizable; you own and control the full source code and roadmap.
- Maintenance & Support: Requires an in-house or dedicated external tech team.
- Best For: Large enterprises, established financial institutions, or scaling businesses with specific compliance and workflow demands.
| Feature / Aspect | White Label AEPS Software | Custom AEPS Software |
|---|---|---|
| Definition | Ready-made, pre-built AEPS platform rebranded with your logo, domain, and company identity. | Built completely from scratch (or tailored from core code) specifically to your unique business logic and architecture. |
| Development & Launch Time | Fast (can go live in a few days to a couple of weeks). | Slow / Long (takes several weeks or months of design, coding, testing, and compliance flow). |
| Initial Cost | Affordable / Lower budget (subscription, setup fee, or revenue/commission share model). | High / Expensive (requires dedicated development teams, architects, and custom-built modules). |
| Branding & UI Customization | Limited to logo, color scheme, company name, and basic web/app wrapper. | 100% Tailored; complete freedom over UI/UX design, custom workflows, and exclusive features. |
| Source Code Ownership | Usually not owned by you (you lease/license the platform or white-label service). | Full Ownership of the source code and intellectual property (IP). |
| API & Bank Integrations | Pre-integrated with the Aeps india existing banking APIs, switch, and NPCI/UIDAI routing. | Custom API integrations with multiple banks, payment switches, or specialized third-party services of your choice. |
| Maintenance & Updates | Handled by the Aeps india (bug fixes, security patches, NPCI updates). | Your responsibility (or requires an ongoing retainer/contract with a development agency). |
| Scalability & Control | Scalable within the limits and feature sets provided by the vendor. | Highly scalable and structurally flexible to accommodate custom business models or high-volume enterprise demands. |
| Best Suited For | Startups, local distributors, and entrepreneurs wanting a quick, low-cost entry into digital banking. | Established fintech companies or enterprises needing proprietary workflows, unique compliance setups, or custom integrations. |
AEPS White Label Software vs AEPS API
Choosing between an AEPS White Label Software (or White Label Portal) and an best AEPS API depends on whether you want a turnkey, ready-to-launch Aeps business platform or a flexible building block to integrate into your existing tech stack.
1. What is an AEPS API?
An Aadhaar Enabled Payment System (AEPS) API is a set of backend programming hooks/protocols provided by Aeps india.
- How it works: You write your own front-end code (mobile app, web portal, or custom aeps b2b software) and plug the AEPS Cash Deposit API into your servers to process transactions like cash withdrawals, balance inquiries, and mini statements.
- Who it is for: Established Aeps software companies, large enterprises, or fintech startups with an in-house Aeps commission app development team that already has a Aeps earning platform (like a multi-service wallet or ERP) and just needs raw banking transaction capabilities.
- Level of Control: Maximum. You control the UI, UX, user journey, database, and how services are structured.
- Development Effort: High. You must build Aeps admin panel, retailer/merchant onboarding flow, eKYC modules, and compliance reporting yourself.
2. What is AEPS White Label Software?
White Label AEPS Software is a complete, pre-built, ready-to-use B2B or B2C Aeps banking platform provided by Aeps india, branded with your company’s name, logo, domain, and colors.
- How it works: The vendor manages the heavy lifting hosting, backend banking/fast Aeps API integrate, and security maintenance while you log into an admin panel to create your own network of Super Distributors, Distributors, and Retailers/Agents.
- Who it is for: Entrepreneurs, startup founders, and regional business owners who want to launch a branded financial services or micro-ATM/AEPS company quickly without hiring Aeps software development team.
- Level of Control: Moderate. You control the branding, margins, commissions, and agent network, but you rely on the vendor for core system updates and bug fixes.
- Development Effort: Very Low. Usually deployed within days; configuration involves setting up your domain, payment gateway/Aeps wallet, and commission slabs.
Key Comparison at a Glance
| Feature | AEPS White Label Software | AEPS API |
|---|---|---|
| Product Form | Turnkey, ready-made portal + app + admin panel | Raw backend endpoints/code snippets |
| Branding | Custom logo, domain, mobile app, and theme in your name | Hidden inside your custom-built application |
| Tech Skills Needed | Minimal (basic admin configuration) | High (full-stack developers required) |
| Time to Market | Fast (days to a couple of weeks) | Slower (weeks to months of development & testing) |
| Network Management | Built-in multi-level hierarchy (Admin -> Distributor -> Retailer) | You must build your own agent management system |
| Cost Structure | Setup fee + monthly/yearly maintenance or hosting (e.g., ₹3,500–₹5,500/mo) + per-transaction or slab costs | API integration fee + per-hit/transaction pricing model |
Common AEPS White Label Software Transaction Problems and Their Solutions
Running an Aadhaar Enabled Payment System (AEPS) white label software platform involves managing multi-tiered networks (admin, distributors, and retailers) where transaction failures can stem from biometric issues, bank server drops, or connectivity glitches.
Common AEPS White-Label Transaction Problems & Solutions
1. Biometric Authentication Failures
- Causes: Worn or dry fingerprints, dirty/smudged scanner glass, unregistered or outdated Registered Device (RD) services, or a poor-quality USB/OTG biometric scanner.
Solutions:
- Clean the scanner glass and ask the customer to wipe or moisten their finger; try an alternate finger (e.g., thumb vs. index).
- Ensure the agent’s device driver and RD Service are updated to the latest version.
- Re-register the biometric device on the respective manufacturer app if flagged as unverified.
2. Aadhaar Not Linked to Bank Account (Seed Mismatch)
- Causes: The customer’s Aadhaar number is active in UIDAI records, but it has not been mapped (seeded) with the specific bank account they are trying to access.
Solutions:
- Inform the customer that their Aadhaar is not linked to that particular bank account.
- Direct the customer to visit their bank branch or use net banking to complete Aadhaar-to-bank seeding and NPCI mapping before attempting another withdrawal.
3. Insufficient Balance or Limit Exceeded (Error Code 51)
- Causes: Low account balance, or the customer attempting to exceed daily or single-transaction limits (typically capped at ₹10,000 per transaction or a monthly cumulative ceiling).
Solutions:
- Train retailers to run a quick Balance Inquiry or Mini Statement first before processing a cash withdrawal.
- Check the High volume Aeps software logs to see if the customer has already exhausted their daily/monthly AEPS limit across other banking points.
4. Issuer / Bank Switch Inoperative & Server Timeouts
- Causes: Bank-specific server downtime, NPCI/UIDAI technical drops, or slow Aeps API response times from the white-label backend.
Solutions:
- White label Aeps platform features multi-bank routing and auto-failover to switch traffic to healthy bank switches automatically.
- Instruct agents to wait a few minutes before retrying rather than spamming the same transaction, which can lock the customer’s biometric profile or trigger temporary security blocks.
- Make sure Aeps admin panel clearly categorizes whether the error is local, network-based, or at the issuer bank level.
5. Account Frozen, Dormant, or Closed
- Causes: The bank account has been marked dormant due to inactivity, locked due to KYC non-compliance, or frozen by cybercrime/regulatory authorities.
Solutions:
- Top AEPS software translates error codes accurately rather than showing a generic “Software Glitch” message.
- Guide the customer to check with their home bank branch to reactivate or update KYC on the frozen/dormant account.
6. Money Debited from Customer Account, But Transaction Fails/Pending
- Causes: A disconnect between the issuer bank, NPCI switch, and the white-label wallet/Aeps settlement API during peak loads.
Solutions:
- Check your white-label portal’s Real-Time Reconciliation and auto-settlement logs.
- If the amount is stuck, check if it auto-reverses within T+0/T+1 banking cycles. If not, guide the user or file a ticket via the NPCI Consumer Complaints Portal or the RBI Integrated Ombudsman.
Why Our AEPS White Label Software Is Different
A White Label AEPS (Aadhaar Enabled Payment System) software lets your business launch branded digital banking and micro-ATM services (such as cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay) under your own company logo and domain without building the tech stack from scratch.
What makes a high-quality or distinct White Label AEPS platform stand out from generic or poorly built alternatives usually boils down to several core differentiators:
1. Architecture & Compliance
- NPCI & RBI Alignment: Built with strict compliance protocols, real-time transaction reconciliation, and secure 256-bit encryption for biometric data capture.
- Multi-Bank Routing & Auto Failover: Intelligent switching across multiple underlying bank APIs so that if one bank’s server faces downtime, transactions automatically route through a working partner bank to maintain high uptime (often 99.9%+).
2. Hierarchical Control & Network Management
- Multi-Tier Role Management: Comprehensive admin panels that allow you to create and manage unlimited or structured tiers—such as Master White Labels, Super Distributors, Distributors, and Retailers/CSPs (Customer Service Points).
- Granular Commission Controls: Flexible backend settings to customize and automate commission structures, slabs, and profit margins for every level of your distribution network.
3. Settlement & Liquidity Speed
- Real-Time / Instant Settlement: Immediate transaction processing and quick payout or wallet-to-bank settlement cycles to keep retailers and agents liquid.
- Virtual Balance Management: Ability for master admins and master white-labels to manage wallet ledgers, credit/debit adjustments, and live cash flows transparently.
4. Branding & Ecosystem Integration
- True Rebranding: Customization that goes beyond just changing a logo—including branded web portals, white-labeled Android/iOS apps (often listed on the Google Play Store), custom SMS/SMTP gateways, and bespoke UI colors.
- Value-Added Services (VAS): Beyond basic AEPS, a differentiated platform bundles Domestic Money Transfer (DMT), BBPS utility bill payments, mobile recharges, micro-loans, CMS, and travel bookings into the same ecosystem.
Why Choose Aeps india for AEPS White Label Software Solution
Aeps india only one of the right provider for an Aadhaar-enabled Payment System (AePS) White Label Software Solution requires evaluating key technical, regulatory, and business metrics to ensure smooth, secure, and profitable operations.
Key Factors to Evaluate
1. Regulatory Compliance & Security
- NPCI & RBI Guidelines: Aeps india strictly adheres to NPCI and Reserve Bank of India mandates for Aadhaar data safety and authentication.
- Encryption & Data Protection: Look for end-to-end data encryption, secure server architecture, multi-factor authentication, and safe biometric device integration (such as Mantra).
- Authorization & Liability: Clarify the legal boundaries and responsibilities regarding compliance, online Aeps API routing, and transaction disputes between your brand and the Aeps india.
2. Transaction Success Rate & Uptime
- High Uptime: Aeps india should promise high Aeps API uptime (ideally 99.9% or higher) to prevent service dropouts for your retailers.
- Multi-Bank Routing: High volume Aeps Platform that support multi-bank fallback routing automatically shift transactions to alternative bank gateways if one bank’s server faces downtime, maximizing your transaction success rate.
3. White-Label Customization & Control
- Branded Interface: Confirm what elements carry your custom branding including the web portal, Android/iOS mobile Aeps apps, admin dashboard, retailer/distributor panels, and receipt layouts.
- Admin & Wallet Management: Ensure the super Aeps admin panel grants you full control over retailer/distributor onboarding, wallet limits, commission slabs, and ledger tracking.
4. Commission Structure & Settlement Cycles
- Real-Time Settlements: Check whether wallet settlements, payouts, and commission distributions happen on an automated, real-time basis or on fixed daily cycles.
- Margin Viability: Compare the Aeps commission margins offered per cash withdrawal, balance inquiry, mini statement, and Aadhaar Pay transaction to ensure your business model stays profitable.
5. Scalability & Technical Infrastructure
- Load Capacity: The leading Aeps platform must comfortably scale as your network grows from dozens to thousands of active retailers and high-volume daily hits.
- Developer Documentation & Sandbox: Aeps india offering a Aeps developer-friendly sandbox environment let you test Aeps API, webhook responses, and error handling before going live.
6. Support & Training
- Technical Assistance: Look for reliable 24/7 or dedicated technical support to resolve stuck transactions, biometric device sync errors, or banking server failures immediately.
- Onboarding & Training Material: Aeps india provides operational manuals, training guides, and Aeps API integrated assistance.
Conclusion – Launch Your Own AEPS Business Today
Choosing the right AEPS White Label Software is an important step for businesses that want to establish their own Aadhaar Enabled Payment System (AEPS) platform and offer digital banking services under their own brand name. A reliable white-label solution should provide more than basic transaction processing. It should help you manage retailers and distributors, integrate biometric devices, monitor banking transactions, configure commissions and control daily business operations through a centralized platform.
A White Label AEPS (Aadhaar Enabled Payment System) Software is a ready-made, customizable digital banking platform that allows you to launch your own branded micro-banking and financial services business without building the complex backend infrastructure or obtaining direct NPCI/UIDAI certifications yourself.
Aeps India provides AEPS White Label Software solutions designed for fintech startups, entrepreneurs, distributors, retailers and businesses planning to enter the digital banking services industry. With a white-label platform, you can establish your own business identity and manage AEPS operations through an admin panel and retailer-distributor network. Depending on your selected solution, you can also explore branding, customization and source-code options.
Through Aeps India’s AEPS platform, businesses can offer essential Aadhaar-enabled banking services, including cash withdrawal, cash deposit, balance enquiry, mini statement, Aadhaar-to-Aadhaar fund transfer and Aadhaar Pay, subject to available banking integrations and service approvals. Biometric device integration with compatible STQC-certified Aeps devices, including supported Mantra, Morpho, Startek and Cogent models, helps facilitate Aadhaar-based authentication.
A complete AEPS White Label Software solution should also support important business operations such as retailer onboarding, distributor management, wallet management, commission configuration, transaction monitoring, settlement tracking and detailed reporting. These features help business owners organize their service network, monitor transaction activities and manage their operations more effectively.
Before selecting an Aeps india, compare important factors such as available banking integrations, biometric device compatibility, transaction success and status-handling processes, security measures fast Aeps onboarding requirements, pricing, technical support and customization options. Also verify the applicable banking partner arrangements, service approvals and compliance responsibilities before launching your platform.
Whether you want to start AEPS company, launch a branded Aeps banking portal, build a retailer and distributor network or expand your existing fintech business, Aeps India can help you explore an AEPS software solution according to your business requirements.
Contact Aeps India today to discuss your requirements, explore AEPS White Label Software features and request a platform demonstration. Take the next step towards building your own branded AEPS business and offering Aadhaar-enabled banking services through a professionally managed technology platform.
AEPS White Label Software with Aeps India
Looking to launch your own AEPS business with a branded platform? Explore AEPS White Label Software with Aeps India for business branding, retailer management, AEPS API integration and administrative controls. Contact our team to discuss software features, setup, customization and pricing based on your business requirements.
AEPS Portal Setup Guide for Business Owners and Agents
Biometric AEPS API: Complete Guide
AEPS Application: Complete Guide for Retailers and Businesses
About Author

