AEPS Service Solution: Features, Benefits & Complete Guide
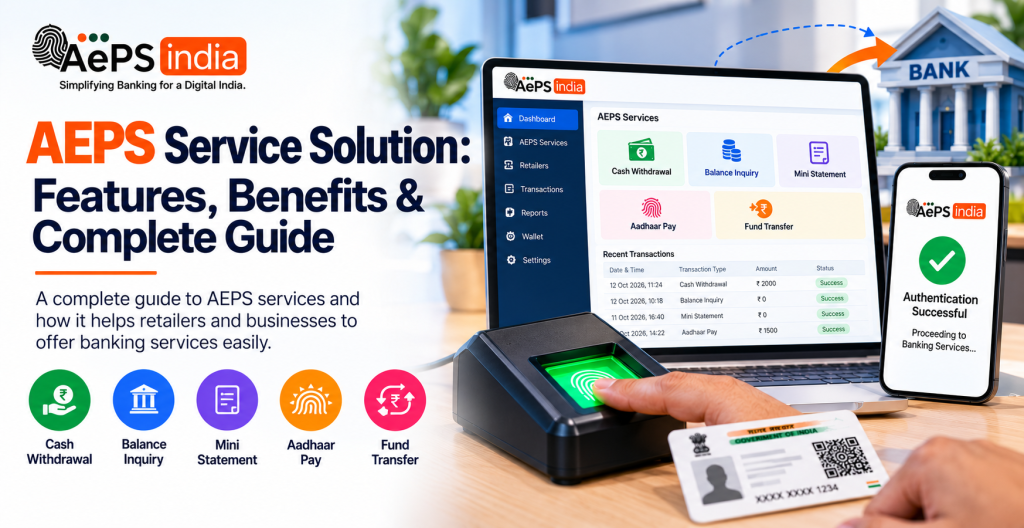
An AEPS Service Solution helps businesses provide Aadhaar Enabled Payment System (AEPS) services through compatible software, authorized banking partners, and supported biometric devices. It enables eligible customers to access selected banking services through participating agents using Aadhaar-based authentication. For fintech startups, retailers, distributors, and digital service center operators, choosing the right AEPS Service Solution is important for managing transactions, supporting customers, and building a reliable digital banking service business.
An AEPS Service Solution is a technology platform that connects supported Aadhaar-based banking transactions with an authorized Aeps india and the relevant banking infrastructure. Depending on the Aeps india, integration, and bank-supported services, it may offer cash withdrawal, balance enquiry, mini statement, and other eligible AEPS transaction types. Available services can vary, so businesses should confirm the exact functionality before Aeps onboarding.
An Aadhaar Enabled Payment System (AePS) is a bank-led model by the NPCI that allows cardless, PIN-free banking through biometric authentication (fingerprint or iris scan) and an Aadhaar number. Popular service solutions like Aeps india let local merchants act as mini-bank branches.
A suitable AEPS platform may include an Aeps admin panel, retailer and distributor management, transaction history, status tracking, commission management, settlement records, and transaction reports. Aeps Biometric device compatibility, secure authentication, reliable transaction-status updates, and clear procedures for handling failed or pending transactions are also important when evaluating a solution.
Before selecting an Aeps india, businesses should assess the onboarding process, supported banks and services, Aeps API integration options, device compatibility, pricing structure, technical support, reporting tools, and security practices. They should also verify the Aeps india authorization and applicable compliance requirements. A well-planned Aeps setup can help businesses manage daily operations more effectively while providing customers with a clearer and more consistent service experience.
Aeps India offers a point of contact for businesses exploring AEPS software, API integration, and digital banking service solutions. Whether you are planning to start AEPS business, expand an existing retailer network, or integrate AEPS functionality into a Aeps fintech platform, identify your business model and required services before choosing the appropriate solution.
In this guide, we explain how an AEPS Service Solution works, its key features, supported banking services, business benefits, integration requirements, and the factors to consider when selecting a provider. This information can help you compare available options and plan a solution that fits your operational needs.
Ready to discuss your requirements? Contact Aeps India to explore the available AEPS service and integration options for your business.
What is an AEPS Service Solution?
An Aadhaar Enabled Payment System (AePS) Service Solution is a bank-led digital Aeps platform developed by the NPCI and Digital India that turns local retail shops and micro-ATMs into neighborhood mini-banks. It lets customers perform cardless and PIN-free banking transactions using just their 12-digit Aadhaar number and biometric authentication (fingerprint or iris scan).
How Does an AEPS Service Solution Work?
The Aadhaar Enabled Payment System (AePS) is a bank-led model by the NPCI that allows customers to perform cardless, PIN-free financial transactions such as cash withdrawals, balance inquiries, and mini statements using just their Aadhaar number and biometric authentication at a Aeps india.
How the AEPS Work Process Functions
- Visit Outlet: The customer visits an authorized Aeps india.
- Share Details: The customer provides their 12-digit Aadhaar number, names their linked bank, and selects the required service (cash withdrawal, balance check, etc.).
- Biometric Scan: The customer places their finger or thumb on a Aeps biometric scanner (or undergoes iris/face scan) connected to the agent’s device.
- Real-Time Verification: The Aeps system authenticates the biometric data via UIDAI and the bank’s core banking system, completing the transaction instantly.
Banking Services Available Through an AEPS Solution
An Aadhaar Enabled Payment System solution provides cardless, PINless, and paperless basic banking services through Business Correspondents (BCs), micro-ATMs, or banking apps using Aadhaar numbers and biometric authentication (fingerprint or iris scan).
Available Banking Services
- Cash Withdrawal: Withdraw money from an Aadhaar-linked bank account at a local agent or micro-ATM.
- Cash Deposit: Deposit cash into a supported bank account through an authorized touchpoint (subject to bank availability).
- Balance Enquiry: Check the real-time available balance of a linked bank account.
- Mini Statement: View a short summary of recent transactions.
- Aadhaar-to-Aadhaar Fund Transfer: Transfer money between two Aadhaar-linked bank accounts.
- BHIM Aadhaar Pay: Make merchant or retail payments directly from a bank account using biometric verification.
- Yes/No Authentication: Verify an account holder’s identity via Aadhaar without exposing sensitive financial details.
- Dual Authentication: Perform higher-security verification steps where required by specific financial workflows.
- Direct Benefit Transfers (DBT): Access government subsidies, pensions, and MNREGA wages credited to Aadhaar-enabled accounts.
AEPS Service Solution Requirements in India
To start Aadhaar Enabled Payment System business in India, an agent needs to be at least 18 years old, possess an Aadhaar-linked bank account, submit KYC documents (Aadhaar, PAN, and address proof), use a smartphone, PC, or POS device, and connect a STQC-certified L1 Aeps biometric fingerprint scanner.
Eligibility & Personal Requirements
- Age: Minimum 18 years old.
- Technical Knowledge: Basic familiarity with online banking portals and digital transactions.
- Mobile & Email: An active mobile number strictly linked to the applicant’s Aadhaar, plus a working email ID.
Mandatory Documents Checklist
- Identity & Address Proof: Aadhaar Card and PAN Card (PAN is mandatory for financial and tax compliance).
- Bank Details: Savings or current bank account details verified via a cancelled cheque or passbook (linked with Aadhaar).
- Business/Shop Proof: Passport-size photographs, utility bills for address proof, and business registration documents (such as a Shop & Establishment or Udyam Certificate, if applicable).
Hardware & Software Requirements
- Biometric Device: A UIDAI- and STQC-certified L1 Aeps fingerprint scanner (or iris scanner).
- Device/Terminal: A smartphone, tablet, or Windows PC with a stable internet connection.
- Application/Portal: Aeps Retailer software or mobile Aeps app provided by an authorized Aeps India.
Who Can AEPS Service Solution
An AePS solution can be used by any Indian resident with an Aadhaar-linked bank account as a customer, or by retailers, local shopkeepers, and Business Correspondents (BCs) who want to operate micro-banking touchpoints.
Who Can Use AePS as a Customer?
- Bank Account Holders: Any individual in India who has an active bank account linked with their Aadhaar number (Aadhaar Enabled Bank Account).
- Rural & Unbanked Citizens: People who need basic banking access without carrying debit cards, remembering PINs, or visiting distant bank branches.
- Beneficiaries: Citizens receiving direct benefit transfers (DBT), such as MNREGA wages or social security pensions.
Why Use AEPS Service Solution
An Best AePS solution allows users to perform cardless, PIN-free banking transactions such as cash withdrawals, deposits, balance checks, and fund transfers using only their Aadhaar number and biometric authentication (Aeps fingerprint or Aeps iris scan) at Aeps india.
Key Benefits for Users
- Cardless and PIN-Free: Eliminates the need to carry physical debit cards, remember ATM PINs, or worry about card loss or skimming.
- Last-Mile Rural Access: Brings essential banking services directly to remote and unbanked villages through local agents, avoiding long trips to bank branches.
- High Biometric Security: Uses unique fingerprint or iris verification matched via UIDAI, reducing identity fraud compared to traditional paper-based methods.
- Government Benefit Transfers (DBT): Facilitates direct receipt of welfare funds, pensions, and MNREGA wages straight into Aadhaar-linked bank accounts.
- Interoperability: Works across different participating banks, letting you access your bank account from any authorized AePS micro ATM or agent regardless of the bank they represent.
Key Benefits for Retailers & Business Owners
- Extra Income: Shop owners and local agents earn attractive tiered commissions on every cash withdrawal, balance check, or transaction they process.
- Low Setup Cost: Requires minimal hardware just a smartphone, a certified Aeps biometric scanner device, and an agent app making it easy to launch.
- Higher Customer Footfall: Offering basic banking services draws more people into local retail stores, boosting core business sales.
AEPS Service Solution for Distributors and Fintech Businesses
An Top AePS solution allows distributors and fintech businesses to turn local storefronts into mini-banks. It enables core banking services such as cash withdrawals, balance inquiries, and mini-statements using Aadhaar numbers and L1-compliant biometric authentication via NPCI infrastructure.
Core Solutions for Distributors & Fintechs
- White-Label & Admin Panels: Centralized Aeps portal let fintechs and master distributors build and manage multi-tier networks of sub-distributors, master agents, and local retailers.
- AEPS API Integration: Plug and play Aeps API connect your b2b Aeps platform directly to bank switching hubs and NPCI servers for real-time transaction processing.
- Wallet & Commission Management: Automated ledger systems track distributor margins, retailer commissions (ranging up to ₹15–₹16 per transaction with Aeps india), and instant or T+0 fund settlements.
- Biometric Device Support: Compatibility with STQC-certified L1 Aeps fingerprint device and Aeps IRIS scanner device (such as Mantra).
Key Features of an AEPS Service Solution
Aeps india is an trusted AePS solution allows cardless and PIN-less banking using Aadhaar numbers and biometric authentication (fingerprints or iris scans). Key features include cash withdrawals, balance inquiries, mini statements, fund transfers, and merchant payments via Business Correspondents (BCs).
Security & Authentication
- Biometric Verification: Uses Aeps fingerprint system or Aeps iris scan system via UIDAI/NPCI gateways, eliminating physical debit cards or PINs.
- Best Finger Detection (BFD): Automatically selects the optimal finger scan to reduce failed login attempts.
- No Sensitive Data Exposure: Customers do not need to share full banking credentials with local operators.
Platform & Software Features
- Interoperability: Works across different participating banks regardless of where the agent’s terminal is hosted.
- Merchant & Retailer Tools: Powers micro-ATMs, mobile Aeps portal, and BHIM Aadhaar Pay for small shop owners.
- Real-Time Settlement: Aeps india offers instant transaction processing and automated dispute/refund handling through the fast AEPS Portal.
Benefits of Using an AEPS Service Solution
The Aadhaar Enabled Payment System (AePS) is a bank-led model managed by the NPCI that allows cardless, PIN-free financial transactions using an Aadhaar number and biometric authentication (Aeps fingerprint hardware or Aeps iris scan hardware) via Aeps india.
Key Benefits for Customers
- Cardless & PIN-Free Banking: Users do not need a debit card, credit card, or secret PIN to access their bank funds.
- Last-Mile Financial Inclusion: Villagers and unbanked populations can perform banking at local Kirana stores without traveling to distant bank branches.
- Direct Benefit Transfers (DBT): Government pensions, MNREGA wages, and subsidies flow directly into Aadhaar-linked accounts safely.
- Interoperable Services: Any customer can use any bank’s AePS touchpoint regardless of which bank holds their account.
Benefits for Retailers & Business Solutions
- Low Setup Cost: Retailers only need a smartphone or best micro ATM device paired with a certified biometric scanner.
- Increased Footfall: Local shops attract more neighborhood visitors looking for quick cash services.
- Commission Earnings: Store owners earn a tiered commission on every successful cash withdrawal or banking request they process.
Aeps Service Implementation Process
Implementing Aeps service as a retailer or business involves choosing a Aeps india, completing KYC verification, acquiring a certified biometric device, and integrating the platform to start processing customer banking transactions.
Step-by-Step Implementation Process
- Choose an AePS Provider: Select a registered AePS India that offers stable uptime, High Aeps commission structures, and multi-bank support.
- Agent Registration & KYC: Fill out the online Aeps registration form with your business/personal details and submit required KYC documents, including your Aadhaar card, PAN card, active bank account details, and a passport-sized photograph.
- Acquire a Biometric Scanner: Purchase a UIDAI-certified Aeps fingerprint or certified Aeps iris scanner (such as Mantra) and register its Registered Device (RD) service with Aeps app or Aeps service portal.
- System & App Setup: Download the Aeps merchant application onto an Android smartphone or computer, or integrate their TOP AePS API directly into your existing B2B Aeps software infrastructure.
- Login & Verification: Log in using your approved Aeps Agent ID and complete a first-time Aeps biometric verification to activate Aeps merchant wallet.
Aeps Service Solution Cost
The AePS Service Solution cost structure involves Best Aeps setup/best Aeps API integration fees ranging from ₹15,000 for white label Aeps solution up to ₹4,500,000+ for direct Aeps bank API, alongside per-transaction charges, bank routing fees (approx. ₹10–₹20), and Aeps agent commission slabs of ₹2 to ₹20+ per transaction.
Setup and Technology Pricing Models
- White-Label API Solution: ₹15,000 – ₹30,000; built for startups needing custom branding via a parent-banking license.
- Direct Bank API Integration: ₹2,500,000 – ₹4,500,000+; built for large-scale fintechs connecting directly with partner banks like ICICI or Yes Bank.
- White-Label Software / Admin Panel: ₹1,49,000 – ₹2,00,000+ for complete Aeps portal ownership.
- Biometric Hardware (L1 Device): ₹2,000 – ₹3,000 per buy Aeps fingerprint device/buy Aeps iris scannerc device unit.
Transaction and Per-Operation Fees
- Cash Withdrawal: ₹0.50 – ₹1.50 per transaction (Aeps india side) or ₹15 + GST (for customer/issuer bank slabs on off-us transactions).
- Balance Enquiry: ₹0.10 – ₹0.25 per query.
- Mini Statement: ₹0.15 – ₹0.30 per request (or ₹5 + GST post-free limits).
- Aadhaar Pay: ₹0.40 – ₹1.00 per transaction.
- eKYC Verification: ₹1.00 – ₹2.00 per check.
Agent & Merchant Commissions
- Cash Withdrawal Commission: Slab-based earnings ranging from ₹2 to ₹15+ per transaction paid to the agent or touchpoint operator.
- Aadhaar Pay Earnings: Zero direct NPCI commission; agents typically charge customers up to 1% of the transaction value.
AEPS Service Solution Commission and Charges
AEPS service commission for retailers typically range from ₹2 to ₹10+ per cash withdrawal depending on the transaction slab, while customer charges are generally zero at home bank BCs but may incur ₹15–₹25 at third-party or off-us terminals.
Retailer Commission Structure (Cash Withdrawal)
Retailers and agents earn slab-based commissions for facilitating Aadhaar-based cash withdrawals:
| Transaction Amount Slab | Retailer Commission (Approx.) |
|---|---|
| ₹100 – ₹999 | ₹2.00 |
| ₹1,000 – ₹1,499 / ₹1,999 | ₹3.00 – ₹4.50 |
| ₹2,000 – ₹2,499 / ₹2,999 | ₹5.50 – ₹6.00 |
| ₹3,000 – ₹3,499 | ₹8.00 |
| ₹3,500 and above (up to ₹10,000) | ₹10.00 – ₹13.00 |
Note: Master distributors and distributors usually earn flat or tiered overrides (e.g., ₹1 to ₹2 per transaction, or flat monthly/per-lot structures).
Customer Charges & Limits
- Cash Withdrawal Limit: Capped by NPCI/RBI at ₹10,000 per transaction (with a daily limit of ₹50,000 per customer through standard biometric auth).
Customer Fees:
- Free at the customer’s own bank or micro-ATM point.
- Off-us / third-party bank touchpoints may charge customers around ₹15 + GST or up to ₹20–₹25 per transaction depending on the issuer bank’s policy (e.g., SBI or Airtel Payments Bank rules).
- Balance Inquiry & Mini Statement: Usually free for customers up to a monthly threshold (e.g., 5 free mini-statements), beyond which nominal fees like ₹5 + GST may apply.
AEPS Transaction Status, Settlement and Reconciliation
AePS transactions route through the National Payments Corporation of India (NPCI) central switch, settling daily on a T+1 basis. Failed or stuck transactions typically auto-reverse within 5 working days (T+5), while merchants and Business Correspondents (BCs) reconcile logs via acquiring Aeps bank portal.
Transaction Status Codes
- 00: Transaction Successful
- 01: Transaction Failed due to insufficient balance
- 06: Transaction Timeout / Network delay
- 09: Invalid Aadhaar number or unlinked account
Settlement & Cutover Timelines
- Daily Cutover: Occurs at 23:00 hours.
- Settlement Cycle: Typically processed on a T+1 daily basis between acquiring banks, issuer banks, and NPCI.
- Auto-Reversal (Failed Transactions): If an account is debited but the cash dispensing or transaction fails, the amount auto-reverses to the customer account within T+5 days. Compulsory compensation of ₹100/day applies if delayed beyond T+5.
Reconciliation Process for Agents & Banks
- Log Extraction: Micro ATM operators and BC agents download daily logs and RRN (Retrieval Reference Number) data from Aeps portals (e.g., Aeps india) or mobile Aeps commission app.
- Data Matching: Acquirer banks match central switch files (SOR/NPCI reports) against local merchant payout ledgers and bank statements.
- Credit Adjustments: If a mismatch or stuck debit occurs, a Credit Adjustment (CA) request is raised with the acquiring/sponsor bank (e.g., Yes Bank) for resolution within 2 to 3 working days.
AEPS Failed Transaction and Reversal Management
If an AEPS (Aadhaar Enabled Payment System) transaction fails but money is debited, the amount is typically auto-reversed to the customer’s bank account within T+1 to T+5 working days through NPCI’s UDIR (Unified Dispute and Issue Resolution) system. If the delay exceeds T+5 days, the bank is liable to pay a penalty of ₹100 per day.
Common Causes of AEPS Failures
- Biometric Mismatch: Poor fingerprint quality, dry/dirty fingers, or worn-out biometric lines.
- Server/Network Timeouts: Connectivity gaps between the Micro-ATM/BC agent app, acquirer bank, NPCI switch, and UIDAI.
- Account Issues: Insufficient balance, unseeded or unmapped Aadhaar-bank status, or disabled AEPS debit facility.
- Technical Decline: Bank server glitches or code-specific rejections (e.g., suspected malfunction).
Reversal & Resolution Timelines
- Auto-Reversal: Processed automatically by the system within 24 to 48 hours for standard network drops.
- Credit Adjustment (T+5 Rule): Acquirer/issuer banks must credit back the funds within 5 working days.
- Delay Penalty: If the refund is delayed past T+5 working days, a compensation of ₹100/day applies to the account holder.
Step-by-Step Guide to Manage & Dispute
- Check Transaction Status: Verify the receipt ID and run a mini-statement or balance inquiry via USSD (*99#) or mobile banking.
- Contact the Issuing Bank: Provide the 12-digit/reference transaction ID to customer care, use the net-banking grievance portal, or visit your home branch. You can also reach out via dedicated helplines like IPPB at India Post Payments Bank Support (155299).
- Raise an NPCI / UDIR Complaint: If the bank fails to act within the window, escalate the issue through the NPCI Consumer Complaints Portal.
- Report Fraud: If you suspect unauthorized access or biometric cloning, immediately dial 1930 or report the cyber fraud.
AEPS Service Solution Security and Customer Protection
The Aadhaar Enabled Payment System (AePS), managed by the top AePS Portal, uses biometric verification for cardless banking. To combat identity theft and fraud, the RBI AePS Guidelines mandate strict due diligence for touchpoint operators, ongoing risk monitoring, and real-time customer safety alerts.
Core Security Features
- Biometric Authentication: Uses unique best Aeps fingerprint or best Aeps iris scans instead of an ATM card or PIN.
- End-to-End Encryption: Secures data during transmission and storage across the network.
- Operator Due Diligence: Acquiring banks must complete full KYC checks and periodic updates for all AePS Touchpoint Operators (ATOs).
- Inactive Operator Locks: Banks must re-verify and conduct KYC on ATOs who remain inactive for three continuous months.
Customer Protection & Best Practices
- Keep Biometrics Safe: Avoid sharing or exposing your Aadhaar details and lock your biometrics via the UIDAI portal if unused.
- Disable/Lock AEPS: Contact your bank via customer care or visit your branch to disable AePS debit functions if you do not use the service.
- Verify Receipts & Alerts: Always collect a transaction receipt and check for real-time SMS debit alerts before leaving a touchpoint.
- Report Fraud Immediately: Dial 1930 immediately or report to the National Cyber Crime Reporting Portal in case of unauthorized transactions.
AEPS Service Solution vs Other Banking Services
Aadhaar Enabled Payment System (AePS) is a cardless, biometric-based banking model designed for last-mile financial inclusion, whereas traditional and digital banking services (such as UPI, Net Banking, and Debit/Credit Cards) rely on smartphones, PINs, or physical cards.
Key Differences at a Glance
| Feature / Service | Aadhaar Enabled Payment System (AePS) | Unified Payments Interface (UPI) | Traditional ATM / Debit & Credit Cards | Internet & Mobile Banking |
|---|---|---|---|---|
| Primary Access | Aadhaar Number + Biometrics (Fingerprint/Iris) | Smartphone + UPI PIN + VPA/QR Code | Physical Card + 4-digit ATM PIN | Login ID + Password + OTP |
| Target Audience | Unbanked, rural, or smartphone-free users | Smartphone users in urban and semi-urban areas | General bank account holders | Tech-savvy or formal banking users |
| Required Hardware | Micro-ATM / Biometric Scanner via Business Correspondent (BC) | Smartphone with internet connectivity | ATM kiosk or POS machine | Computer or smartphone with internet |
| Core Functions | Cash withdrawal, deposit, balance check, mini-statement | 24/7 instant peer-to-peer/merchant transfers | Cash withdrawal, balance inquiry, POS swiping | NEFT, RTGS, IMPS, bill payments, account management |
| Transaction Limits | Typically ₹10,000 per transaction (NPCI cap) | Up to ₹1,00,000 per day (varies by bank) | Bank-defined daily cash/POS limits | Higher daily limits for NEFT/RTGS/IMPS |
Advantages of AePS Service Solutions
- Cardless & PIN-Free: Eliminates the need to carry debit cards or remember PINs, using Aeps biometric fingerprint or Aeps biometric iris scans instead.
- Last-Mile Inclusion: Empowers rural populations to access basic banking through local Business Correspondents (BCs) and Kirana stores without traveling to bank branches.
- Government Subsidies: Facilitates easy withdrawal of Direct Benefit Transfers (DBT) and rural micro-insurance collections.
Limitations of AePS vs. Other Services
- Connectivity & Hardware Dependency: Requires active internet and working biometric hardware at agent touchpoints, leading to occasional authentication or network failures.
- Lower Transaction Caps: Capped strictly at ₹10,000 per withdrawal, making it unsuitable for large commercial or personal payments handled via RTGS, IMPS, or UPI.
- Intermediary Risk: Relies on local agents/BCs, whereas UPI and Internet Banking offer direct, self-serve digital execution.
Common Problems in AEPS Service Solution
Common problems in Aadhaar Enabled Payment System (AePS) service solutions include biometric authentication failures, poor network connectivity, issuer bank server timeouts, unlinked Aadhaar numbers, cash liquidity constraints for agents, and security risks like fingerprint spoofing.
Technical & Transaction Errors
- Biometric Mismatch: Fingerprints fail to scan due to dry skin, dust, worn-out ridges (common in manual laborers), or outdated Registered Device (RD) service drivers.
- Network & Server Outages: Intermittent internet in rural areas or downtime at the issuer bank/NPCI switch leads to modern Aeps API timeouts or frozen requests.
- Aadhaar-Bank Unlinkage: The customer’s Aadhaar is not mapped to the specific bank account or the bank’s IIN (Institution Identification Number) is entered incorrectly.
- Account Status Restrictions: Transactions are declined because the account is dormant, frozen, closed, or has AePS debit services disabled by the bank.
- Limit Exceeded: Attempting a withdrawal that crosses the single-transaction cap of ₹10,000 or daily bank thresholds.
Operational & Business Challenges
- Cash Liquidity Management: Business correspondents (BCs) struggle to maintain physical cash reserves at retail shops to meet heavy rural withdrawal demands.
- Delayed Dispute Resolution: When a customer’s account is debited during a failed transaction, waiting for automated or manual reversals can take days, straining trust.
- Thin Margins: Low per-transaction commissions paired with high electricity, biometric device maintenance, and annual RD service renewal costs.
Security & Fraud Risks
- Biometric Spoofing: Fraudsters use silicon fingerprint replicas or cloned biometrics obtained from data leaks to execute unauthorized withdrawals.
- Ghost Accounts: Unscrupulous agents exploit weak KYC processes to open fraudulent accounts for diverting government subsidies.
- Lack of Real-Time Alerts: Delayed or missing SMS notifications prevent victims from spotting unauthorized AePS debits immediately.
Aeps india One Of The Right AEPS Service Solution Provider
Aeps india one of the right AEPS service solution provider, evaluate compliance with NPCI and UIDAI, high transaction success rates (98%–99%+), transparent commission structures, fast or real-time settlements, and reliable 24/7 customer support.
Core Factors to Evaluate
- Security & Compliance: Ensure the Aeps earning platform strictly adheres to NPCI, RBI, and UIDAI guidelines, featuring end-to-end data encryption and secure biometric authentication (fingerprint/iris).
- Success Rate & Uptime: Look for Aeps india that offer a 98% to 99%+ transaction success rate to prevent customer drop-offs during cash withdrawals or balance inquiries.
- Commission & Pricing: Compare per-transaction earnings (which can scale up to ₹15–₹16 depending on volume) and watch out for hidden gateway or monthly maintenance fees.
- Settlement Speed: Aeps india offering instant or same-day fund settlements into your working bank account to maintain healthy daily cash flow.
- Service Range: Check if the Aeps india supports essential tools like Aeps cash withdrawal service, Aeps balance inquiry service, Aeps mini statement service, Aadhaar Pay software and utility/bill payments.
- Integration & Usability: If you need an high speed Aeps API, look for clear Aeps developer documentation, sandbox testing, and reliable tech support. If you are a retailer or agent, choose an intuitive Aeps mobile app or web portal.
- Customer Support: Responsive 24/7 helpdesks via phone, chat, or email are critical for resolving stuck or failed biometric transactions immediately.
Why Aeps india for AEPS Service Solution
Aeps india is an AePS service solution provider enables retail shops, local entrepreneurs, and fintech businesses to offer core banking services such as cash withdrawals, balance checks, mini-statements, and fund transfers using only a customer’s Aadhaar number and biometric scan via Aeps commission platform like NPCI AePS Overview.
Key Benefits of Using an AePS Service Provider
- Financial Inclusion: Brings basic banking infrastructure to rural and unbanked areas where physical bank branches or ATMs are far away.
- Cardless & PIN-Free Transactions: Eliminates the need for debit cards, credit cards, or secret PINs by relying strictly on UIDAI-certified biometric authentication (fingerprint or iris scan).
- Additional Income & Commissions: Retailers and Business Correspondents (BCs) earn tiered transaction commissions directly into their wallets for every cash withdrawal or balance inquiry.
- Increased Footfall: Local shopkeepers and micro-merchants attract more customers to their storefronts by acting as mini-banking touchpoints.
- Value-Added Services: Aeps india bundle AePS service software with extra utilities like Best BBPS, mobile recharges, cash deposits, and Aadhaar Pay API.
Conclusion: Choose the Right AEPS Service Solution with Aeps India
Choosing the right AEPS Service Solution is essential for businesses that want to offer Aadhaar Enabled Payment System services through a reliable digital Aeps banking platform. AEPS enables customers to access supported banking services through participating banks and authorized service providers using Aadhaar-based authentication. Depending on the Aeps india, available services may include cash withdrawal, balance enquiry, mini statement, and other supported banking transactions.
For retailers, distributors, fintech startups, and digital service businesses, Aeps india is the right AEPS Service Solution should offer more than basic transaction processing. Important factors to evaluate include biometric device compatibility, secure authentication, transaction-status tracking, retailer and distributor management, commission configuration, transaction reports, settlement and reconciliation processes, technical support, and integration options. Service availability and features depend on the provider, participating bank, and applicable regulatory requirements.
The Aadhaar Enabled Payment System (AePS) is a bank-led financial inclusion model developed by the Aeps india that allows cardless, PIN-free transactions using an Aadhaar number and biometric authentication (fingerprint or iris scan) through authorized Aeps india.
Aeps India can help businesses explore top AEPS software, Aeps earning platform, and integration requirements according to their business model. Before selecting a Aeps india, confirm the onboarding process, required documentation, commercial terms, supported services, security measures, and authorization requirements. A clear understanding of these factors can help you choose a solution that fits your operational needs and supports future business growth.
If you are planning to start or expand an AEPS business, evaluate the available solutions carefully and prioritize secure transactions, transparent reporting, dependable technical assistance, and compliance with applicable requirements.
Looking for an AEPS Service Solution with Aeps India? Discuss your requirements and explore suitable options by visiting the Aeps India Contact Page. Find out which services, integrations, and Aeps b2b platform features are appropriate for your business before moving forward.
AEPS Service Solution with Aeps India
Looking for a reliable AEPS Service Solution for your digital banking business? Contact Aeps India to learn about AEPS services, biometric-enabled transactions, integration options, and business setup support. Get in touch to discuss your requirements and find a suitable solution for your business.
Frequently Asked Questions About AEPS Service Solution
An AEPS Service Solution is a digital banking service that uses the Aadhaar Enabled Payment System to help customers access supported banking services through eligible banking agents or Business Correspondent outlets. Depending on the Aeps india, it can support cash withdrawal, balance enquiry, and mini statements using Aadhaar-based authentication.
The customer selects a supported banking service, provides the required Aadhaar and bank details, and completes biometric authentication using a compatible device. The transaction request is processed through the authorised banking network. The retailer should confirm the final transaction status before handing over cash or confirming completion.
Common AEPS services include cash withdrawal, balance enquiry, and mini statement. Other services, such as cash deposit, may depend on the participating bank, authorised Aeps india, and available service arrangement. Confirm the current service list before onboarding.
Eligible customers with an Aadhaar-linked bank account can use supported best AEPS services, subject to bank and service requirements. Retailers, banking agents, and Business Correspondent networks may offer these services when properly authorised and Aeps onboarded.
Common features include retailer login, biometric transaction processing, supported bank selection, transaction status tracking, transaction history, reporting, and customer receipt management. Depending on the Aeps service platform, additional features may include distributor management, commission reports, wallet management, and administrative controls.
AEPS transactions generally require a compatible biometric authentication device, an internet-connected device or terminal, and access to an authorised AEPS service. The exact hardware and software requirements depend on the provider’s supported setup.
Start by selecting an authorised Aeps india. Check eligibility, submit the required business and identity documents, complete verification and Aeps onboard, arrange compatible equipment, and test the service before serving customers. Confirm the provider’s current requirements before applying.
Requirements vary by Aeps india. Commonly requested documents may include identity proof, address proof, business details, bank account information, and photographs or other onboarding records. Aeps india for its current document checklist rather than relying on a generic list.
The customer provides the required details and completes Aadhaar-based biometric authentication. The request is processed through the relevant banking network. Once the transaction is confirmed successful, the authorised retailer can hand over the approved withdrawal amount and provide the transaction record.
Check the transaction status using the authorised fast Aeps platform and retain the transaction reference number. Verify whether the request failed, remains pending, or was completed. If money was debited but cash was not received, follow the Aeps india complaint and reversal process. Do not repeat the transaction blindly before checking its status.
Use the transaction history or status-checking facility provided by the authorised trusted AEPS platform. Keep the transaction reference number, date, amount, and relevant bank details available. If the status remains unclear, contact the Aeps india through its official support channel.
Retailer commission depends on the Aeps india commercial terms, eligible transaction types, transaction amount slabs, and applicable charges. Before joining, request the current commission chart and confirm settlement timing, deductions, minimum balance requirements, and any recurring fees. Earnings should not be assumed to be fixed or guaranteed.
AEPS is an Aadhaar-based banking service that uses the authentication method required by the service. A Micro ATM is a device or terminal used to facilitate supported banking transactions. Some Micro ATM setup may support AEPS, but the available services depend on the device, bank, and authorised service arrangement.
Safety depends on the authorised service arrangement and how the standard Aeps platform is operated. Customers should use trusted outlets, review the transaction amount, protect their personal information, and retain transaction receipts. Retailers should follow authentication procedures, secure access credentials, and avoid recording sensitive customer information unnecessarily.
Possible reasons include poor fingerprint capture, a dirty sensor, device compatibility issues, connectivity problems, or an authentication mismatch. Follow the device and Aeps india instructions, check the connection, and retry only when appropriate. If the problem continues, use the authorised support process.
Compare supported banking services, onboarding requirements, compatible devices, transaction-status tracking, customer support, reporting, commission terms, and applicable charges. Verify the Aeps india authorisation and service arrangements, and ask for a demonstration before committing.
The total cost depends on the Aeps india onboarding terms, software or device requirements, setup charges, maintenance, and transaction-related fees. Request a written breakdown of one-time and recurring expenses before starting the business.
Aadhaar Enabled Payment System platform support multiple user levels, including retailers, distributors, and administrators. Available functions may include user onboarding, transaction reports, commission tracking, and account management. Confirm which functions are included in the specific high earning Aeps platform.
Ask AEPS India to confirm its currently available banking services, fast Aeps onboarding and eligibility requirements, supported devices, transaction handling, commission terms, fees, and support arrangements. Verify any claims about authorisation and service availability before registering.
Contact AEPS India to enquire about the available AEPS service solution, current eligibility criteria, documentation, onboarding process, device requirements, and commercial terms. Review the details carefully before completing registration.
AEPS Software Company in India
Trusted AEPS API Provider in India : Complete Guide
Live AEPS API Provider in India (2026): Complete Guide
About Author

