UPI Cash Withdrawal Solution: Benefits and Working Process
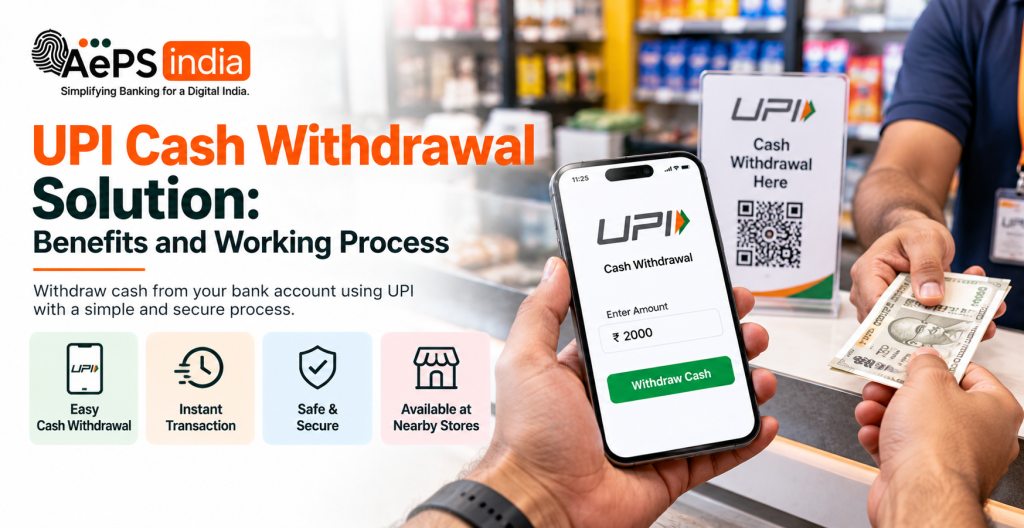
A UPI Cash Withdrawal Solution enables customers to access physical cash through supported UPI-based services without relying on a traditional debit card. Depending on the service model, customers may withdraw cash at a compatible UPI-enabled ATM or an authorized Business Correspondent (BC) or retail cash point by scanning a transaction-specific QR code and approving the payment through their UPI application. For fintech startups, retailers, distributors, and digital banking businesses, this technology creates opportunities to make cash access more convenient for customers.
With a suitable UPI Cash Withdrawal Solution in India, businesses can explore a digital process that connects customers, participating retailers, and the relevant payment infrastructure. In an agent-based cash-point model, the retailer initiates a withdrawal request, generates a dynamic QR code, and provides the requested cash after receiving confirmation of a successful transaction. This differs from UPI ATM cash withdrawal, where the customer scans a QR code displayed by a compatible ATM. The available process depends on the Aeps india and its authorized UPI Cash Withdrawal setup.
UPI Cash Withdrawal allows you to withdraw money from supported ATMs or local retail “Cash Points” without using a physical debit card, leveraging the Interoperable Cardless Cash Withdrawal (ICCW) network. By scanning a dynamic QR code using any UPI app (like Google Pay or Paytm), you can instantly authorize cash dispensation using your UPI PIN.
Before choosing a UPI Cash Withdrawal Service Provider, businesses should evaluate UPI Cash Withdrawal API integration, dynamic QR generation, transaction-status enquiries, webhook notifications, settlement procedures, commission terms, security controls, and technical support. Clear handling of pending and failed transactions is particularly important. Retailers should verify successful payment confirmation before handing over cash and follow the Aeps india process for investigating disputed transactions.
Aeps India helps businesses explore digital UPI Cash Withdrawal banking software and integration options based on their operational requirements. If you are planning to expand your financial services, evaluate how a UPI cash withdrawal service could fit your existing retailer network, digital UPI Cash point panel or fintech business model. Confirm the available service features, eligibility criteria, authorization requirements, and commercial terms before launching.
Whether you are a fintech entrepreneur, retailer, distributor, or digital financial service provider, selecting the right UPI Cash Withdrawal Solution can help you evaluate new ways to serve customers who need convenient access to cash. Contact Aeps India to discuss your business requirements and explore suitable digital banking integration options.
In this guide, you will learn how a UPI Cash Withdrawal Solution works, how UPI cash points differ from UPI-enabled ATMs and AEPS services, which features businesses should evaluate, how transactions are processed, and what to consider when selecting a Aeps india. Understanding these differences can help you make a more informed decision and choose an approach that suits your customers and business goals.
What Is a UPI Cash Withdrawal Solution?
A UPI Cash Withdrawal Solution is a digital banking system that allows users to withdraw physical cash without using a physical debit or credit card, relying instead on the Unified Payments Interface (UPI) and a smartphone.
UPI Cash Withdrawal Work?
UPI cash withdrawal lets you take out money from a compatible ATM using your smartphone app instead of a physical debit or credit card.
How It Works
- Select Option: Visit a UPI-enabled ATM and choose “UPI Withdrawal” or “Cardless Cash” on the screen.
- Enter Amount: Type the cash amount you wish to withdraw (must be in multiples of ₹100).
- Scan QR Code: A unique, single-use dynamic QR code will appear on the ATM screen. Open your UPI app (such as Google Pay, PhonePe, or Paytm) and scan this QR code.
- Authorize Payment: Select the bank account linked to your app and enter your UPI PIN to confirm.
- Collect Cash: Once authorized, the ATM dispenses your physical cash.
Types of UPI Cash Withdrawal Solutions
UPI cash withdrawal solutions in India fall into two primary categories: UPI ATM Cash Withdrawals and UPI Cash Points (Merchant Cash-Out).
1. UPI ATM Cash Withdrawal (Interoperable Cardless Cash Withdrawal – ICCW)
This method lets you pull cash from physical, UPI-enabled automated teller machines (ATMs) without using a physical debit card.
- How it works: You select the “UPI Cash Withdrawal” or “Cardless Cash” option on the ATM screen, enter your desired amount, and scan the single-use dynamic QR code using any UPI app. You then authorize the payment with your UPI PIN to get your cash.
- Limit: Up to ₹10,000 per transaction (while remaining subject to your standard daily UPI and bank limits).
- Where to find them: Live across thousands of terminals supported by participating banks and networks managed via NPCI.
- Key benefit: Completely eliminates card-skimming or cloning risks.
2. UPI Cash Points (Retailer / Agent Cash-Out)
This decentralized model turns local kirana stores, retail shops, or Bank Mitra / micro-ATM touchpoints into human cash-dispensing counters.
- How it works: Instead of visiting a bank machine, you walk up to an authorized partner merchant use a Aeps india. The retailer enters the withdrawal amount on their merchant app, generates a QR code on an Android device or display, and you scan and pay via UPI to receive physical cash from the shop owner.
- Limit: Dependant on the retailer’s cash-in-hand availability and local platform rules.
- Where to find them: Local neighborhood partner stores, micro-banking outlets, and rural/semi-urban trade touchpoints where traditional ATMs are sparse.
- Key benefit: High accessibility in areas lacking physical ATMs, with zero hardware requirement other than a standard smartphone or screen for the merchant.
UPI Cash Withdrawal Solution Eligibility and Setup Requirements
UPI cash withdrawal (Interoperable Cardless Cash Withdrawal or ICCW) allows you to withdraw physical cash from a compatible ATM using a smartphone without a debit or credit card.
Eligibility Requirements
- Active Bank Account: Must hold a savings or current account with a bank that supports UPI cash withdrawal.
- UPI-Enabled App: Must have an active UPI application installed on your smartphone.
- Registered Mobile Number: Your mobile number must be linked to both your bank account and your UPI app.
- UPI PIN: Must have an active, functioning UPI PIN set for the linked account.
- ATM Compatibility: The physical Micro ATM machine must support UPI-based cardless cash withdrawal options.
- Transaction Limits:
- Maximum ₹10,000 per transaction (in multiples of ₹100).
- Subject to daily UPI and individual bank-imposed limits.
Setup & Withdrawal Process
- At the ATM: Approach a UPI-enabled ATM and select the UPI Cardless Cash or UPI Withdrawal option on the screen.
- Enter Amount: Type in the desired withdrawal amount (dispensed in ₹100 multiples up to the ₹10,000 per-transaction cap).
- Scan QR Code: A dynamic QR code will appear on the ATM display.
- Authorize on App: Open your preferred UPI app on your phone, tap Scan & Pay, and scan the ATM screen’s QR code.
- Enter PIN: Select the appropriate bank account, verify the withdrawal amount, and enter your UPI PIN.
- Collect Cash: Once authenticated, the ATM will dispense the physical cash.
Who Can Use UPI Cash Withdrawal Solution
Any bank account holder in India with a smartphone, an active UPI-enabled app and a valid UPI PIN can use the UPI cash withdrawal solution.
Where You Can Use It
- UPI-Enabled ATMs: Any customer can use participating bank ATMs that support Interoperable Cardless Cash Withdrawal (ICCW) via UPI.
- Authorized Retailer/Agent Shops: Customers can withdraw physical cash from enabled micro ATM, business correspondent (BC), or partner retail counters (such as networks powered by Aeps india by scanning a shop’s QR code.
Why Use UPI Cash Withdrawal Solution
A UPI cash withdrawal solution lets you pull physical cash from an ATM or retail counter using your smartphone instead of a physical debit or credit card, via the UPI Guide or similar banking portals.
Key Benefits
- No Card Needed: You do not need to carry, swipe, or insert a physical debit card.
- Better Security: It uses the Interoperable Cardless Cash Withdrawal (ICCW) method with QR codes and your mobile UPI PIN. This completely eliminates risks like card skimming, cloning, or physical card theft at the machine.
- Emergency Access: If you forget your wallet or card at home, you can still get cash right away as long as your phone has an active UPI app.
- Real-Time Tracking: Transactions reflect immediately in your linked bank account and UPI app with instant digital receipts.
- Wider Reach (Retail CashPoints): Beyond traditional Micro ATM, some networks turn local shops and agent counters into cardless cash-dispensing points using simple Android screens and QR codes.
Key Aspects of UPI Cash Withdrawal Solution
The UPI cash withdrawal solution allows users to withdraw physical cash without a physical debit card through two primary methods: UPI ATMs (Interoperable Cardless Cash Withdrawal or ICCW) and UPI Cash Points at local merchant outlets.
Key Aspects & Mechanism
- Cardless Convenience: Eliminates the need to carry physical debit or credit cards, reducing risks associated with card skimming, cloning, and physical theft.
- Two-Factor Authentication: Relies on mobile device security and the user’s secret UPI PIN entered directly inside a UPI app rather than typing a PIN on potentially compromised ATM pads.
- Dynamic QR Code: Generates a unique, single-use dynamic QR code for every session to prevent replay attacks or fraudulent duplication.
- Transaction Limits: Capped at ₹10,000 per transaction (in multiples of ₹100) for UPI ATMs, aligned with standard per-transaction limits. UPI Cash Points at retail shops typically cap transactions around ₹5,000 per session.
- Interoperability: Powered by national frameworks like the National Financial Switch (NFS) network and NPCI ecosystem, enabling users to draw cash from compatible ATMs or merchant touchpoints regardless of the issuing bank of the account or the ATM operator.
- Failure & Refund Handling: If cash fails to dispense due to machine errors, connectivity drop-outs, or timeouts, debited amounts are typically auto-reversed back to the linked bank account within 5 business days.
Why UPI ATM Services Are Gaining Popularity
UPI ATM services are gaining popularity because they enable cardless, secure, and instant cash withdrawals using a smartphone and any UPI app.
Key Reasons for Growing Popularity
- Elimination of Physical Cards: Users do not need to carry a debit or credit card, removing the risks of cards getting lost, damaged, swallowed, or cloned.
- Superior Security (No Skimming Risk): Transactions are authenticated directly on the user’s mobile device via a UPI PIN and a dynamic QR code scan on the ATM screen, eliminating magnetic stripe skimming fraud.
- Frictionless and Fast Flow: The process requires only a few quick steps—choosing the cash amount, scanning the on-screen QR code through apps like Google Pay or Paytm, and confirming with the UPI PIN without dealing with legacy card-insertion delays.
- Interoperability: Powered by NPCI and RBI frameworks, users can pull cash from participating ATMs using accounts linked across various banks without needing a specific bank’s card.
- Lower Bank Infrastructure Overhead: Banks and white-label operators like Hitachi Payment Services benefit from reduced costs associated with physical card issuance, replacement, and fraud management.
UPI-ATM Cash Withdrawals: A New Horizon
You can withdraw cash from a UPI-enabled ATM without a physical debit or credit card using the Google Pay Help Center or any other UPI app.
How to Withdraw Cash Using UPI
- Select Option: Approach a UPI-enabled ATM and tap UPI Withdrawal or UPI Cardless Cash on the screen.
- Enter Amount: Type the cash amount you need (up to ₹10,000 per transaction). A dynamic QR code will appear on the ATM screen.
- Scan QR Code: Open your UPI app (such as Google Pay and BHIM) and scan the on-screen QR code.
- Authorize Payment: Select the linked bank account and enter your UPI PIN on your phone.
- Collect Cash: Wait for the ATM to dispense your cash and take your receipt.
UPI Cash Withdrawal Solution Setup Requirements
Setting up a UPI Cash Withdrawal Solution whether for an ATM network (Interoperable Cardless Cash Withdrawal / ICCW), a MicroATM / Business Correspondent (BC) touchpoint, or a retail merchant “UPI Cash Point” requires a combination of regulatory compliance, technical integration, and partner/banking tie-ups governed by the National Payments Corporation of India (NPCI) and the Reserve Bank of India (RBI).
1. Regulatory & Compliance Requirements
- Sponsor Bank Tie-up: You must partner with an Aeps india reconciliation, and compliance.
- KYC & AML Norms: Full Know Your Customer (KYC) and Anti-Money Laundering (AML) verification must be completed for every merchant, Business Correspondent (BC), or agent outlet offering the cash-out service, as mandated by RBI.
- Merchant Category Codes (MCC): Transactions must be tagged with designated MCCs (e.g., MCC 6013 for MicroATM/BC cash withdrawals or specific MCCs assigned by NPCI) to track and report cash-out volumes properly.
- Two-Factor Authentication (2FA): All cash-out transactions require mandatory two-factor authentication via the customer’s UPI PIN or authorized biometric verification. (Note: UPI LITE and credit-line accounts are typically excluded from cash-out services).
2. Technical & Software Requirements
- Dynamic QR Generation: The Aeps india must be capable of generating a single-use, transaction-specific dynamic QR code either on an ATM screen, a MicroATM device, or a retailer’s app/dashboard. Static QRs cannot be used for cash withdrawals due to security risks.
- API & Switch Integration:
- Direct integration with Aeps india switches and the sponsor bank’s core banking / payment gateway APIs.
- Real-time ledger updates to track liquid cash inventory at the retailer/ATM end versus digital settlement in the bank account.
- App / Dashboard Interface: An authorized mobile UPI Cash Withdrawal app, web dashboard, or terminal interface (such as a Aeps india) for entering withdrawal amounts and viewing instant settlement logs.
3. Transaction & Operational Limits (NPCI Guidelines)
- Per-Transaction Limit: Standard maximum cap of ₹10,000 per transaction (though some MicroATM/BC channels or individual banks cap specific tiers at ₹5,000 per transaction).
- Daily / Monthly Caps:
- MicroATM / BC touchpoints: Typically capped at ₹10,000 per day and ₹50,000 per month per user profile.
- Standard ATM ICCW: Subject to the user’s overall daily UPI limit (up to ₹1,00,000 across general UPI usage) and individual bank caps.
- Cooling Periods / Frequency: Certain UPI Cash point setup enforce transaction frequency caps (e.g., maximum limits per day with a 30-minute cooling interval between consecutive cash-outs).
4. Infrastructure & Hardware Setup
- For UPI ATMs (ICCW): Upgraded ATM/CRM hardware capable of displaying a dynamic QR code on the monitor and communicating with interoperable UPI switches.
- For MicroATM / BC Outlets: An Android-based mobile device or MicroATM terminal paired optionally with a biometric/card reader (if supporting multi-mode BC services).
- For Retail “UPI Cash Points” (Kirana/Shops): Just a standard smartphone or tablet running the approved UPI Cash Withdrawal app to display the dynamic QR code; no extra card-swipe hardware is strictly mandatory.
UPI Cash Withdrawal Solution for Fintech Businesses
A UPI Cash Withdrawal Solution (often called UPI CashPoint, QR ATM, or Interoperable Cardless Cash Withdrawal – ICCW) allows Aeps india to turn everyday local shops, kiosks, or ATMs into card-free cash dispensing points.
Core Benefits for Fintech Businesses
- Zero Hardware Costs: Unlike traditional Micro ATM (MATMs) or card swipe machines that require expensive physical hardware provisioning, UPI CashPoints run using a standard smartphone or displayed dynamic QR code.
- Elimination of Card Fraud: Skimming, cloning, and physical card wear-and-tear risks are completely removed because authentication happens digitally via 2-factor UPI PIN or emerging on-device biometrics.
- Network Scalability: Fintechs can embed UPI Cash Point APIs into existing B2B UPI Cash Point software panels to onboard Kirana stores, medical shops, and Common Service Centers (CSCs) into a broad-reaching Aeps india.
- Retailer Monetization: Store owners earn a commission or partner incentive on every successful cash-out transaction, driving higher customer footfall and recurring business income.
UPI Cash Withdrawal Solution for Retailers and Business Correspondents
The UPI Cash Point Solution allows local retailers, shop owners, and Business Correspondents (BCs) to turn their shops into cash withdrawal counters. Instead of relying on a physical debit card, ATM, or Aadhaar biometric authentication (AePS), customers can scan a dynamic QR code using any UPI app on their phone and receive physical cash from the retailer.
Benefits for Retailers & Business Correspondents
- No Extra Hardware Needed: Works directly on Android smartphones or existing partner apps without needing a card swipe machine or Micro ATM hardware.
- New Revenue Stream: Retailers earn a commission on every cash withdrawal plus potential partner incentives.
- Increased Footfall: Acting as a local cash point brings more walk-in customers into the shop.
- Reduced Cash-In-Hand Burden: Helps circulate physical cash cleanly through digital settlements.
Features UPI Cash Withdrawal Solution
The UPI cash withdrawal solution (Interoperable Cardless Cash Withdrawal or ICCW) allows users to pull cash from ATMs or local retail cash points using a smartphone and any UPI-enabled app without a physical debit card.
Key Features of UPI Cash Withdrawal
- Cardless Convenience: Eliminates the need to carry physical debit or credit cards, preventing card loss, theft, or wear and tear.
- Enhanced Security: Uses single-use dynamic QR codes generated on the spot and mobile-based UPI PIN authorization, completely avoiding risks like card skimming or cloning.
- Interoperability: Powered by the National Payments Corporation of India (NPCI), allowing customers of any participating bank to withdraw cash from any UPI-enabled ATM or authorized Aeps india website.
- Multiple Account Access: Gives users the flexibility to select and switch between multiple bank accounts linked within their UPI app at the time of withdrawal.
- Transaction Limits: Generally capped at up to ₹10,000 per transaction (or ₹5,000 to ₹10,000 daily depending on the specific bank and app policies).
- No Specific Extra Charges: No separate NPCI or network charges are levied directly for UPI cash withdrawals, though standard bank transaction rules or limits apply.
Benefits UPI Cash Withdrawal Solution
The UPI cash withdrawal solution (Interoperable Cardless Cash Withdrawal or ICCW) lets you withdraw cash from ATMs using a smartphone and UPI app without needing a physical debit or credit card.
Key Benefits
- Card-Free Convenience: You can withdraw cash anytime using just your phone, meaning you do not have to worry about carrying, misplacing, or forgetting your physical debit card at home.
- Enhanced Security Against Fraud: Because you do not insert a physical card into the machine, the system eliminates risks related to card skimming, card cloning, and physical theft.
- Dynamic QR Code Protection: Each transaction uses a single-use dynamic QR code displayed on the ATM screen, making the cash withdrawal session secure.
- Two-Factor Authentication: You authorize the cash withdrawal directly on your mobile device using your familiar UPI PIN rather than a separate ATM card PIN.
- Multi-Account Flexibility: You can link multiple bank accounts to your UPI app and choose a specific account from which to pull the cash at the ATM.
- Interoperability: The service works across participating banks and networks, letting you use compatible ATMs regardless of which bank holds your UPI-linked account.
- Transaction Limits: The general limit is up to ₹10,000 per transaction (subject to individual bank and daily UPI limits).
UPI Cash Withdrawal Transaction Process: Step by Step
You can withdraw cash from a UPI-enabled ATM without a physical debit card by scanning a dynamic QR code using any UPI app.
Step-by-Step Withdrawal Process
Step 1: Select Option on ATM
- Approach a UPI-enabled ATM and select the “UPI Cash Withdrawal” or “UPI Cardless Cash” option on the screen.
Step 2: Enter the Amount
- Type in the required cash withdrawal amount. Note that the amount must be in multiples of ₹100, up to a maximum limit of ₹10,000 per transaction.
Step 3: Scan the Dynamic QR Code
- A single-use dynamic QR code will appear on the ATM screen. Open a UPI-enabled app on your smartphone, select the scanner tool, and scan the QR code.
Step 4: Authorize the Transaction
- Verify the cash amount and recipient details on your phone screen, choose the linked bank account, and enter your UPI PIN to authorize the payment.
Step 5: Collect Cash
- Once the transaction is authenticated, the ATM will dispense your cash. Collect your money and take a receipt if desired.
UPI Cash Withdrawal Solution Cost Structure
UPI cash withdrawal solutions operate across two primary models: ATM-based UPI cash withdrawals (Interoperable Cardless Cash Withdrawal / ICCW) and Retailer / Agent-based UPI cash points.
1. Customer Cost Structure at UPI-Enabled ATMs
- Free Quota: UPI cash withdrawals at ATMs count toward your bank’s standard monthly free ATM transaction limits (typically 5 free transactions at your own-bank ATMs, and 3 to 5 free transactions at other-bank ATMs).
- Post-Limit Charges: Once your complimentary monthly quota is exceeded, banks typically charge ₹23 plus applicable GST/taxes per transaction.
- Per-Transaction Limit: The maximum withdrawal limit via UPI at ATMs is ₹10,000 per transaction (while remaining subject to your bank’s daily UPI and ATM caps).
- Direct Bank Transfers: Standard personal UPI person-to-person (P2P) or direct bank-to-bank transfers remain free of charge.
2. Retailer and Agent-Based UPI Cash Point Solutions
- Hardware & Onboarding Cost: UPI CashPoint Solution feature zero onboarding, zero hardware dependency (no ATM machines, debit cards, or biometric devices required), and no recurring subscription or renewal fees.
- Retailer Commissions: Agents and shop owners earn a commission structure based on the transaction volume and Aeps india terms (ranging up to tiered or industry-standard percentage/flat commissions per cash-out event).
- Credit Limits: Retail UPI Cash Withdrawal platform can extend working capital or retailer credit limits (such as up to ₹15 lakh) to service cash-dispensing requests at local storefronts.
UPI Cash Withdrawal Commission and Revenue Model
The UPI Cash Point API allows local shops and Business Correspondents (BCs) to dispense physical cash to customers in exchange for a digital UPI payment, creating a cardless, micro-ATM alternative.
Commission Structure for Retailers
- Per-Transaction Earnings: Retailers earn a commission or fee on every cash-out transaction processed. Depending on the UPI Cash point platform, commissions can range up to ₹8 per transaction or vary based on the slab amount terms (such as Aeps india offering tiered or high-percentage payouts).
- No Direct Cost for User / Cardless Model: Customers use a smartphone and UPI app (scanning a dynamic QR code) without needing a physical debit card or paying traditional ATM interchange fees.
Revenue Model & Ecosystem Economics
- Retailer Incentive: Retailers gain extra commission income and increased foot traffic as local neighborhood cash hubs.
- Platform & API Provider Monetization: Aeps india monetize via transaction-processing shares, B2B UPI Cash Withdrawal software integration, and ancillary financial services (AEPS software, micro ATM software, and domestic money transfers).
- Broader UPI Market Context: While peer-to-peer (P2P) and standard lower-value UPI merchant transactions operate under zero-MDR guidelines, specialized cash-out and commercial or credit-on-UPI pathways incorporate structured fee-sharing models to sustain backend infrastructure and retail liquidity.
UPI Cash Withdrawal Transaction Limits and Applicable Rules
UPI cash withdrawals can be done via ATMs (Interoperable Cardless Cash Withdrawal or ICCW) and MicroATMs.
Transaction & Daily Limits
- Per-Transaction Limit (ATM): Maximum of ₹10,000 per transaction.
- Daily / Cap Limits (ATM): Varies by bank (for example, HDFC Bank allow up to 2 transactions or ₹20,000 per day), while constrained overall by your general daily UPI limit (typically ₹1,00,000).
- MicroATM Limits: NPCI guidelines allow up to ₹5,000 per transaction, ₹10,000 per day, and ₹50,000 per month at Aeps india touchpoints.
Applicable Rules & Charges
- Free ATM Quota Inclusion: UPI cash withdrawals at ATMs count toward your bank’s monthly free ATM transaction limits (5 free transactions at your own bank; 3 in metro or 5 in non-metro areas at other banks).
- Post-Free Limit Charges: Exceeding the free monthly ATM quota incurs a fee of ₹23 plus applicable taxes per transaction.
- Authentication: Requires scanning a single-use dynamic QR code displayed on the ATM/MicroATM screen and authorizing the amount via your smartphone UPI app using your UPI PIN.
- Multi-Account Support: You can select and withdraw from any bank account linked inside your UPI app.
- Exclusions: UPI LITE and credit-type accounts are generally excluded from cash withdrawal features.
UPI Cash Withdrawal Software and API Integration
You can build or integrate a cardless cash withdrawal platform using the UPI Cash Point API in India or white label UPI Cash Withdrawal API infrastructure from Aeps india
Core Software & API Features
- Dynamic QR & Intent APIs: Generates single-use QR codes tied to specific terminal IDs, merchant IDs, and withdrawal amounts.
- Transaction Status Enquiry API: Polls or checks real-time transaction states (success, pending, or failed).
- Webhook / Callback Handlers: Pushes instant server-to-server notifications to your backend the moment a payment clears.
- Settlement & Commission Engine: Automates B2B commission splits, merchant payouts, and liquidity reconciliation.
- Agent & Network Hierarchy Management: Lets best UPI Cash point platform owners manage distributors, local retailers, and wallet balances.
Turn Every Agent Into a Cash Point
Turn Every Agent Into a Cash Point” is a major operational concept in agent banking, retail fintech, and digital financial inclusion. It focuses on enabling local shopkeepers, merchants, and mobile money agents to act as decentralized micro-ATMs where customers can easily deposit, withdraw, or transfer money.
The primary snippets and mechanisms used to implement this system across global retail networks include:
1. UPI Cash Point & Cardless Withdrawals
Modern applications leverage QR-code-based withdrawals to bypass physical plastic cards and expensive biometric hardware.
- The Mechanism: Customers scan an agent’s dynamic or static UPI QR code using apps like Paytm or Google Pay to withdraw cash instantly.
- Virtual ATM Frameworks: Solutions provided by platforms like Paymart India integrate directly into partner banks’ Core Banking Systems (CBS). A user generates an OTP-authenticated token on their mobile banking app, the retail agent verifies the token, and then hands over the physical cash.
2. Aadhaar Enabled Payment System (AePS)
In regions like India, this infrastructure uses national digital identity architectures to convert small rural merchants into fully operational bank branches.
- Biometric Authentication: Agents utilize simple fingerprint or iris scanners linked to a customer’s Aadhaar number.
- Core Functionality: Enables instant cash withdrawals, balance inquiries, mini-statements, and paperless e-KYC account openings right from a neighborhood store.
3. POS and Micro-ATM Terminals
Hardware vendors provide handheld, portable card-swipe terminals (often called “Bank-in-a-Box”) designed to service locations that standard ATMs cannot reach.
- Dual-Purpose Merchant Terminals: The same device used to accept standard customer debit or credit card payments for retail goods also functions as a cash dispenser.
- Revenue Loop: Every successful cash withdrawal earns the business correspondent or agent a direct commission fee, driving immediate secondary revenue for the shop.
4. Broadened Mobile Money Service Mix (Float Turn Optimization)
To maximize the profitability of an individual cash point, financial networks push agents to offer multiple digital-to-cash services.
- Domestic Money Transfers (DMT): Allowing walk-in customers without smartphones to deposit cash directly into external bank accounts.
- Utility Vending: Integrating utility bill payments, internet/cable subscriptions, and mobile airtime top-ups, which typically offer higher transaction margins (1.2%–5%) than baseline cash-outs.
- Float Circulation: Balancing daily deposits and withdrawals so cash continuously cycles within the shop floor rather than sitting idle or forcing emergency bank runs.
Security and Compliance Requirements for UPI Cash Withdrawal
Review the NPCI/UPI/OC-225/2025-26 Circular and the UPI Information Security Compliance Framework 2025 for the core security, transaction rules, and compliance standards governing UPI-based cash withdrawals.
Transaction Limits and Rules
- Per-Transaction Limit: ₹5,000 (standard MicroATM/UPI ATM cash-out rules cap ranges between ₹500 and ₹10,000 depending on the specific ATM network, with MicroATM rules capped at ₹5,000).
- Daily Limit: ₹10,000 per day for MicroATM/UPI cash withdrawals.
- Monthly Limit: ₹50,000 per month.
- Mandatory Two-Factor Authentication (2FA): Every transaction requires 2FA via mobile verification and UPI PIN approval.
- Ineligible Accounts: UPI LITE accounts and credit-type accounts are not permitted for best UPI cash withdrawal.
- Merchant Category Code (MCC) & Mode: Acquiring banks and Business Correspondents (BCs) must route these through MCC 6013, Purpose Code ’00’, and Initiation Mode ’15’ using a dynamic UPI QR code.
Core Security Protocols
- Dynamic QR Code Scanning: Replaces static or physical magnetic stripe/chip cards, eliminating physical card skimming, cloning, and shoulder-surfing of ATM PINs.
- Tokenized Identifiers: Replaces sensitive card and bank data with encrypted tokens during transmission.
- Device Binding: Cryptographically links the UPI app to the user’s verified mobile device hardware to block unauthorized remote access.
- AI-Driven Fraud Detection & Monitoring: Real-time analysis by participatingAeps india to flag abnormal behavior or exploitation.
Compliance & Governance (UPI Framework 2025)
- CISO Accountability: Independent Chief Information Security Officers (CISOs) must oversee risk linkages, direct reporting to senior leadership, and separation from IT operations.
- CIA Triad & Standards: Systems must uphold Confidentiality (encryption/tokenization), Integrity (hashing/digital signatures), and Availability (failovers/disaster recovery). Alignment is required with Zero Trust Architecture, ISO 27001, PCI DSS, and RBI mandates.
- Third-Party Application Aeps india (TPAP) Audits: Sponsor/PSP banks remain directly accountable for security audits and continuous compliance of the TPAPs and apps they onboard.
Common UPI Cash Withdrawal Problems and Their Solutions
Common UPI cash withdrawal (Cardless Cash Withdrawal via UPI-ATM) problems and their solutions span technical glitches, authentication errors, and security risks.
1. Money Debited from Bank Account, But ATM Did Not Dispense Cash
- Causes: Communication timeout between the UPI app, the National Payments Corporation of India (NPCI) server, the issuing bank, and the best Micro ATM machine; or a mechanical jam at the ATM dispenser.
Solution:
- Wait up to 1 hour for automated reconciliation and status updates from your bank.
- If the money is not auto-refunded within an hour, check your UPI app’s help or transaction history section (such as Google Pay, or Paytm) to Raise a Dispute or report a failed transaction.
- Contact your bank’s customer support with the UPI Transaction Reference Number.
2. Transaction Limit Exceeded
- Causes: Attempting to withdraw more than the per-transaction limit (capped at ₹10,000 per transaction for UPI-ATM) or exceeding your daily cumulative UPI limit (typically ₹1,000,000 / ₹1 lakh depending on the bank).
Solution:
- Ensure the cash withdrawal amount is entered in multiples of ₹100 and stays at or below ₹10,000 per go.
- Check your bank app Limits Guide / your specific bank rules to verify your remaining daily quota.
3. Wrong UPI PIN or Temporary Account Block
- Causes: Entering an incorrect UPI PIN multiple times (usually 3 consecutive failures) triggers a temporary 24-hour security block to protect your funds.
Solution:
- Reset your UPI PIN inside your payment app using your Debit Card details (last 6 digits and expiry date).
- Wait out the 24-hour cooling period if your account handle has been temporarily locked due to repeated authentication errors.
4. Fake QR Code Overlays or ATM Screen Tampering
- Causes: Fraudsters placing fake sticker QR codes over the dynamic QR code displayed on the ATM screen to divert cash-out requests.
Solution:
- Always inspect the physical ATM screen and bezel for loose stickers or tampered overlays before scanning.
- Confirm that the bank logo and official UPI prompt match the top Micro ATM machine interface. Never scan a QR code if you suspect a physical overlay.
5. Poor Internet or App Incompatibility
- Causes: Weak mobile data/Wi-Fi signal during the live QR scan and authorization window, or an outdated UPI app version.
Solution:
- Switch between mobile data and Wi-Fi or toggle airplane mode on and off before initiating the scan.
- Update your UPI application and mobile operating system to the latest version.
A Complete UPI Cash Withdrawal Platform
A UPI Cash Withdrawal Platform lets customers get physical cash without using a physical debit card, biometric scanner, or Aadhaar linkage, using only their smartphone and a UPI app at an ATM or authorized retailer.
How UPI Cash Withdrawal Works
At UPI-Enabled ATMs:
- Select the UPI Cash Withdrawal option on the ATM screen.
- Enter the desired withdrawal amount (typically in multiples of ₹100, up to a daily/per-transaction limit of ₹10,000).
- Scan the dynamic QR code displayed on the ATM screen using any UPI app (such as Google Pay, PhonePe, or Paytm).
- Authorize the transaction by entering your UPI PIN on your phone.
- Collect the cash dispensed by the machine.
At Retail / Merchant Cash Points (e.g., Kirana shops, Bank Mitra, or Business Correspondent outlets):
- The customer tells the retailer the needed cash amount.
- The retailer generates a dynamic QR code via their platform.
- The customer scans the QR code using their UPI app, enters their UPI PIN, and transfers the amount.
- The retailer hands over the physical cash from their counter.
ATM/MATM vs UPI Cash Point
ATM / MATM (Micro ATM) and UPI Cash Points represent two distinct generations of retail cash withdrawal systems in India. While traditional ATMs and Micro ATMs rely on hardware and physical debit cards or biometrics, a UPI Cash Point converts any smartphone-equipped retail merchant into a human-operated cash dispenser using standard dynamic QR codes.
Here is a direct, scannable breakdown of how these technologies compare across key operational factors.
ATM / MATM vs. UPI Cash Point
| Factor | ATM / MATM | UPI Cash Point |
|---|---|---|
| Customer Requirement | A physical debit card and ATM PIN (or Aadhaar + fingerprint for AePS). | Just a smartphone with any active UPI app and the UPI PIN. |
| Merchant Hardware | Requires a dedicated MATM device, card swipe machine, or biometric scanner. | Zero hardware needed; uses a dynamic QR code displayed on an Android screen or printed paper. |
| Transaction Limits | Typically up to ₹10,000 to ₹50,000+ per day, governed by card limits. | Usually capped at ₹5,000 per transaction and ₹10,000 daily. |
| Fraud & Security Risks | Risks of card skimming, cloning, or PIN exposure at physical points. | Cardless & secure; tokenized transactions where no sensitive details are shared with the merchant. |
| Merchant Onboarding | Slow & costly; involves procuring, provisioning, and maintaining hardware. | Instant activation; the merchant simply enables the feature on their partner app and starts scanning. |
| Earning Structure | Flat or variable payout depending on the specific device procurement model. | Earns a direct commission on every withdrawal, credited instantly to the partner wallet. |
Key Operational Snippets
1. How a UPI Cash Point Works (Merchant Flow)
- Initiation: The merchant opens their UPI Cash Point portal and enters the customer’s mobile number and desired cash amount.
- QR Generation: The app generates a single-use dynamic QR code.
- Scan & Pay: The customer scans this QR code using their preferred app (Google Pay, Paytm, etc.) and authorizes the transfer via their UPI PIN.
- Disbursement: The cash amount and the merchant’s commission are instantly credited to the merchant’s digital wallet, prompting them to hand physical cash to the customer.
2. Risk Mitigation & Compliance Rules
Because UPI Cash Points operate through human agents rather than automated machines, Aeps india enforce strict merchant guidelines to prevent fraud:
- No Screenshots: Merchants are strictly forbidden from taking photos or screenshots of the one-time dynamic QR codes.
- Mandatory Registers: Agents must maintain a physical register logging the customer’s name, mobile number, exact withdrawal amount, signature, and the Retrieval Reference Number (RRN).
- Cooling Periods: Systems enforce a 30-minute cooling period between consecutive transactions for the same user to check velocity attacks.
Cardless Cash Withdrawal vs. UPI-ATM Withdrawals
Cardless cash withdrawal and UPI-ATM withdrawals are closely related, as UPI-ATM withdrawals are actually a specific type of Interoperable Cardless Cash Withdrawal (ICCW) backed by the Reserve Bank of India (RBI) and the National Payments Corporation of India (NPCI).
Older traditional cardless cash methods and modern UPI-ATM methods differ primarily in how you initiate and authorize the transaction.
Comparison Overview
| Feature | Traditional Cardless Cash Withdrawal (NetBanking/OTP-based) | UPI-ATM Withdrawal (ICCW / Dynamic QR) |
|---|---|---|
| Initiation | Started via your bank’s mobile app, NetBanking, or ATM screen using your mobile number and an OTP. | Started directly at the ATM screen by choosing the UPI withdrawal option. |
| Authentication | Requires entering a mobile number, a temporary One-Time Password (OTP), and sometimes a specific transaction code. | Requires scanning a single-use dynamic QR code with a UPI app (like Google Pay, PhonePe, etc.) and entering your UPI PIN. |
| Interoperability | Often restricted or more cumbersome across different bank networks. | Fully interoperable across participating banks and ATM networks. |
| Transaction Limit | Typically up to ₹10,000–₹20,000 per transaction depending on the bank. | Up to ₹10,000 per transaction (with monthly RBI/bank limits applying). |
| Speed & Ease | Slower; involves pre-setting beneficiaries or dealing with SMS OTP delays. | Fast and immediate; scan-and-pay style flow at the machine. |
| Card Requirement | No physical card needed, but relies on pre-login or OTP generation. | No physical card needed; only a smartphone with a UPI app. |
Secure Banking with UPI ATM Systems
UPI ATM systems allow you to withdraw cash safely from an automated teller machine without using a physical debit card, utilizing the Interoperable Cardless Cash Withdrawal (ICCW) technology.
Security Benefits
- No Card Skimming or Cloning: Because you never insert a physical card into the machine, criminals cannot steal your card data through skimmers.
- Two-Factor Authentication: Transactions are secured by your phone’s lock screen security and your private UPI PIN.
- Dynamic QR Codes: The QR code on the screen changes for every single transaction, preventing replay or duplicate fraud.
- Automatic Reversals: If the cash fails to dispense due to an ATM error or timeout, the debited amount is automatically reversed to your bank account.
Aeps india one of the Best UPI Cash Withdrawal Solution Provider
Aeps india one of best UPI cash withdrawal or UPI Cash Point solution provider depends on several core technical, financial, and operational factors.
Key Factors to Consider
Transaction Technology & Infrastructure
- Switching & Reliability: Look for Aeps india built on robust backend switches that ensure high uptime and fast transaction response times.
- Hardware Independence: Check if the UPI Cash Withdrawal system requires physical hardware (like MATM machines or Aeps biometric scanners) or if it operates purely via dynamic QR code scanning on a smartphone or Android screen.
Commercial Terms & Earning Potential
- Commissions and Payouts: Evaluate the commission structure per transaction for agents or retailers (e.g., fixed payouts or percentage-based margins funded by Aeps india networks).
- Onboarding & Subscription Fees: Aeps india offer zero UPI cash point onboarding costs, no recurring monthly subscription charges, or hidden maintenance fees.
Security & Compliance
- Cardless Protection: Ensure the Aeps india supports Interoperable Cardless Cash Withdrawal (ICCW) or QR-based authentication, which eliminates physical debit cards, PIN exposure, and risks like card skimming or cloning.
- Regulatory Adherence: Verify compliance with National Payments Corporation of India (NPCI) and Reserve Bank of India (RBI) guidelines, multi-factor authentication, and device binding.
Developer & Integration Support (For APIs/B2B)
- API & Sandbox Access: If integrating into an existing business app or best UPI Cash Withdrawal platform, look for comprehensive UPI Cash Withdrawal API documentation, webhook support, live sandbox testing environments, and detailed reporting dashboards.
- Transaction Limits & Cooling Periods: Check the built-in limits per transaction, per day, or per month (such as standard ₹5,000 to ₹10,000 caps) and any mandatory cooling periods between consecutive transactions.
Network & Scalability
- Interoperability: Ensure customers can use any major UPI application seamlessly regardless of their issuer bank.
- Customer & Technical Support: Reliable 24/7 B2B Aeps india support and fast dispute/refund handling prevent cash flow bottlenecks at the counter.
Why Aeps india best for UPI Cash Withdrawal Solution
Aeps india for a UPI Cash Withdrawal Solution (whether for ATM infrastructure or retail/agent-assisted cash points like Aeps india stands out by offering zero hardware dependency, seamless interoperability, and strong security.
Key Qualities of the Best UPI Cash Withdrawal Provider
- No Hardware Dependency: Eliminates the need for physical debit cards, Aadhaar biometric fingerprint devices, or bulky micro ATM machines by relying purely on dynamic QR code generation and smartphone scanning.
- Interoperability: Allows customers to use any UPI-enabled app regardless of the bank that owns the ATM or agent counter.
- Enhanced Security: Combines two-factor authentication (smartphone + UPI PIN), eliminating physical card skimming, cloning, and shoulder-surfing risks.
- Zero or Low Onboarding Costs: Aeps india offer zero subscription fees, quick digital UPI Cash Withdrawal onboarding for retailers/agents, and high merchant credit/cash limits.
- Attractive Commission Structures: Empowers local kirana stores, mobile shops, and service centers to turn their counters into live cash-dispensing points while earning transaction commissions.
- Bypasses Traditional ATM Overhead: Reduces reliance on legacy card-switch networks and avoids standard physical card interchange fees.
Conclusion
A reliable UPI Cash Withdrawal Solution can help businesses explore convenient ways to provide cash access through supported UPI-enabled systems. For fintech startups, retailers, distributors, and entrepreneurs, the Aeps india can create new service opportunities while helping organize transactions, monitor operations, and serve customers who need access to cash. Before launching this service, it is important to understand the available Aeps india requirements, transaction process, and applicable operating guidelines.
When evaluating a UPI Cash Withdrawal Solution in India, look beyond the advertised features. Check supported transaction methods, participating Aeps india arrangements, transaction limits, customer authentication, settlement procedures, transaction-status tracking, failed-transaction handling, and technical support. Confirm how cash availability is managed and how complaints are handled when a transaction is pending, declined, or debited without cash being dispensed. Actual functionality depends on the supported system, Aeps india agreements, and applicable requirements.
The Interoperable Cardless Cash Withdrawal (ICCW) solution, commonly known as UPI-ATM, allows you to withdraw physical cash from enabled ATMs without using a debit or credit card. The entire transaction is completed securely by scanning a dynamic QR code using any UPI application (such as Google Pay, BHIM, or Paytm) on your smartphone.
Aeps India helps businesses explore digital banking software and integration options based on their operational needs. Depending on the selected solution and available integrations, businesses can assess features for transaction monitoring, retailer management, reporting, and related financial services. Before choosing a platform, verify that the Aeps india supports the specific UPI cash withdrawal model you intend to offer and that all required authorizations and banking arrangements are in place.
A well-planned UPI Cash Withdrawal Solution should combine a straightforward customer experience with secure transaction processing, transparent charges, clear receipts, and a reliable support process. Businesses should also test transaction flows, review settlement and reconciliation reports, and train staff to handle customer queries correctly. These steps can help reduce operational confusion and build trust.
Whether you are planning to launch a new digital banking service or expand an existing fintech business, selecting the Aeps india requires careful evaluation of technology, compliance, support, and long-term business needs. Choose a UPI Cash Withdrawal platform that fits your operating model rather than relying on price or marketing claims alone.
Looking for a UPI Cash Withdrawal Solution for your business? Contact Aeps India to discuss your digital banking software and integration requirements.
Contact Aeps India: https://aepsindia.com/contact-us
UPI Cash Withdrawal Solution with Aeps India
Looking for a UPI Cash Withdrawal Solution for your business? Contact Aeps India to discuss your requirements, explore available features, and learn more about setting up a suitable cash withdrawal service.
Frequently Asked Questions About UPI Cash Withdrawal Solution
A UPI Cash Withdrawal Solution enables eligible customers to access cash through a supported UPI-based service. Depending on the model, customers may receive cash from participating retail outlets or use a supported UPI-enabled ATM. The process, eligibility and transaction limits depend on the Aeps india and applicable rules.
The process depends on the withdrawal method. At a participating cash point, a customer may scan a transaction-specific QR code using a supported UPI application, authorize the payment and receive cash after successful confirmation. At a supported UPI ATM, the customer follows the ATM’s cardless withdrawal instructions and completes the required authorization.
UPI Cash Point is designed for cash access through participating retail outlets or service points. UPI ATM cash withdrawal enables cardless cash withdrawals at compatible ATMs through a supported UPI-based process. The two methods have different transaction workflows, infrastructure requirements and operating conditions.
Yes, supported UPI cash withdrawal methods can allow eligible customers to access cash without using a physical debit card. Availability depends on the participating outlet or ATM, the customer’s bank and UPI application, and the applicable authentication requirements.
A UPI Cash Withdrawal Solution for retailers allows eligible participating outlets to provide cash access through an authorized service arrangement. Depending on the UPI Cash Withdrawal platform, retailers may receive transaction records, payment status updates and reporting tools to help manage cash withdrawals.
A retailer should identify an authorized Aeps india, confirm business eligibility, complete the required onboarding and verification, and follow the Aeps india operational procedures. Before launching, confirm transaction limits, settlement arrangements, applicable charges, cash-handling requirements and customer complaint procedures.
A business-focused solution may include transaction-specific QR generation, payment confirmation, transaction-status tracking, transaction history, reconciliation, retailer management and reporting. The available features depend on the service model and Aeps india.
Not every UPI cash withdrawal method requires a biometric device. QR-based UPI Cash Point transactions and supported UPI ATM withdrawals use their respective authorization workflows. Biometric devices may be relevant to other services, such as AEPS, which uses a different authentication process.
Transaction limits depend on the withdrawal method, participating Aeps india, applicable payment-network rules and any operational restrictions. Retailers and customers should confirm the current limits for the specific service before initiating a transaction.
The customer should retain the transaction reference and payment confirmation, then contact the retailer and the relevant Aeps india through their official complaint channels. The transaction must be checked and reconciled before another withdrawal is attempted. The resolution depends on the actual transaction status and applicable procedures.
Yes. Network interruptions, delayed responses or processing issues can leave a transaction awaiting final confirmation. The retailer should verify the status through the authorized system and follow the Aeps india reconciliation process before handing over cash or initiating another transaction.
The cost depends on the service model, UPI Cash Withdrawal software requirements, UPI Cash point API integrate, hardware or infrastructure, UPI Cash Withdrawal API onboarding and ongoing support. Transaction charges and commercial terms may also apply. Request an itemized quotation that explains setup costs, recurring fees and any transaction-based charges.
Commission arrangements depend on the participating Aeps india agreement. Before joining, confirm whether commissions are offered, how they are calculated, when they are credited and whether any transaction fees or other deductions apply.
Yes. UPI cash withdrawal uses a supported UPI-based payment and authorization workflow. AEPS uses Aadhaar-based authentication through the applicable banking service and compatible biometric infrastructure. Their eligibility, transaction procedures, technical requirements and service arrangements differ.
Integration may be possible if the Aeps india offers suitable best UPI Cash Withdrawal API or other approved integration methods. Depending on the service, the implementation may involve QR generation, transaction-status checks, payment confirmation, callbacks and reconciliation. Confirm the Aeps india documentation, access requirements and integration terms first.
A solution should use secure transaction handling, verified payment status, appropriate access controls, protected customer information and reliable transaction records. Retailers should hand over cash only after the authorized system confirms successful payment, not merely because a customer displays a screenshot or an unverified notification.
Aeps india authorization and partner arrangements, supported transaction model, UPI Cash Withdrawal API onboard requirements, technical capabilities, settlement procedures, pricing, customer support and complaint-resolution process. Request written service terms and verify that the proposed solution meets applicable requirements.
Businesses interested in UPI Cash Withdrawal Solutions can contact AEPS India to confirm the services currently available, eligibility conditions, integration options, onboarding process and commercial terms. Verify the specific features and service arrangements before making a purchase or business commitment.
Start by explaining your business model, whether you need a retail cash point or an ATM-based solution, and whether you require software integration. Ask AEPS India for the available service details, onboarding requirements, transaction limits, pricing and support arrangements before proceeding.
Confirm the service model, Aeps india authorization, business eligibility, transaction limits, customer authorization workflow, payment confirmation process, cash availability, settlement arrangements, complaint handling and technical support. Test the complete transaction workflow before offering the service to customers.
AEPS Portal Benefits That Help You Earn More Commission
AEPS API for Recharge Software: Benefits & Integration Guide
AEPS Business: Complete Guide to Start and Earn in 2026
About Author

