B2B AEPS Software: Features, Benefits & Complete Guide
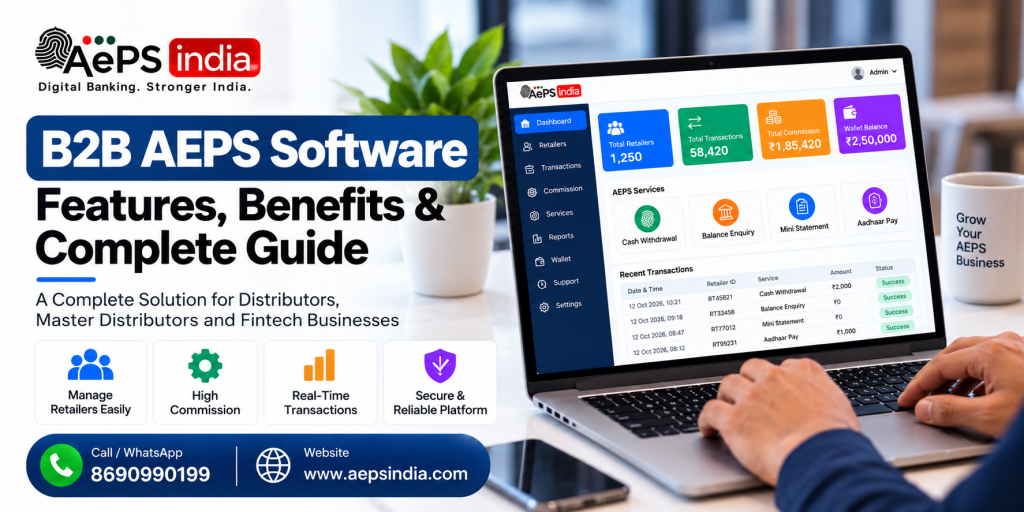
B2B AEPS Software is a digital banking solution that enables fintech businesses, distributors, retailers, and financial service providers to offer Aadhaar Enabled Payment System (AEPS) services through a centralized platform. It helps businesses manage retailer networks, monitor transactions, configure commissions, track wallet balances, and expand assisted banking services. If you want to launch your own AEPS business or add Aadhaar-based banking services to an existing fintech platform, choosing the right B2B AEPS Software is an important step.
A professional B2B AEPS Software platform can support essential services such as Aadhaar-based cash withdrawal, balance enquiry, mini statement, and other services available through the connected banking partner. Depending on the Aeps india and approved integrations, the platform may also support cash deposit, Aadhaar Pay, Micro ATM services, and additional digital financial services. These options allow businesses to serve customers through authorized retailers and service points, including areas where access to conventional banking facilities may be limited.
AEPS B2B software is a white-label or custom Aeps fintech platform that lets businesses, aggregators, and fintech startups run their own Aadhaar Enabled Payment System (AePS) and micro-banking network.
One of the most important features of B2B AEPS Software is its multi-level management system. An Aeps admin panel can help manage master distributors, distributors, retailers, user permissions, transaction limits, commission structures, and service activation. Other useful features include biometric device compatibility, Aeps API integration, wallet and settlement management, real-time transaction status, failed-transaction tracking, detailed reports, and role-based access controls. The exact features depend on the software package, banking integrations, and Aeps india.
For businesses planning to launch their own brand, White Label B2B AEPS Software can provide a branded Aeps portal with configurable business settings and retailer or distributor management. Before choosing a solution, compare the Aeps setup cost, supported banking services, Aeps API documentation, biometric requirements, transaction charges, settlement process, security controls, technical support, and compliance responsibilities. A low Aeps software price alone does not guarantee reliable transactions or a sustainable business model.
With Aeps India, businesses can explore AEPS software and Aeps API integration options for building or expanding their digital banking services. Depending on the selected solution, businesses can evaluate capabilities for retailer management, transaction monitoring, commission handling, reporting, and integration with other digital services. The right configuration should match your business model, expected transaction volume, network structure, and operational requirements.
In this complete guide, we will explain how B2B AEPS Software works, its key features, benefits, admin panel functions, retailer and distributor hierarchy, Aeps biometric device support, best Aeps API integrate, white label Aeps options, pricing considerations, and important factors to check before selecting a Aeps india. Whether you are starting a new AEPS business or expanding an existing fintech network, understanding these points can help you make a more informed top Aeps software decision.
What Is B2B AEPS Software?
B2B AEPS (Aadhaar Enabled Payment System) software is a business-to-business digital platform that allows fintech companies, banks, and service providers to empower a network of local retail agents and merchants to offer basic banking services.
B2B AEPS Software Work
B2B AEPS (Aadhaar Enabled Payment System) software turns local retail shops, kirana stores, and fintech networks into cardless, PIN-less “mini-banks” using biometric authentication.
How B2B AEPS Software Works
The transaction workflow proceeds through five main steps:
- Initiation: The agent enters the customer’s Aadhaar number and selects the bank.
- Biometric Authentication: The customer scans their fingerprint on a connected device.
- Identity Verification & Processing: Data is securely routed via UIDAI and NPCI to the destination bank.
- Completion: Real-time approval triggers cash disbursement or transaction confirmation.
AEPS Services Available Through B2B Software
Aadhaar Enabled Payment System B2B software empowers fintech companies, distributors, and local retail shops to act as mini-bank branches using biometric authentication.
Core AEPS Banking Services
- Cash Withdrawal: Allows customers to withdraw money from their bank accounts using their 12-digit Aadhaar number and a Aeps fingerprint or Aeps iris scan on a certified Aeps device.
- Cash Deposit: Enables authorized Business Correspondent (BC) points to accept and deposit cash directly into customer bank accounts linked to Aadhaar.
- Balance Inquiry: Provides instant checking of bank account balances via biometric or OTP authentication.
- Mini Statement: Generates a summary of recent bank account transactions for the customer.
- Aadhaar Pay: Lets merchants accept cashless, digital payments directly from a customer’s Aadhaar-linked bank account.
- Aadhaar-to-Aadhaar / Fund Transfers: Facilitates domestic money transfers (DMT) through IMPS or NEFT protocols.
Documents and Requirements for AEPS Software Setup
To set up an Aadhaar Enabled Payment System software, Aeps portal, or B2B/Aeps API system in India, you need specific KYC documents, hardware components, and technical prerequisites.
Required Documents for KYC & Onboarding
- Identity & Tax Proof: PAN Card (mandatory).
- Identity & Biometric Link: Aadhaar Card (with an active mobile number linked for OTP verification).
- Banking Proof: Cancelled cheque, updated bank passbook, or recent bank statement for wallet settlement.
- Business/Address Proof: Shop & Establishment Certificate, GST Registration, Udyam Registration, or a utility bill (electricity or water, 2–3 months old).
- Photographs: Recent passport-sized photographs.
- Contact Details: Active email address and operational phone number.
Hardware & Equipment Requirements
- Biometric Scanner: A UIDAI or STQC-certified Level 1 (L1) fingerprint or Aeps iris scanner device (such as Mantra).
- Device Software/Driver: Active Registered Device (RD) Service installed on your scanner for encrypted biometric capture.
- Computing Device: An Android smartphone/tablet (with USB OTG support) or a Windows PC/laptop.
- Internet Connection: A stable broadband, mobile data, or dongle connection to route real-time calls via the National Payments Corporation of India (NPCI).
- Physical Outlet: An established shop, office, or commercial counter to serve walk-in customers.
Software & Regulatory Setup Steps
- Choose a Aeps india: Partner with an authorized Aeps india.
- Complete KYC Verification: Submit your corporate/retail KYC documents and complete agent mapping (adhering to the single-operator/acquiring bank rules).
- Integrate Portal or API: Deploy the ready-made B2B web/mobile portal or integrate AEPS API into your existing Aeps platform.
- Install RD Service: Configure the biometric device drivers and test a trial balance inquiry or cash withdrawal transaction.
Who Needs B2B AEPS Software?
B2B AEPS software is needed by entities that want to build, manage, or scale a network of Aeps india.
Who Needs B2B AEPS Software?
- Fintech Startups & Software Providers: Aeps india building custom digital payment ecosystems or white label Aeps banking portal that need ready-made, NPCI- and RBI-compliant infrastructure without building bank connections from scratch.
- Super Distributors & Master Distributors: Entities managing large hierarchies of regional distributors and local merchants who need multi-layered Aeps admin panels to Aeps onboard agents, track transactions, and automate commission structures.
- Distributors: Middle-tier business networks that supply local retail touchpoints with micro-banking capabilities, balance tracking, and wallet-loading tools.
- Retail Chains & Multi-Outlet Businesses: Large commercial networks turning individual retail stores, general merchant shops, or local service centers into functional “mini-ATMs” to drive foot traffic and earn transaction commissions.
- Business Correspondents (CSPs) & Service Aggregators: Organizations acting as official banking correspondents that require centralized Aeps service software to process biometric cash withdrawals, deposits, mini-statements, and Aadhaar Pay software for customers in semi-urban and rural areas.
Why Need B2B AEPS Software
B2B AePS (Aadhaar Enabled Payment System) software is essential for businesses, fintechs, distributors, and local retail networks because it turns everyday shops into cardless, PIN-less digital banking touchpoints.
Key Reasons Businesses Need B2B AePS Software
- Turn Local Shops into Mini-ATMs: It enables neighborhood Aeps india to offer core banking services like cash withdrawals, cash deposits, balance inquiries, and mini-statements using only a customer’s Aadhaar number and fingerprint biometric scan.
- Create a Recurring Revenue Stream: Aeps india can build and manage a multi-tiered network (Admin, Super Distributor, Distributor, Retailer), earning Aeps commission or surcharge on every high-frequency transaction processed down the chain.
- Eliminate Licensing and Infrastructure Headaches: Businesses can launch full-scale assisted banking services immediately without needing to handle direct bank licensing, heavy compliance, or physical ATM hardware setup.
- Automate Network Management: Centralized Aeps B2B dashboard replace manual spreadsheets and phone calls with automated Aeps retailer onboarding, real-time transaction tracking, wallet management, and instant settlement (T+0) features.
- Expand Service Offerings: Modern Aeps platform integrate seamlessly with additional utilities like Best BBPS (Bharat Bill Payment System), mobile recharges, and Micro-ATMs, turning a single outlet into a complete financial hub.
- Promote Financial Inclusion: It bridges the banking gap in rural and semi-urban communities where traditional bank branches and ATMs are scarce.
- Bank-Grade Security & Compliance: Built-in multi-layer encryption, Aadhaar/UIDAI biometric verification, and adherence to NPCI and Reserve Bank of India (RBI) regulations protect every transaction against fraud.
Why B2B AEPS Software Growing in india
B2B Aadhaar Enabled Payment System (AEPS) software is growing rapidly in India because it turns local retail shops and small businesses into accessible, cardless “mini-banks” for rural and semi-urban communities.
Key Drivers of Growth
- Deep Financial Inclusion in Rural Areas: Millions of people in Tier 2, Tier 3, and rural regions lack nearby bank branches or ATMs. AEPS bridges this gap by allowing customers to use just their Aadhaar number and a fingerprint scan to bank locally.
- Cardless and Pinless Convenience: Customers do not need a debit card, credit card, or physical bank passbook to make transactions. Biometric fingerprint authentication makes the process secure and easy for first-time or uneducated users.
- New Revenue Streams for Retailers: B2B AEPS platforms allow local shopkeepers, kirana stores, and business correspondents to earn commission revenue on every cash withdrawal, balance inquiry, or mini-statement processed.
- White-Label and API Scalability: Aeps india can quickly deploy pre-built, white label AEPS Service software or integrate AEPS API into their own Aeps apps under their brand name.
- Multi-Service Convergence: Modern B2B AEPS platforms do not stop at basic banking. They bundle additional utilities like Bharat Bill Payment System (BBPS), mobile recharges, and best micro ATM services into a single Aeps dashboard.
- Government and NPCI Backing: Continuous national pushes toward a cashless, digital economy supported by the National Payments Corporation of India (NPCI) and UIDAI provide a solid regulatory foundation.
B2B AEPS Software for Master Distributors, Distributors and Retailers
B2B AEPS Software (Aadhaar Enabled Payment System) is a multi tier Aeps platform that lets fintech businesses, aggregators, and entrepreneurs manage a hierarchical network of Master Distributors, Distributors, and Retailers/Agents to deliver micro-banking services.
Multi-Tier Hierarchy
- Admin / Fintech Platform: Manages central switching, NPCI-compliant Aeps service API routing, and white label Aeps b2b operations.
- Master Distributor: Aeps Onboards downline distributors/retailers, manages commission structures, and handles wallet funding.
- Distributor / Sub-Distributor: Manages regional networks of local merchant agents.
- Retailer / CSP: Interfaces directly with end-users for biometric-authenticated transactions.
Why Choose B2B AEPS Software for Your Fintech Business?
B2B AEPS (Aadhaar Enabled Payment System) software lets fintech businesses, distributors, and local merchants offer cardless, biometric banking services using unique Aadhaar numbers and Aeps fingerprint system or Aeps iris scans system.
Key Reasons to Choose B2B AEPS Software
- New Revenue and Commission Streams: Retailers, agents, and distributors earn fixed commissions or transaction fees on every cash withdrawal, balance check, and mini-statement processed through the Aeps Service platform.
- Low Infrastructure Costs: It eliminates the need for expensive physical bank branches or complex hardware, requiring only a smartphone or computer, an internet connection, and a certified Aeps biometric scanner.
- Market Expansion into Rural Areas: You can easily penetrate unbanked, rural, or semi-urban communities where traditional ATMs and internet banking are scarce.
- Interoperable Multi-Banking Network: A single B2B AEPS platform connects to multiple banks via the National Payments Corporation of India (NPCI) network, letting you serve customers from almost any bank in India.
- Cardless and PIN-less Convenience: Customers do not need debit cards, credit cards, or physical PINs, as transactions authenticate instantly through live biometric verification.
- Hierarchical Agent Management: White label Aeps B2B solution come with built-in admin panels that let you manage multi-tier networks including Master White Label Aeps APP, Super Distributors, Distributors, and local agents/CSPs with real-time commission tracking and auto-settlements.
- Expanded Core Services: Beyond basic cash withdrawals and balance inquiries, modern Aeps software integrate Aadhaar Pay, Domestic Money Transfers (IMPS/NEFT), BBPS utility bill payments, mobile recharges, and micro-loans.
- Regulatory Compliance and Security: Built-in NPCI and RBI compliance, 256-bit encryption, and multi-factor authentication protect sensitive financial data and lower fraud risks.
Features B2B AEPS Software
B2B AEPS (Aadhaar Enabled Payment System) software enables Aeps india to operate a cardless, biometric-authenticated banking and micro ATM network.
Multi-Level Hierarchy & B2B Management
- Hierarchical Role Control: Multi-tier panels typically structured for Aeps Admin, Master White Labels, White Label Aeps Admin APP, Super Distributors, Distributors, and Retailers/CSPs.
- Commission & Slab Management: Automated calculation and real-time or T+0 crediting of partner and retailer commissions.
- Service ON/OFF Controls: Single-tap or granular toggle switches to enable or disable specific banking or utility services per agent or downline.
Technical & Security Features
- Biometric & UIDAI Compliance: Direct integration with UIDAI-certified Aeps fingerprint device/iris scanners and NPCI (National Payments Corporation of India) switches.
- Security & Encryption: End-to-end data encryption (often 256-bit security) and fraud-prevention protocols.
- API & White-Label Integration: Options for web portals, Android/iOS mobile apps with OTG device support, or direct B2B Aeps API integration into existing best Aeps software ecosystems.
- Real-Time Settlement & Payouts: Instant or automated payout and wallet settlement systems with comprehensive ledger reporting.
Benefits B2B AEPS Software
B2B AEPS (Aadhaar Enabled Payment System) software turns retail stores, micro-ATMs, and fintech networks into local banking touchpoints. It lets customers perform cardless and PIN-less transactions using their Aadhaar number and biometric fingerprint or iris scan.
Key Benefits of B2B AEPS Software
- New Revenue and Commissions: Retailers and network owners earn a commission or fee on every completed transaction, building a steady income stream.
- Low Infrastructure Costs: Businesses can offer banking services without building physical branches, installing expensive ATMs, or setting up heavy POS hardware.
- Greater Customer Footfall: Providing cash withdrawals, balance checks, and mini-statements draws more people into local shops and retail outlets.
- Financial Inclusion: Rural and semi-urban customers gain easy access to formal banking services right in their neighborhoods.
- High Security: Transactions use government-backed Aadhaar biometric verification, which reduces fraud risks and builds customer trust.
- Instant Settlements: Automated real-time processing and T+0 payout options keep working capital flowing smoothly.
- Multi-Level Network Management: Admin panels let businesses create and control super distributors, distributors, and retailers under a custom white label Aeps Application brand.
B2B AEPS Software Development
The B2B AePS software development process typically spans 3 to 8 weeks and involves building a multi-layered Aeps earning platform that connects local retailers or business correspondents (BCs) to national banking rails.
Step-by-Step Development Process
- Requirement Analysis & Scope Definition: Define target business models (White-label, Reseller, or Enterprise), service types (cash withdrawal, balance inquiry, mini-statements, Aadhaar-to-Aadhaar transfers), and multi-tier user hierarchies (Admin, Master Distributors, Distributors, Retailers).
- System Architecture & Database Design: Design Aeps software structure, cloud/server infrastructure, role-based access control (RBAC), and high-availability databases to handle real-time transaction logs.
- AEPS API Integration: Connect the Aeps commission platform with Aeps india team to handle live transaction requests, authentication calls, and bank routing.
- Biometric Device & SDK Integration: Integrate UIDAI-certified biometric hardware (fingerprint or iris scanners like Mantra) using manufacturer-provided Registered Device (RD) Services. Ensure raw biometric data is compressed and encrypted (e.g., AES-256) and never stored on local servers.
- Admin & Agent Dashboard Development: Build the backend best Aeps portal featuring wallet management, automated commission slabs, instant (T+0) settlement engines, e-KYC modules, and dispute Aeps management panel.
- Sandbox Testing & Quality Assurance: Run end-to-end tests in bank/NPCI sandbox environments to verify transaction flows, biometric payload delivery, failure handling, and security protocols.
- Compliance & Security Audits: Implement data encryption, anti-fraud monitoring, and strict KYC/AML compliance rules adhering to RBI and NPCI guidelines.
- Deployment & Go-Live: Deploy the web portal and Android/iOS mobile Aeps applications, activate distributor/retailer onboarding flows, and launch real-time transaction processing.
B2B AEPS Software Cost in India
B2B AEPS software cost structures in India range from ₹7,499 for basic Aeps developer setups to ₹4,50,000+ for direct bank enterprise integration, depending on whether you choose a white label Aeps package or a direct Aeps bank API.
1. One-Time Setup and Integration Fees
- Basic / Developer Integration: ₹7,499 – ₹15,000 (basic Aeps API and developer kits).
- Standard White-Label AEPS API: ₹12,000 – ₹35,000 (includes a pre built Aeps admin panel and shared gateway).
- AEPS Software Pack with Biometric Device: ₹20,000 – ₹50,000 (bundles admin/retailer apps and a fingerprint scanner).
- White-Label AEPS Portals / Turnkey Solutions: ₹25,000 – ₹1,20,000 (fully branded admin, distributor, and retailer panels).
- Direct Bank / Enterprise API (ICICI, Yes Bank, etc.): ₹1,50,000 – ₹4,50,000+ (dedicated server routing and direct bank partnership).
2. Recurring & Maintenance Costs
- Annual Maintenance Charges (AMC): ₹9,999 – ₹40,000 per year for server upkeep, security patches, and technical support. (Note: Often waived for the first year).
- Hosting, Domain & SMS Gateways: Variable yearly fees for cloud servers (AWS/DigitalOcean/etc.) and transactional SMS services.
3. Transaction & Commission Structure
- Per-Transaction Routing / Bank Fees: ₹0.50 to ₹1.50 (or ₹3 – ₹5 per standard withdrawal depending on the Aeps india).
- Agent / Retailer Commissions: Structured as a slab commission model where the top Aeps platform admin configures payouts (agents can earn up to ₹10–₹13 per cash withdrawal transaction depending on volume slabs).
- Aadhaar Verification (KYC) Fees: Roughly ₹20 per verification query if integrated.
B2B AEPS Software Commission
B2B AePS software platforms use a slab-based commission structure where earnings scale depending on the transaction type and amount. Admins and master distributors can configure custom margin distributions across their sub-distributor and retailer networks.
Typical AePS Cash Withdrawal Commission Slabs
- ₹100 – ₹999: ₹2.00
- ₹1,000 – ₹1,499: ₹3.00
- ₹1,500 – ₹1,999: ₹4.50
- ₹2,000 – ₹2,499: ₹5.50
- ₹101 – ₹3,500: 0.40% or slab-based
- ₹3,501 – ₹7,500: ₹11.00
- ₹7,501 – ₹10,000 (Sweet Spot): ₹13.00 to ₹14.50+ (up to ₹15+ per transaction depending on the Aeps india)
Non-Financial & Ancillary Services
- Balance Enquiry: ₹0.50 to ₹5.00 per transaction
- Mini Statement: ₹2.00 to ₹7.00 per transaction
- Aadhaar Pay (Merchant Payments): Roughly 1% of the transaction amount
B2B Hierarchy & Distribution Margins
In a white-label or Aeps B2B admin setup (such as those managed via Aeps platforms like Aeps india), the commission earned from the bank/NPCI route is split across the network tree:
- Admin / White-Label Owner: Retains a micro-margin or override per transaction.
- Master Distributor / Distributor: Earns a fixed or percentage override (e.g., flat ₹1 to ₹3 per withdrawal or share of volume).
- Retailer / Agent (CSP): Receives the primary slab commission (e.g., ₹2 to ₹15+ per withdrawal).
- Volume Bonuses: Aeps B2B platforms offer extra monthly payouts (e.g., ₹2,000+) if an agent hits high transaction targets (such as 150 to 200+ monthly transactions).
B2B AEPS Software Admin Panel
An AEPS B2B Admin Panel is a centralized backend Aeps dashboard that lets Aeps india server manage their Aadhaar Enabled Payment System network.
Core Features
- Hierarchical Role Management: Control multi-tier networks including Admin, Best White Label Aeps, Super Distributors, Distributors, and Retailers/CSPs (Customer Service Points).
- Commission & Wallet Engine: Configure custom slab- or percentage-based margins that auto-split and credit to agent, distributor, and Aeps admin wallet in real time.
- Transaction Monitoring: Track live biometric cash withdrawals, Aadhaar Pay API, balance inquiries, mini statements, and Domestic Money Transfers (DMT).
- API & Bank Switching: Integrate and switch between multiple Aeps banking API to maintain high transaction success ratios and 99.7%–99.9% uptime.
- White-Label Customization: Brand the web portal and Android/iOS mobile Aeps apps with your own company name, logo, and custom domain.
AEPS Wallet, Commission and Settlement Management
AEPS (Aadhaar Enabled Payment System) wallet, commission, and settlement management coordinate fund flows, agent margins, and liquidity for digital banking networks.
AEPS Wallet & Ledger Management
- Double-Wallet System: Separates funds into an AEPS Wallet (for incoming cash withdrawal liquidity and settlement) and a Main Wallet (for utility payments, recharges, or operational float).
- Liquidity & Float: Requires a working capital float (typically ₹50,000 to ₹1,60,000+) to disburse physical cash to customers at retail/Business Correspondent (BC) outlets.
- Ledger Tracking: Automatically logs debits, credits, passbook updates, and balance top-ups in real-time.
Commission & Margin Structure
- Agent Margins: Retailers and agents earn per-transaction commissions (roughly ₹7 to ₹15 per successful cash withdrawal or mini-statement, depending on the slab).
- Tiered Splitting: Aeps Admin platforms automatically split and credit override commissions across the hierarchy from Master Distributors and Distributors down to Retailers.
- TDS & Reporting: Automatically calculates and tracks Tax Deducted at Source (TDS) and generates downloadable earnings reports.
Settlement Management
- Instant & Same-Day Payouts (T+0 / T+1): The settlement engine controls fund transfers from the AEPS nodal bank straight to the agent’s virtual wallet or primary bank account.
- Multi-Bank Routing: Uses high uptime Aeps banking API (such as ICICI Bank or Axis Bank) to ensure real-time liquidity and failover protection.
- Escrow Protection: Pools and secures merchant/customer funds in compliance with Reserve Bank of India (RBI) and National Payments Corporation of India (NPCI) guidelines.
Security and Compliance Considerations for B2B AEPS Software
B2B Aadhaar Enabled Payment System (AePS) software requires strict adherence to regulatory guidelines, robust data protection, and continuous operator monitoring to prevent fraud and maintain Aeps india server.
Regulatory and Compliance Mandates
- RBI and NPCI Guidelines: Aeps payemnt Software must strictly comply with Reserve Bank of India (RBI) and National Payments Corporation of India (NPCI) directives governing digital payment ecosystems.
- AePS Touchpoint Operator (ATO) Framework: Under the RBI directive effective January 1, 2026, acquiring banks must execute enhanced Know Your Customer (KYC) and stringent due diligence for all last-mile agents and operators (ATOs).
- Operator Monitoring: Fast Aeps Platforms must feature tools for regular reviews, re-validation of inactive or high-risk operators, and automated compliance reporting.
Technical and Transaction Security
- Biometric Authentication: Integration with UIDAI-certified Aeps biometric devices (fingerprint or iris scanners) ensures that only verified customers authorize transactions.
- End-to-End Encryption: Sensitive customer data, Aadhaar numbers, and financial payloads must be encrypted both in transit and at rest.
- Real-Time Fraud Detection: AI-powered monitoring, transaction velocity checks, instant alerts, and automated audit trails help detect and block suspicious behavior.
- Role-Based Access Control (RBAC): Multi-tiered Aeps administrative panel restrict access based on user hierarchy (admins, distributors, and retail agents).
B2B AEPS Software vs Retailer AEPS Software
B2B AEPS Software and Retailer AEPS Software serve two completely different levels of the Aadhaar Enabled Payment System (AEPS) hierarchy, differing in scale, user rights, and business objectives.
B2B / Admin / White-Label AEPS Software
- Who it is for: Aeps india want to run or manage an entire banking network.
- Core purpose: Infrastructure management, network creation, and system control.
Key capabilities:
- Network Hierarchy: Ability to create and manage master distributors, distributors, and sub-agents (retailers).
- Commission Control: Custom-configure commission slabs, distributor margins, and retailer payouts.
- White-Label Branding: Launch an AEPS portal or mobile app under your own company name, logo, and domain.
- API & Backend Access: Direct developer-friendly API integrations to embed biometric banking into larger platforms.
- Monitoring & Reconciliation: Live transaction tracking, ledger management, automated settlement reports, and dispute/complaint handling.
Retailer / Agent AEPS Software
- Who it is for: Single shop owners, local kirana stores, Common Service Centers (CSCs), and individual Business Correspondents (BCs).
- Core purpose: Executing frontline, customer-facing micro-banking transactions.
Key capabilities:
- Customer-Facing Services: Process cash withdrawals, balance inquiries, mini-statements, and Fast Aadhaar Pay API.
- Biometric Authentication: Connect UIDAI certified Aeps fingerprint or UIDAI certified Aeps iris scanners to a smartphone or PC to verify customer identities.
- Instant Settlements: Real-time or fast wallet crediting and immediate commission updates for each completed swipe/scan.
- Simplicity & Access: Low-cost, ready-to-use mobile Aeps b2b app or web login designed for non-technical shopkeepers.
Key Comparison at a Glance
| Feature | B2B / Admin AEPS Software | Retailer / Agent AEPS Software |
|---|---|---|
| Primary User | Fintech companies, administrators, distributors | Local kirana merchants, individual agents |
| Operational Scope | Manages thousands of users and multi-tier networks | Operates a single point-of-sale/mini-ATM terminal |
| Revenue Model | Earns a cut/override from every transaction across the network | Earns a direct commission per customer cash withdrawal or inquiry |
| Technical Setup | White label Aeps portal, Aeps API gateway, admin dashboard | Ready mobile/web app paired with a biometric scanner |
B2B AEPS Software vs AEPS API: What Is the Difference?
An AEPS API is a technical code bridge that lets you plug Aadhaar-based banking features into an existing app or website, while B2B AEPS Software (often a white label Aeps admin portal or complete Aeps platform) is a ready-to-use, multi-tiered business system that includes trusted Aeps admin panels, agent networks, and commission modules out of the box.
Core Differences
| Feature | AEPS API | B2B AEPS Software (Portal / White-Label) |
|---|---|---|
| What it is | A backend code interface/protocol. | A complete, turnkey software product/dashboard. |
| Who builds it | You (or your dev team) build the UI and workflows using the fast Aeps API. | The Aeps india provides a pre-built web and mobile application. |
| Hierarchy & Management | Just the raw transaction connector; no built-in agent structure. | Includes multi-level panels like Super Admin, Distributor, and Retailer/Merchant. |
| Best For | Fintech companies building a custom, proprietary app from scratch. | Entrepreneurs, white-label partners, or startups wanting to launch an instant B2B agent network. |
| Development Effort | High (requires custom programming, UI/UX design, and compliance handling). | Low to none (ready-to-use, branded deployment). |
AEPS API Breakdown
- Function: Acts as a data pipe connecting your platform to the NPCI and banking switch via encrypted channels.
- Control: Gives you complete control over the user interface, customer experience, and custom logic.
- Requirements: You must develop your own database, wallet ledger, commission engine, and Aeps admin dashboards.
B2B AEPS Software Breakdown
- Function: A full-stack business management suite that comes with pre-integrated Aeps API, ledger systems, and device compatibility.
Management Tiers:
- Super Admin Panel: Controls the entire ecosystem, profit margins, and master ledgers.
- Distributor Panel: Aeps Onboards local retailers, manages regional wallets, and distributes commissions.
- Retailer / Merchant Panel: Used by shop owners to run biometric scans and cash withdrawals.
- Turnkey Setup: Often delivered as a white label Aeps solution so you can brand Aeps platform under your own company name immediately.
White-Label B2B AEPS Software for Your Own Brand
You can launch a branded digital Aeps banking platform using a AEPS India.
Key Features of White-Label B2B AEPS Software
- Custom Branding: Your own company logo, custom domain name, web portal, and Aeps Android app.
- Core Banking Services: Aadhaar Enabled Payment System (AePS) for cash withdrawals, balance inquiries, and mini-statements using biometric authentication.
- Value-Added Services: Domestic Money Transfer (DMT), Best Bharat Bill Payment System (BBPS), mobile/DTH recharges, and micro-ATMs.
- Multi-Level Hierarchy: Admin panel to create and manage super-distributors, distributors, and retailer networks with custom commission slabs.
Aeps india One Of The Best B2B AEPS Software Provider in India
Aeps india one of the best B2B Aadhaar Enabled Payment System (AEPS) software provider, you must evaluate technical reliability, security compliance, business structures, and financial terms.
Key Factors to Evaluate
- Security & Compliance: Ensure the secure Aeps software strictly complies with NPCI and UIDAI guidelines, featuring end-to-end HTTPS encryption, multi-factor authentication (2FA), and secure biometric data handling.
- Transaction Success Rate & Uptime: Look for Aeps india offering high Aeps API uptime (ideally 98% or higher) and intelligent multi-bank routing to minimize failed transactions and drop-offs.
- Settlement Speed: Fast real-time or same-day payout and settlement cycles are crucial to maintaining healthy cash flow for your retail network.
- Multi-Bank Interoperability: The seamless Aeps platform must connect to a wide, reliable network of banks so agents can process transactions regardless of the customer’s bank
- Distributor & Retailer Hierarchy: A strong Aeps B2B platform should support multi-tier management (Super Distributor, Master Distributor, Distributor, and Retailer) with automated commission tracking and distribution.
- White-Label Customization: If you want to run the business under your own brand, verify whether the Aeps india offers a white label AEPS b2b portal with complete backend control.
- Integrated FinTech Services: Choose a Aeps india that bundles AEPS with complementary services such as Micro-ATM, DMT (Domestic Money Transfer), BBPS (Bill Payment System), and mobile recharges to maximize agent revenue.
- Transparent Pricing & Costs: Understand the cost breakdown, including setup fees, standard Aeps software/white-label licensing costs, annual recurring fees, and commission structures (typically 0.5% to 1% or slab-based commissions). Look out for hidden charges.
- Developer Documentation & Support: Clear best Aeps API documentation, a functional sandbox environment for testing, and responsive technical support are essential during integration and production issues.
How Aeps India Helps Businesses Choose a B2B AEPS Solution
Aeps india one of the B2B AePS solution provider helps businesses by supplying the complete technical infrastructure, bank connectivity, compliance management, and agent-network tools needed to offer biometric banking services.
Key Ways Aeps india Help Businesses Choose & Implement AePS
- Infrastructure & NPCI Compliance: Aeps india run on pre-approved National Payments Corporation of India (NPCI) and RBI-compliant architecture, sparing your business from independent, time-consuming banking certifications.
- Partner Model Selection: Aeps india offer flexible deployment structures such as White Label Aeps platforms, Reseller networks, or Enterprise models to match your company’s scale and network hierarchy.
- Core Banking API & Multi-Bank Support: Aeps india integrate multi-bank connectivity so retailers can process transactions (cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay) across almost any major Indian bank.
- Network & Dashboard Management: They deliver Aeps administrative dashboard to onboard distributors and retailers, manage KYC documents, assign member IDs, and monitor transaction health.
- Automated Commission Slabs: Top Aeps System automatically calculate and settle commissions in real time for every cash withdrawal or banking query processed by your agent network.
- Security & Uptime: Aeps india ensure high uptime (typically 99%+), multi-layer security, fast processing, and 24/7 technical support.
Conclusion: Choose the Right B2B AEPS Software for Your Business
Choosing the right B2B AEPS Software is essential for businesses that want to offer Aadhaar Enabled Payment System (AEPS) services through a structured network of retailers and distributors. A reliable Aeps platform should do more than process transactions. It should help businesses manage users, monitor transactions, control commissions, track settlements, and maintain clear operational records through a centralized Aeps administration system.
When comparing B2B AEPS Software, look for essential services such as Aadhaar-based cash withdrawal, balance enquiry, mini statement, and other supported banking services. Important features include an admin panel, master distributor and distributor management, retailer onboarding, wallet management, commission configuration, transaction reports, failed-transaction tracking, biometric device compatibility, Aeps API integrated, and responsive technical support. Available services and transaction limits may vary depending on the Aeps india and applicable requirements.
B2B AEPS (Aadhaar Enabled Payment System) Software is a business-to-business platform that lets fintech companies, banks, distributors, and local retailers offer cardless, PIN-less banking services using Aadhaar biometric authentication.
For growing fintech businesses, a scalable B2B AEPS Software Solution can make it easier to manage multiple retailers, organize commission structures, monitor business activity, and expand into additional digital services. Before choosing a Aeps india, compare integration requirements, pricing, settlement terms, security practices, device support, service availability, and the quality of technical assistance rather than focusing only on the initial cost.
With Aeps India, businesses can explore brand AEPS software and Aeps API solutions for building or expanding their digital banking service operations. Depending on the selected solution, businesses can evaluate features for retailer and distributor management, transaction monitoring, commission management, wallet operations, reporting, and supported biometric integrations.
If you are planning to launch AEPS business, upgrade an existing platform, or build a larger retailer and distributor network, choose B2B AEPS Software that matches your current requirements and future growth plans. The right combination of reliable integration, transparent pricing, strong administration tools, secure transaction handling, and dependable support can help you build a more organized and scalable AEPS service business.
Ready to explore B2B AEPS Software for your business? Contact Aeps India to discuss your requirements, available features, integration options, and pricing.
Contact Aeps India: https://aepsindia.com/contact-us
FAQs for B2B AEPS Software with Aeps india
B2B AEPS Software is a digital banking platform that enables fintech businesses, distributors, and retailers to provide Aadhaar Enabled Payment System (AEPS) services through an authorized banking network. It can include an admin panel, Aeps retailer portal, distributor management, transaction history, commission tracking, and settlement reports, depending on the Aeps india.
B2B AEPS Software connects an authorized retailer or banking outlet with the AEPS transaction infrastructure. After the customer provides the required Aadhaar details and completes biometric authentication, the transaction request is processed through the connected banking system. The Aadhaar Enabled Payment System software then displays the transaction status and records the available transaction details.
Look for retailer and distributor management, an admin dashboard, transaction monitoring, commission configuration, wallet or ledger management, settlement reports, role-based access, transaction history, customer support, and Aeps API integration options. Confirm which features are included in the Aeps india actual offering before selecting a platform.
Fintech entrepreneurs, digital banking service providers, distributors, master distributors, and eligible retailers may use AEPS B2B Software to build or expand their service networks. Access to AEPS transactions depends on the Aeps onboarded requirements, applicable authorizations, KYC checks, and banking arrangements.
Yes, you may be able to start an AEPS distribution or retail business by partnering with a suitable Aeps india. Before starting, evaluate the Aeps setup cost, onboarding process, required documents, transaction limits, commission terms, and ongoing support.
A regular AEPS portal may focus mainly on providing banking transactions to an individual retailer. B2B AEPS Software is generally designed for business networks that need to manage multiple retailers, distributors, user roles, commissions, and transaction reports through a centralized Aeps bank platform. The exact difference depends on the features offered by the Aeps india.
Many B2B AEPS platforms support a hierarchy of administrators, master distributors, distributors, and retailers. Depending on the software configuration, businesses can manage user accounts, onboarding status, permissions, transaction activity, and commission settings from a central dashboard.
Commission management allows a business to configure or track earnings according to the applicable transaction type, amount slab, partner agreement, and distribution hierarchy. Before choosing a Aeps india, check the commission rates, eligibility conditions, deductions, settlement schedule, and transaction-wise reporting. Actual earnings depend on transaction volume and the agreed commercial terms.
The cost of B2B AEPS Software varies according to the licensing model, white-label requirements, number of users, API integrations, customization, support, and transaction infrastructure. Aeps india offer subscription or partner-based models, while customized trusted Aeps platform may involve separate development and maintenance charges. Request a detailed quotation before making a decision.
Aeps india offer white label Aeps solutions that allow eligible businesses to use their own brand identity on the portal or application. Depending on the agreement, customization may include branding, domain configuration, retailer access, and dashboard settings. Confirm the available customization options, ownership terms, and ongoing fees before signing up.
A B2B AEPS admin panel can help authorized administrators manage users, monitor transactions, review reports, configure permitted settings, and track business activity. Advanced capabilities may include distributor hierarchy management, commission reports, wallet ledgers, and user access controls. Available functions vary by Aeps india.
Yes, Aeps india offer APIs for integrating AEPS services into an existing fintech portal, website, or application. Before integration, check the best Aeps API documentation, authentication method, supported transaction types, callback or webhook support, error responses, testing environment, and commercial terms. High speed Aeps API access and production activation depend on the arrangements.
Security depends on the Aeps software architecture, authorized banking connections, biometric processing arrangements, access controls, data handling, and operational safeguards. Businesses should verify applicable compliance requirements, encryption practices, audit logs, access permissions, and incident-support procedures. They should also follow applicable Aadhaar authentication and data-protection requirements.
Depending on the authorized Aeps india and connected banking infrastructure, Best AEPS may support cash withdrawal, balance enquiry, and mini statement services. Other capabilities must be confirmed separately because not every high Aeps platform or banking arrangement supports the same transactions.
A suitable B2B AEPS platform may provide transaction history, reference numbers, status information, commission records, and settlement reports. When a transaction is pending or its status is unclear, check the reference number and reconciliation records, then follow the Aeps india official support process before attempting another transaction.
First, check the transaction status and reference number in the portal. Review the reconciliation process and wait for the official status update where required. If the status remains unresolved, contact the authorized Aeps india with the transaction details. Avoid repeating a transaction until its status has been verified to reduce the risk of duplicate debits or withdrawals.
Requirements depend on whether you are registering as a retailer, distributor, or business partner. They may include identity and address documents, PAN details, bank account information, business documents, photographs, and applicable KYC records. Ask the Aeps india for its current document checklist and complete the required verification before activation.
Best Aeps india on authorized banking connectivity, transaction reliability, available features, transparent commission terms, settlement and reconciliation processes, fast Aeps API documentation, security controls, onboarding requirements, pricing, and customer support. Request a product demonstration and review the agreement carefully before committing to a high commission Aeps platform.
Businesses considering B2B AEPS Software from Aeps india should evaluate the available retailer and distributor management features, transaction reporting, commission visibility, integration options, onboarding assistance, pricing, and technical support. Request a demonstration and confirm the specific features, banking arrangements, and commercial terms available for your business model.
To get started, contact Aeps india to discuss your business model, expected retailer network, required best AEPS services, and integration needs. Review the available Aeps business software options, onboarding documents, pricing, commission structure, and service terms. Proceed with activation after the relevant verification and authorization requirements have been satisfied.
AEPS Banking Software in India – Secure, Scalable & Complete AEPS Platform
Best AEPS API Providers in India for Startups and Retailers
AEPS Application: Complete Guide for Retailers and Businesses
About Author

