UPI Cash Point Software: How It Works, Features and Benefits
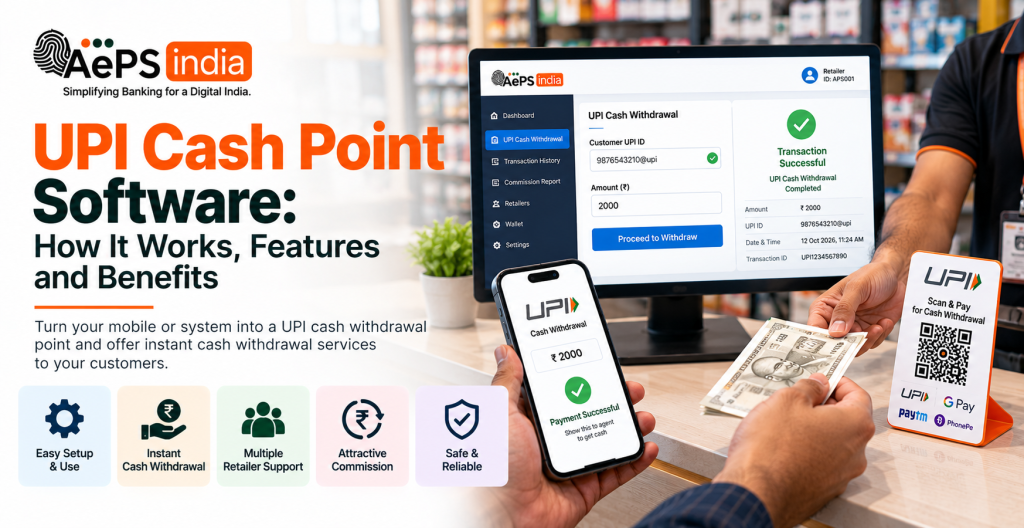
UPI Cash Point Software Work by connecting a customer’s UPI-enabled payment process with an authorized cash point merchant and the relevant payment service infrastructure. It is designed to support cash withdrawal workflows through participating merchants, helping customers access cash without relying only on traditional ATMs. For fintech companies, distributors, retailers, and digital service businesses, understanding how UPI Cash Point software works is important before choosing a technology solution.
A suitable UPI Cash Point software platform can help businesses manage retailer accounts, monitor transaction status, maintain transaction records, and organize day-to-day operations through an administrative dashboard. Depending on the Aeps india and UPI Cash Point API integration, it may also support partner management, reporting, commission tracking, and settlement-related records. The exact features and transaction process depend on the authorized Aeps india and the supported payment system.
A UPI Cash Point Software is a digital platform that lets local retail shops, Kirana stores, and business correspondents turn their counters into cardless cash-dispensing points.
The process generally starts when a customer requests a cash withdrawal at a participating merchant. The merchant initiates the supported transaction workflow, and the customer completes the required authorization through their UPI application. The payment system verifies the transaction, and the merchant provides cash only after receiving the appropriate confirmation. The software can then record the transaction status for monitoring and reconciliation.
For businesses planning to enter this segment, selecting a Aeps india requires more than checking the available features. It is important to evaluate UPI Cash Point API integrate, transaction-status updates, access controls, reporting, technical support, scalability, and the Aeps india authorization and compliance requirements.
Aeps India can be contacted to discuss your fintech software requirements and explore suitable options for building or expanding a digital financial services business. Before proceeding, confirm whether the required UPI Cash Point service, payment integration, and merchant onboarding facilities are available for your intended business model.
In this guide, we explain how UPI Cash Point software works, its key features, transaction workflow, business benefits, integration considerations, and the factors to evaluate when choosing a Aeps india. This will help you understand the process and make a more informed decision for your business.
What is UPI Cash Point Software?
UPI Cash Point Software is a digital platform and application framework launched under guidelines from the National Payments Corporation of India (NPCI) that turns local retail shops, Kirana stores, pharmacies, and Business Correspondent (BC) outlets into cardless cash withdrawal points.
How Does UPI Cash Point Software Work?
UPI Cash Point Software allows local shops, Kirana stores, and Business Correspondent (BC) outlets to act as cardless cash withdrawal spots using real-time NPCI (National Payments Corporation of India) UPI infrastructure.
How the Process Works
- Request Cash: A customer visits a registered merchant or agent and asks for physical cash.
- Enter Amount: The merchant types the requested withdrawal amount into the UPI Cash Point software or app.
- Dynamic QR Generation: The software calls a dynamic QR generation API to create a unique, single-use payment QR code tied to that exact transaction.
- Scan Code: The customer opens any UPI-enabled app on their smartphone and scans the dynamic QR code.
- PIN Authorization: The customer enters their secure UPI PIN in their app to approve the withdrawal.
- Verification & Payout: The banking network processes and validates the transfer instantly, showing a confirmation on both the merchant and customer screens. The merchant then hands over the physical cash to the customer.
Who Can Use UPI Cash Point Software
Eligible retailers, local business owners, and financial service providers can use UPI Cash Point Software to turn their store counters or agent networks into cardless cash-dispensing points.
Who Can Use the Software and Services
- Kirana & General Stores: Neighborhood grocery and daily-needs shops can register as cash points to provide cash-out services to local residents.
- Medical & Pharmacy Outlets: Chemist and medical shops can enable UPI cash withdrawals alongside regular health and pharmacy sales.
- Mobile & Electronics Shops: Retail stores selling phones, recharges, and electronics can offer digital-to-cash services.
- Common Service Centers (CSC): Rural and semi-urban digital service kiosks use the platform to bridge local cash gaps where physical ATMs are scarce.
- Bank Mitras & Business Correspondents (BC): Authorized banking agents can dispense cash without needing heavy biometric or card-swipe machines.
- Fintech & B2B Software Providers: Companies can white-label or integrate the UPI Cash Point API into their own dashboards to manage large distributor and retailer networks.
How Aeps india Helps UPI Cash Point B2B Partners?
UPI Cash Point providers such as Aeps india help B2B partners, distributors, and local merchants transform retail counters into cardless cash-dispensing points.
Key Ways Providers Support B2B Partners
Centralized Dashboard & Management:
- Provide UPI Cash Point admin panel to onboard, manage, and monitor a network of distributors and retail agents from a single interface.
- Track real-time transactions, settlement metrics, and network activity.
API & Software Integration:
- Offer plug-and-play UPI Cash Point API and white label UPI Cash Point software that integrate into existing B2B fintech applications or merchant networks.
- Handle backend switching infrastructure (such as banking switches) to process real-time payment requests.
Zero Hardware Dependency:
- Eliminate the need for physical ATM hardware, biometric scanners, or debit card machines, keeping setup and scaling costs low for retailers.
Dynamic QR & Intent Generation:
- Automate the creation of unique, single-use dynamic UPI QR codes or payment intent requests for every cash-out transaction to ensure security and traceability.
Revenue & Footfall Growth:
- Enable partners to offer an extra financial service (cash-out) that attracts higher store footfall and generates transaction-based commissions or earnings for retailers and distributors.
UPI Cash Point Transaction Limits, Rules and Requirements
You can withdraw cash using UPI at Business Correspondent (BC) touch points and UPI-enabled ATMs following specific National Payments Corporation of India (NPCI) and Reserve Bank of India (RBI) guidelines.
1. UPI Cash Point / MicroATM (Business Correspondent Touch Points)
- Per-Transaction Limit: ₹5,000
- Daily Limit: ₹10,000
- Monthly Limit: ₹50,000
- Authentication: Mandatory Two-Factor Authentication (2FA) via UPI PIN.
- Eligible Accounts: Savings or Current accounts only; UPI LITE and credit-type accounts are excluded.
- MCC & Purpose Code: Merchant Category Code (MCC) 6013 with Purpose Code
00and Initiation Mode15.
2. UPI-ATM Cash Withdrawals (Interoperable Card-less Cash Withdrawal / ICCW)
- Per-Transaction Limit: ₹10,000
- Daily Limit: Subject to your standard daily UPI limit (typically up to ₹1,00,000) or individual bank limits.
- Process: Scan a single-use dynamic QR code displayed on the ATM screen using any UPI app and authorize with your UPI PIN.
- Eligible Accounts: Savings or current accounts linked in your app (supports multiple linked accounts).
- Charges: Standard ATM usage rules apply (free transactions count towards your monthly bank/ATM quota, followed by standard fees like ₹23 + GST per transaction).
Key Rules & Requirements
- No Debit Card Needed: You only need a smartphone with an active internet connection and a UPI-enabled app.
- Excluded Payment Methods: You cannot use UPI LITE or RuPay Credit Cards on UPI for cash-out/withdrawal services.
- Bank-Level Caps: Individual banks may enforce stricter lower limits than the maximum NPCI thresholds. Always check the limit screen inside your UPI app before completing a withdrawal.
How Does UPI Cash Point Software Process a Transaction?
UPI Cash Point software processes a cash withdrawal transaction by connecting the customer, the retail merchant/agent, the banking network, and the NPCI switch through a single dynamic QR-based workflow.
Step-by-Step Transaction Process
- 1. Onboarding and Setup: B2B partners and retail agents register with a Aeps india and integrate the UPI Cash Point API or admin panel into their UPI Cash Point platform.
- 2. Request Cash Withdrawal: The customer visits the registered merchant and requests a physical cash payout. The merchant enters the requested withdrawal amount (typically capped around ₹5,000 per transaction at retail points) into the UPI Cash Point software or app.
- 3. Dynamic QR Generation: The UPI Cash Point software communicates with the acquiring bank or UPI switch to generate a unique, single-use dynamic QR code tied strictly to that cash-out value.
- 4. Customer Scan & Authentication: The customer opens a UPI-enabled app on their smartphone and scans the dynamic QR code displayed by the merchant.
- 5. UPI PIN Authorization: The customer selects their preferred linked bank account and enters their secret UPI PIN inside their mobile app to authorize the payment.
- 6. Network & Risk Verification: The transaction routes through the NPCI UPI switch for fraud and risk checks (FRM/EFRM), debiting the customer’s bank account and crediting the merchant or agent pool account.
- 7. Real-Time Confirmation & Payout: Once the UPI Cash Point software and merchant dashboard receive an instant confirmation webhook/status update from the network, the merchant hands over the physical cash to the customer.
How Does Money Move in a UPI Cash Point Transaction?
In a UPI Cash Point transaction (such as at a UPI-enabled ATM or a local retail cash point), money moves digitally from Aeps india, while physical cash is handed to you by the machine or retailer.
Step-by-Step Flow of Money
Initiation & Request
- You enter or select the cash withdrawal amount on the ATM screen or tell a local merchant/agent.
- The ATM or the retailer’s app generates a single-use dynamic QR code linked to that specific transaction amount.
Scanning & Authorization
- You open your UPI app and scan the dynamic QR code.
- The app displays the amount and the destination (the ATM network or the merchant’s settlement account).
- You authorize the transaction by entering your UPI PIN on your smartphone.
Backend Clearing and Settlement (NPCI & Banks)
- The authorization message is processed through the Aeps india server switch.
- Funds are debited directly from your linked bank account via IMPS (Immediate Payment Service) or the underlying UPI rails.
- The money is transferred to the ATM operator’s bank account or the retailer’s/business correspondent’s merchant settlement account.
Cash Dispensation & Commission
- Once the bank confirms the debit, a signal is sent back to the ATM machine or the retailer to release the physical cash.
- At an ATM: The machine dispenses the physical currency notes to you.
- At a Retail Cash Point: The local shopkeeper or agent hands you physical cash from their float, while a small commission (ranging from ₹2 to ₹14 per transaction) is credited to the retailer by the Aeps india.
Role of UPI Cash Point Software in Cash Withdrawal
The UPI Cash Point Software acts as a centralized B2B digital bridge that allows neighborhood retailers, kirana shops, and Business Correspondents (BCs) to function as human-operated micro-ATMs.
Core Role and Functions
- Cardless Cash Dispensing: Replaces physical debit cards and biometric AePS hardware with smartphone-based QR code scans.
- Dynamic QR Generation: Automatically generates a single-use dynamic QR code on the merchant’s screen or device for the exact cash amount requested.
- Real-Time Settlement & Dashboard: Connects local merchants, fintech distributors, and core banking systems (CBS) through a single management dashboard to track cash-outs, liquidity, and ledgers.
- Two-Factor Authentication: Uses the customer’s UPI app and UPI PIN to authorize the digital transfer, after which the merchant hands over the physical cash.
- Agent Monetization: Calculates and credits direct commission earnings (typically ₹2 to ₹14 per transaction) to the retailer or BC for providing liquidity.
UPI Cash Point Software Dashboard: Main Functions
A UPI Cash Point Software Dashboard is a centralized platform for Aeps india server to manage cardless cash withdrawal services.
Main Functions of the Dashboard
- Live Transaction Feed: Monitor real-time UPI cash-out statuses, success and failure rates, and unique RRN (Retrieval Reference Number) or UTR tracking references.
- Dynamic QR Generation & Requests: Create single-use, time-bound dynamic QR codes for customer cash withdrawals.
- Liquidity & Wallet Overview: Track main merchant/partner balances, working capital, commission earnings, and settlement pools.
- Retailer & Agent Management: Onboard, verify, and manage a network of local merchants, Business Correspondents (Bank Mitras), and distributors.
- API Integration & Status Controls: Manage best UPI Cash Point API, status inquiry checks, and staging/production webhooks.
- Alerts & Notifications: Receive automated and visual triggers for failed callbacks, low merchant cash floats, or disputed/flagged payouts.
- Settlement & Reporting: Access real-time transaction logs, daily balance reconciliations, and payout audit reports.
How Retailers, Distributors and Admins Use the UPI Cash Point Software
UPI Cash Point software acts as a centralized B2B and merchant platform that turns local shops into cardless cash withdrawal centers using dynamic QR codes and NPCI-backed UPI infrastructure.
1. How Retailers Use the Software
- Turn Shop into a Mini-ATM: Retailers (kirana, medical, or general stores) log into their Aeps india and select the UPI cash-out or QR ATM option.
- Generate Dynamic QR Codes: The retailer enters the requested cash withdrawal amount and the customer’s phone number into the software, which immediately generates a transaction-specific dynamic QR code.
- Process Customer Scans: The customer scans the QR code using any UPI app enters their UPI PIN, and authorizes the payment.
- Hand Over Cash & Earn Commission: Once the top UPI Cash Point Software shows a real-time transaction confirmation, the retailer hands over the physical cash and earns a commission or partner incentive on the withdrawal.
2. How Distributors Use the Software
- Network & Downline Management: Distributors (or master distributors) use the B2B dashboard to onboard, create, and manage a chain of sub-agents and retail merchants.
- Wallet & Liquidity Management: They handle virtual balance allocations, manage fund payouts, and ensure retailers have adequate liquidity to service daily cash-out requests.
- Real-Time Monitoring: Distributors track live transaction volumes, cash flows, and performance metrics across their entire regional merchant network.
- Commission Configuration: They oversee or help configure tiered commission margins and automated payouts for active downline retailers.
3. How Admins (Platform Providers & Fintechs) Use the Software
- Centralized Infrastructure Control: Aeps india manage the master dashboard linking banking networks, Trusted UPI Cash Point API, and B2B partners.
- API & Webhook Management: They maintain the NPCI-backed Secure UPI Cash Point API, dynamic QR generation engines, intent processing, and automated webhook push notifications for real-time settlement.
- Compliance & Security Oversight: Admins enforce KYC verification for onboarding partners, monitor transaction security, prevent fraudulent activity, and manage system-wide audit logs.
- Settlement & Ledger Reconciliation: They handle end-to-end clearing and settlement between participating Aeps india Server.
UPI Cash Point Business Opportunity
A UPI Cash Point business allows local shop owners and retailers to turn their stores into mini-ATMs, letting customers withdraw physical cash by scanning a dynamic QR code with apps.
Benefits for Retailers
- Commissions: Earn a fixed commission or percentage per successful cash-out transaction (varying by Aeps india often up to ₹10–₹15 per transaction).
- Higher Footfall: Customers coming in for cash withdrawals often stay to buy groceries or household goods, boosting core retail sales.
- No Cash-Handling Risk of Skimming: Cardless flow means no physical debit cards are handed over or exposed to cloning risks.
UPI Cash Point Commission
The UPI Cash Point commission structure varies depending on the transaction slab, the Aeps india and active merchant schemes.
Typical Slab-Wise Commission Structure
Retailers earn a small flat commission per successful cash-out transaction based on the amount dispensed:
- ₹500 – ₹999: ₹1 (Retailer Commission)
- ₹1,000 – ₹1,999: ₹2 (Retailer Commission)
- ₹2,000 – ₹2,999: ₹4 (Retailer Commission)
- ₹3,000 – ₹3,500: ₹7 (Retailer Commission)
- Higher Slabs (up to ₹5,000): Commissions can range up to ₹2 to ₹14 per transaction depending on volume tiers, monthly throughput incentives, and the aggregator platform used.
UPI Cash Point Charges
Aeps india does not charge any direct fee for UPI ATM cash withdrawals.
However, standard ATM limits and transaction fees apply:
- Free Monthly Limits: UPI cash withdrawals are now counted as part of your bank’s standard monthly free ATM transaction limits (5 free transactions at your own-bank ATMs; 3 free at other-bank ATMs in metro cities, or 5 in non-metro cities).
- Charges Beyond Free Limit: Once you exceed your monthly free ATM transactions, banks charge ₹23 plus applicable GST per financial transaction.
- Transaction Limits: The maximum withdrawal limit is capped at ₹10,000 per transaction (and remains subject to your daily UPI or bank-imposed caps).
Secure UPI Cash Point Transactions
You can complete a secure cash withdrawal without a physical card using either a UPI-enabled ATM or a local UPI Cash Point merchant (such as Fino or local retail agents).
Key Security & Limits
- No Card Required: Eliminates skimming, cloning, or physical card theft risks.
- Single-Use Codes: Dynamic QR codes expire quickly and cannot be reused.
- Transaction Limits: Generally capped at ₹5,000 per transaction at retail cash points and up to ₹10,000 per transaction at UPI ATMs, subject to your bank’s daily limits.
- Safety Rule: Never share your UPI PIN with the merchant or shopkeeper; always type it privately on your own device.
How Does UPI Cash Point Software Handle Failed Transaction
UPI cash point and cash-withdrawal software handle failed transactions through automated status checks, real-time reconciliation, and mandatory Reserve Bank of India (RBI) auto-reversal protocols.
Core Handling Mechanisms
- Real-Time Status Polling (Transaction Status Enquiry APIs): Modern UPI Cash Point Software continuously polls or queries the National Payments Corporation of India (NPCI) and banking partners to verify whether a transaction has succeeded, timed out, or failed before dispensing physical cash.
- Idempotency Checks: Every transaction carries a unique identifier (such as RRN or UTR). If a network timeout occurs and a request is retried, the system recognizes the duplicate ID to prevent double-debiting or multi-dispensing.
- Webhook & Callback Handlers: Server-to-server notifications alert the retailer dashboard and the backend engine the moment a transaction clears or drops, locking the cash-dispensing command if the payment does not return a confirmed SUCCESS status.
Refund & Reversal Timelines
- No Debit Failures: If the payment fails instantly prior to account debit, no money leaves the user’s account, and the cash point displays a “Transaction Failed” prompt.
- Debited but Failed / Un-dispensed Cash: If an account is debited but cash is not handed over due to a connectivity or terminal glitch, the software triggers an automated reversal (UPI-REV / RET).
- Regulatory Deadlines: Under RBI guidelines, merchant and assisted cash-point transactions must auto-reverse within T+1 to T+5 business days (typically processed or updated within 24 hours to 5 days).
- Delay Penalties: Aeps india exceed the mandated reversal window, a compensation of ₹100 per day applies to the customer’s account.
Dispute & Escalation Workflow
- Wait Window: Users and retailers are advised to wait up to 1 hour for automated reconciliation and status synchronization between the beneficiary bank, NPCI, and the issuer.
- In-App Dispute Raising: If the amount is not auto-reversed within an hour, the user or retailer logs a complaint directly inside the UPI app or merchant dashboard using the UPI Reference Number (RRN) or Transaction ID.
- Escalation Hierarchy: Unresolved claims escalate from the Aeps india support to dispute mechanism, and ultimately to the RBI Ombudsman if left unaddressed.
UPI Cash Point Software Requirements for Retailers
Retailers can turn their store into an NPCI-compliant UPI Cash Point (cardless cash withdrawal point) without needing a traditional Micro ATM machine, card swipe terminal, or biometric Aeps fingerprint scanner.
Software & Technical Requirements
- Authorized B2B / Fintech Platform: Retailers must use an approved UPI Cash Point software solution, app, or portal such as Aeps india.
- Dynamic QR Generation Capability: The UPI Cash Point software must support real-time generation of transaction-specific dynamic QR codes (one-time use, typically valid for 60 to 120 seconds) rather than a static store QR code.
Hardware Requirements:
- A basic Android smartphone, tablet, or POS terminal to run the partner application and display the dynamic QR code.
- No card reader (Micro-ATM) or Aeps biometric device is required.
KYC & Onboarding Documents:
- Valid PAN card and Aadhaar card of the retailer.
- Proof of shop/business establishment and active current or savings bank account linked for same-day/instant settlement.
- Branding Compliance: Display of official NPCI UPI Cash Point logos and wordmark guidelines (minimum digital size or print layout specifications) at the counter if mandated.
Transaction Workflow & Limits
- Enter Details: The retailer logs into the app, selects the UPI Cashout / QR ATM option, and enters the withdrawal amount and customer mobile number.
- Generate QR: A unique dynamic QR code appears on the retailer’s screen.
- Customer Scan & Authorize: The customer scans the QR using any UPI app and authenticates using their UPI PIN.
- Cash Handover: Once the retailer’s app confirms the transaction, physical cash is handed over to the customer.
Standard NPCI Transaction Caps:
- Maximum per transaction: ₹5,000
- Maximum per day: ₹10,000
- Maximum per month: ₹50,000
- Cooling period: 30 minutes between repeat transactions (typically capped at 2 transactions per day per customer profile).
- Retailer Earnings: Retailers earn a commission per successful cash-out transaction (ranging roughly from ₹2 to ₹14 depending on volume and Aeps india tiers).
Non-Obvious Tips
- No Static QR Reuse: Never print or save a dynamic cash-out QR code; each code expires quickly and must be generated fresh per request.
- Maintain Cash Reserves: Ensure your cash drawer has sufficient physical liquidity to match daily customer withdrawal demands before enabling the service.
Best UPI Cash Point Platform
Aeps india is a digital financial services and fintech platform in India that enables shopkeepers, retailers, and entrepreneurs to operate as a local mini-ATM and UPI Cash Point.
Key Benefits for Retailers
- Extra Income: Earn guaranteed commissions on every cash withdrawal transaction.
- Higher Footfall: Attract more customers to your Kirana store, mobile shop, or service outlet.
- All-in-One Platform: Along with UPI Cash Point, Aeps india offers AEPS (Aadhaar Enabled Payment System), Micro ATM, Money Transfer (DMT), Bill Payments, and PAN Card services.
- No Debit Card Needed: Customers do not need a physical debit card to withdraw cash.
UPI Cash Point Software Cost in India
The cost structure for a UPI Cash Point (Interoperable Cardless Cash Withdrawal / Micro ATM software) solution depends on whether you use a plug-and-play platform or build/white label UPI Cash Point a custom UPI Cash Point API integration.
1. Software Setup and Integration Costs
- Pay-as-you-go / Standard Platform: ₹0 to ₹12,000 UPI Cash Point Software setup fee with zero monthly commitments; costs are managed via per-transaction commission or service structures.
- White-Label / Custom B2B Setup: ₹15,000 to ₹1,20,000+ depending on UPI Cash Point software customization, admin dashboard access, branding, and licensing.
- Zero-Cost Models: Aeps india offer zero onboarding fees and zero recurring subscription or renewal charges, monetizing through transaction volume splits.
2. Annual Maintenance Charges (AMC)
- Standard AMC: Ranges from ₹10,000 to ₹40,000 per year for server hosting, security patches, NPCI/bank switch uptime, and technical support.
3. Retailer & Agent Commission Structure
- Unlike paying a flat UPI Cash Point software fee per cash-out, agents and retail cash points generally operate on a per-transaction payout model:
- Retailers earn commissions ranging from ₹2 to ₹14 per transaction (or up to ₹8+ depending on the slab amount and platform tier).
- Some networks allow retailers to operate with counter credit limits (e.g., up to ₹15 lakh) to facilitate high-volume cash dispensing.
4. Customer-Side Limits and Fees
- Cardless Withdrawal Limit: Typically capped at ₹5,000 to ₹10,000 per transaction (subject to daily caps like ₹10,000/day or ₹50,000/month, or bank-specific ICCW rules).
- Customer Fees: UPI cash withdrawals at ATMs or cash points count toward standard free monthly ATM transaction quotas (5 free at own-bank, 3–5 at other banks); exceeding the quota incurs ~₹23 plus GST per transaction. Standard P2P UPI transfers remain free.
Features UPI Cash Point Software
UPI Cash Point software enables local merchants, kirana stores, and Business Correspondents (BCs) to turn their shops into cardless cash-dispensing counters using Unified Payments Interface (UPI).
Core Features of UPI Cash Point Software
- Dynamic QR Generation API: Instantly creates a single-use, transaction-specific QR code mapped directly to the requested withdrawal amount.
- Intent & Payment Processing API: Handles app-to-app redirection or direct scans, letting customers authorize withdrawals inside their preferred UPI app using their UPI PIN.
- Real-Time Transaction Status Enquiry: Provides instant validation and tracking (success, pending, or failed) for both the merchant and the consumer before handing over physical cash.
- Webhook & Push Notifications: Delivers automated, real-time push notifications to the merchant or fintech server upon settlement.
- Cardless & Biometric-Free Operation: Requires no physical debit cards, card swipe machines, Micro ATM hardware, or Aeps fingerprint scanners only an Android smartphone or partner app.
- Interoperability: Backed by the National Payments Corporation of India (NPCI) and partner banks, allowing customers from any participating bank to withdraw cash.
- Multi-Account Flexibility: Allows customers to switch between multiple bank accounts linked inside their UPI app during the withdrawal process.
- Retailer & Commission Management: Tracks per-transaction commissions, partner incentives, and merchant working-capital or credit limits (such as extensions up to ₹15 lakh).
Security Measures in UPI Cash Point Software
UPI Cash Point software enables authorized Aeps india to act as cardless cash-out locations using the NPCI (National Payments Corporation of India) UPI ecosystem.
Key Security Features of UPI Cash Point Software
- Single-Use Dynamic QR Codes: The system generates a fresh, time-sensitive, single-use QR code for every withdrawal request, stopping screenshot reuse or tampering.
- Mobile-Based UPI PIN Authorization: Customers authorize the transaction directly on their own smartphone inside any UPI-enabled app using their private UPI PIN.
- Cardless Architecture: Transactions eliminate physical debit cards, completely removing risks linked to card skimming, cloning, or physical theft at merchant desks.
- Real-Time Bank Verification & Webhooks: Status Enquiry APIs and instant webhook callbacks verify transaction success straight with the banking network before cash is handed over.
- Built-In Transaction Limits & Controls: Software includes daily and per-transaction caps (typically aligned with NPCI guidelines, such as up to ₹10,000 per transaction with cool-off periods) to monitor and control cash flows.
- Centralized Dashboard Monitoring: Aeps india to track live transaction logs, audit merchant activity, and manage real-time settlements.
Best UPI Cash Point Company
Aeps india is a digital financial services and fintech platform in India that enables retailers, kirana stores, and local shop owners to operate as a UPI Cash Point or QR ATM.
Additional Services Offered by Aeps india
- AEPS (Aadhaar Enabled Payment System): Biometric-based cash withdrawals and balance inquiries.
- Micro ATM: Card-based cash withdrawal services.
- Money Transfer (DMT & Indo-Nepal): Domestic and cross-border money transfers.
- Bill Payments & Recharges: Utility bill pay and mobile/DTH recharges.
- Financial Services: PAN card creation and ITR filing assistance.
Top UPI Cash Point Company
Aeps india only one of the Top UPI Cash Point providers and platforms in India enable local retailers, kirana stores, and business correspondents to offer cardless cash withdrawals using dynamic QR codes.
- Maximum per transaction: ₹5,000
- Daily transaction limit: ₹10,000
- Monthly transaction limit: ₹50,000
- Transactions allowed per day: Up to 2
- Cooling period: 30 minutes between consecutive transactions
Note: These limits are based on Aeps india currently available UPI Cash Point information and may be revised from time to time.
Aeps india one of The UPI Cash Point Software Provider for Your Business
Aeps india one of the right UPI Cash Point software for your business requires evaluating key operational, financial, and technical factors to ensure smooth cash-out services, regulatory compliance, and reliable daily reconciliations.
Key Factors to Choose UPI Cash Point Software
- Dynamic QR Code Generation: Look for UPI Cash Point software that generates transaction-specific dynamic QR codes rather than static ones, ensuring each cash withdrawal request links cleanly to the exact amount and user session.
- Real-Time Transaction Confirmation & Alerts: The UPI Cash Point platform must provide instant, crystal-clear status notifications and audio-visual payment confirmations before you hand over physical cash.
- Automated Settlement & Payout Cycles: Check how fast the UPI Cash Point software processes same-day or real-time settlements into your working capital account to prevent cash flow crunches.
- Commission & Fee Structure: Evaluate the profit margins or retailer commissions offered per cash withdrawal transaction against any monthly software-as-a-service (SaaS), smooth UPI Cash Point API integrating, or portal maintenance fees.
- No-Biometric / Frictionless Flow: Ensure the system operates seamlessly via standard UPI PIN or dynamic QR app authorization without heavy hardware dependencies like biometric Aeps fingerprint scanners (unlike traditional AEPS terminals).
- Comprehensive Ledger & Reconciliation Dashboard: Aeps india should offer detailed daily transaction logs, exportable settlement reports, and automated tracking to match physical cash drawer counts with digital inflows.
- API & Panel Scalability: If you run a B2B network, distributor chain, or micro-ATM network, verify whether the software supports white label UPI Cash Point API or multi-tier retailer management panels.
- Security & Regulatory Compliance: Ensure the UPI Cash Point Software complies with National Payments Corporation of India (NPCI) guidelines and utilizes robust bank-grade encryption for all transaction handshakes.
How Aeps India Helps Businesses Set Up UPI Cash Point Software
Aeps india is an UPI Cash Point software providers help businesses, fintechs, and retailers turn physical stores into cardless cash withdrawal hubs.
How Providers Enable UPI Cash Point Software
- Dynamic QR Generation: The UPI Cash Point Software creates single-use, time-bound QR codes tied directly to specific cash-out amounts requested by the customer.
- Universal App Integration: Aeps india connect the system to National Payments Corporation of India (NPCI) infrastructure so customers can scan and pay using apps.
- Hardware-Free Setup: Aeps india eliminate the need for physical ATM machines, debit cards, Aeps biometric fingerprint scanners, or Aadhaar linkage.
- Real-Time Webhooks & Notifications: Instant transaction alerts and webhooks notify the merchant and system as soon as a payment clears.
- Ledger Auto-Reconciliation: The UPI Cash Point Software matches Virtual Payment Addresses (VPAs) and transaction IDs automatically to keep merchant accounts and cash balances updated.
- Commission & Margin Management: Built-in dashboards calculate agent, retailer, or distributor margins and payouts for every successful cash-out transaction.
- Transaction Limits & Controls: Aeps india embed daily, weekly, and monthly threshold controls (such as per-transaction or daily caps) to maintain compliance and risk management.
- White-Label & B2B Solutions: Aeps india offer white label UPI Cash Point platform so Aeps india can scale their own retailer and agent networks.
Future of UPI Cash Point Software in India
UPI Cash Point software enables local merchants and Kirana stores to act as cardless, micro-ATMs where customers can withdraw cash by scanning a QR code with their UPI app.
Core Future Trends of UPI Cash Point Software
- Cardless & Biometric-Free Expansion: UPI Cash Point Software is shifting entirely away from physical debit cards and hardware scanners, relying instead on real-time app authentication and dynamic QR codes.
- Automated Reconciliation & Real-Time Webhooks: Modern UPI Cash Point platform integrate instant backend reconciliation tools that match transaction IDs and Virtual Payment Addresses (VPAs) to merchant ledgers automatically, cutting down manual bookkeeping.
- Embedded Commission & Margin Tracking: UPI Cash Point Software architectures are building in automated agent/retailer commission calculators to track real-time margins per cash payout, turning local shops into micro-banking hubs.
- Offline & Low-Connectivity Capabilities: Integration with offline mechanics (such as UPI Lite, sound-wave, or NFC protocols) allows UPI Cash Point software to process or buffer localized micro-transactions even when network latency or dropouts occur.
- Value-Added Retail Ecosystems: UPI Cash Point software is evolving past single-function withdrawals into super-app modules that bundle cash-out services with utility bill payments, mobile recharges, and inventory micro-lending based on digital ledger histories.
- Stricter Compliance & Fraud Mitigation: New security layers including dynamic single-use QR generation, smart anti-scam alerts, and biometric/face-ID checks are being hardcoded into vendor software interfaces.
Final Words
UPI Cash Point Software Work is an important topic for businesses looking to understand how customers can withdraw cash through supported UPI-based cash withdrawal services. With the right software solution, eligible businesses can manage transactions, monitor payment status, maintain transaction records, and provide a smoother service experience through an organized digital UPI Cash Point platform.
Before choosing a Aeps india is an UPI Cash Point Software provider, check the available transaction features, integration options, admin dashboard, reporting tools, security controls, support services, and applicable onboarding requirements. Also, understand the difference between UPI-based cash withdrawal and Aadhaar Enabled Payment System (AEPS), as they use different transaction flows and eligibility requirements.
A UPI Cash Point Software turns a local retail shop, Kirana store, or business correspondent outlet into a card-free cash withdrawal counter. It allows customers to get physical cash using only their smartphone and a UPI app, without needing a physical debit card, ATM, or buy Aeps biometric device (AePS).
Aeps India can help businesses explore suitable digital banking and Upi cash point software solutions based on their operational needs and supported integrations. Whether you are planning to launch a cash point service or expand an existing digital service business, selecting the right solution can help you manage operations more effectively.
If you want to understand the available features and integration options, visit Aeps India Contact Us to discuss your requirements. Choose a Aeps india that fits your business model, follows applicable rules, and offers the support needed for reliable day-to-day operations.
UPI Cash Point Software with Aeps India
Looking for UPI Cash Point Software for your digital payment business? Contact Aeps India to discuss software features, setup options and solutions suited to your business requirements.
FAQs: UPI Cash Point Software Work – Aeps India
UPI Cash Point software helps authorised merchants and Business Correspondents provide cash withdrawal services through a UPI-based process. The customer visits a participating outlet, scans its displayed QR code using a UPI app, checks the transaction details, and authorises the payment. Once the merchant or service system confirms successful receipt, the merchant hands over the cash. The software helps manage the transaction status and related records.
UPI Cash Point software is a digital platform used to support UPI-based cash services at authorised Aeps india website. Depending on the Aeps india and integration, it may include merchant access, QR-based transaction workflows, transaction history, settlement records, reports, and administrative controls.
The usual process is:
Visit an authorised UPI Cash Point outlet.
Tell the merchant how much cash you want to withdraw.
Scan the outlet’s displayed QR code using your UPI app.
Verify the amount and recipient details.
Approve the payment using your UPI app’s required authentication.
Wait for the transaction to be confirmed successful.
Collect the cash from the merchant.
Always verify the final transaction status before accepting or handing over cash.
UPI Cash Point software can help authorised retailers manage customer cash requests, view transaction statuses, access transaction history, and maintain records for reconciliation. Depending on the Aeps india, retailers may also receive settlement reports and commission details. Actual features depend on the platform and the retailer’s approved service arrangement.
No. UPI Cash Point and Aadhaar Enabled Payment System (AEPS) are different transaction services. UPI Cash Point uses a UPI-based payment journey, generally involving QR scanning and customer authorisation through a UPI app. AEPS uses Aadhaar-based authentication through an authorised banking service. The applicable requirements and transaction workflows differ.
A standard UPI Cash Point transaction does not inherently require a biometric device. The customer authorises the transaction through the supported UPI app and its authentication process. Hardware and onboarding requirements can vary depending on the UPI Cash Point services offered by the Aeps india.
If a transaction fails or shows a pending status, check the transaction reference and verify the status through the approved system before repeating the transaction or handing over cash. If the customer’s account has been debited but the transaction remains unresolved, follow the Aeps india official dispute and reversal process. Keep the transaction record for support and reconciliation.
Yes, platforms that include transaction reporting can allow authorised retailers or administrators to review available transaction details, such as reference numbers, amounts, timestamps, and transaction statuses. The exact information and reporting options depend on the Aeps india and its integration.
A business should first check its eligibility and register through a participating Aeps india as applicable. It must complete the required verification, obtain service activation, understand cash-management and dispute procedures, and use the approved transaction workflow. Buying UPI Cash Point software alone does not automatically authorise a business to provide regulated banking services.
The permitted amount depends on the applicable service rules, transaction limits, customer bank limits, and the cash available at the outlet. NPCI’s published UPI Cash Point product information specifies a per-transaction limit of ₹5,000, subject to other applicable regulatory limits. Businesses should verify the current rules with their participating bank or authorised Aeps india before offering the service.
Integration may be possible when an authorised Aeps india offers a supported UPI Cash Point API or UPI Cash Point software integration. Depending on the approved service, integration may support transaction initiation, status updates, merchant management, reporting, and reconciliation. Businesses should verify UPI Cash Point API documentation, access permissions, security requirements, and operational responsibilities before implementation.
Businesses should assess merchant and administrator access, transaction-status tracking, reporting, reconciliation, security controls, integration documentation, technical support, scalability, and transparent pricing. They should also verify that the proposed service is supported by the relevant authorised banking or payment arrangement.
A retailer may earn commission or other agreed remuneration if the participating bank or authorised Aeps india offers it under its commercial arrangement. The rate, eligibility, settlement schedule, and deductions vary by Aeps india and contract. Retailers should confirm the written commission terms rather than rely on an assumed fixed earning per transaction.
Aeps India can use this section to explain its actual UPI Cash Point software or integration offering, including supported features, onboarding requirements, Aeps india dependencies, reporting, technical support, and pricing. Before publishing, include only services and capabilities that Aeps India can verify and provide. Businesses should confirm the relevant authorisation and integration arrangements before going live.
Contact Aeps India to discuss your business model, intended transaction workflow, merchant network, integration needs, and reporting requirements. Ask for a feature demonstration, written pricing, UPI Cash Point API or integration documentation where applicable, and details of the authorised service arrangement. Confirm the onboarding and compliance requirements before launching the service.
UPI Cash Point API in India: Complete Guide to Cash Withdrawal & API Integration
UPI Cash Point Service: Complete Guide for Retailers & Businesses (2026)
UPI Cash Point: Complete Guide to UPI Cash Withdrawal for Retailers in India (2026)
About Author

